**"Truth may be stretched thin, but it never breaks, and it always rises above falsehood, as oil floats on water." **Miguel de Cervantes
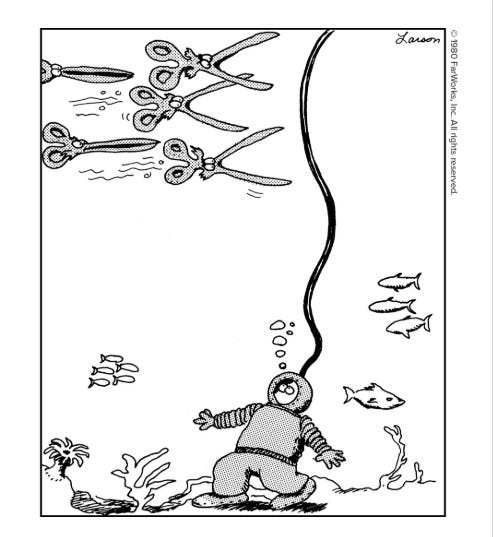
A diver on the ocean floor. Boots, brass helmet, the whole 1920s rig. He is watching a fish. Above him, unseen, a school of scissors is swimming down toward his air hose.
The whole gag, and it takes one line to explain, which is how you know it is a good one.
Here is what makes it a market cartoon and not a joke about scissors. The diver is not doing anything wrong. He is doing his job, at depth, competently, looking at the thing in front of him. Everything he depends on is a thin line he cannot see, running up to a surface he is not watching. The hose is not a decision he makes every morning.
A condition he assumes.
Until it is not.
Now try the list.
An Attorney General’s office run as a personal instrument. Inspectors general fired in batches, on a Friday, without the notice the statute requires. Emergency powers invoked for tariffs that are not emergencies. And a Defense Department that is forbidden by law from making equity investments in foreign countries taking a 35% stake in an operator handed seventeen Venezuelan oil fields on hundred-year concessions, from a government whose legitimacy Washington’s own official position denies, which means Caracas cannot sign a binding contract in the first place.
-from Jonathan V. Last on
The Bulwarkwebsite
Read that one twice. Against our law going out, against their constitution coming in, and announced like a press release.Then add the ordinary ones, which are the ones that matter more. A Federal Reserve chair installed after his predecessor was publicly worked over for the better part of a year. Refiners hauled into a closed room and pressed on gasoline prices eight weeks before an election. A stopgap that punts every difficult number past the midterms, 370 to 48, because the single thing both parties agree on is that nobody wants to campaign during a shutdown.
None of those is the scissors. All of them are.
Gallup has asked Americans the same question every year since 2006: is corruption widespread throughout the government? The answer ran in the low 70s for two decades, through Bush, through Obama, through the first Trump term, through Biden. Now 89, the highest in the series, and the line does not bend at the end.
It goes vertical.
I want to be careful here, because this is where people go wrong in both directions. That number is not a verdict on one administration. A reading on the hose.
Which brings me to the question I cannot answer, and I have been chewing on it for weeks.
What gets restored?
The written things, probably. Statutes get re-passed. Courts eventually rule. A norm that turns out to have been a law gets litigated back into place: slowly, expensively, and mostly intact. I would not bet against the paperwork.
The unwritten ones are the problem. The reason a President did not call a company about its stock price was never a statute. Doing so would simply have been ‘unthinkable’. Unthinkable is not a rule. Habits are not rules, and a habit broken once is just a precedent with better manners. The next one does not have to argue for the power.
He only has to point at the last guy.
Cheaper than an argument, and faster.
You do not splice an air hose at depth. You go up, or you do not.
And… well. You are reading a market letter, so I am not going to pretend I can price that for you. What I can tell you is that, in the seven hours before I sat down, gold went up $108 while the barrel came off its high, on the same war, in the same session.
One of those is a ‘war trade’. The other one is about the money.
**THE MONEY MOVED. THE CURVE DID NOT.**Gold 4,522.60, +2.45%, bid 3.80 off its session high, while 2Y/10Y/30Y printed 4.39/4.79/5.27 two sessions running.Wrong ifgold closes under 4,414.60 with the dollar higher.**THE FRONT END STOPPED CONFIRMING.**The weakest private payroll print since January missed by 9,000 and the 2Y closed unchanged. Five sessions of leadership, then silence.Wrong ifthe 2Y goes through 4.50%.**THE ARM WENT ON SMALL.**Brent through the 95.00 line, taken as a quarter unit call spread inside the inflation trade rather than beside it.Wrong ifBrent settles below 95 within two sessions.**ONE BET, AND THE UNION IS BIGGER THAN EITHER HALF OF IT.**Front end at cap, 3.0 of 3. Inflation 4.0 of 4. Gross 16.0. Friday takes ten of twenty-nine lines the same way.
Gold 4,522.60, up $108 and 2.45%, sitting 3.80 off its session high, with the dollar offered against both the euro and the yen.
The Treasury curve printed 4.39, 4.79 and 5.27 on September 1st and printed the same three numbers again on September 2nd. 2s10s +40bp, unchanged.
Brent 95.94 after trading 97.62 overnight. Fifth spike and fade of this war, and the first settle through the 95.00 arm line.
USDJPY 155.50, down 2% off a 158.97 high, with the Bank of Japan reported to be leaning toward a quarter point on the 18th.
Inside financials on September 2nd, credit services +3.21% against listed venues and information (2.01). 522 basis points of dispersion on a sector that averaged +0.06%.
One idea organizes this note.
**Everything that is not the dollar got bid last night, and the curve everybody has been arguing about did not move at all.**That is a different regime from the one I wrote about yesterday, it arrived inside a single session, and it will not get written up this way because the war headline is louder and easier.START WITH WHAT DID NOT HAPPEN, because the absence is the load-bearing fact.
Three tenors. Two sessions. Zero basis points. 2s10s at +40 and 2s30s at +88, both unchanged.
For a week this book has been paid by a front end that led every session, and I demoted the long-end line yesterday because the front end kept doing the work the back end’s thesis claimed. Then Wednesday happened. ADP printed 38,000 private jobs, the weakest since January, a 9,000 miss, and the two-year closed exactly where it opened the day before.
Five sessions of leadership is strong evidence. One session of silence is weaker evidence wearing the same suit.
The tape did not disagree with me. It just.. stopped.
NOW WHAT DID HAPPEN.
Gold 4,522.60, up $108. Not up on the open and fading, which is what a headline pop looks like. Up, and sitting 3.80 off a session high of 4,526.40 at nine in the morning. The yen through 155.50 from a 158.97 high, a 2% session. The euro at 1.16246, at the top of its range. And the barrel, on the identical war, up 0.32% and 1.68 BELOW its own overnight high of 97.62.
Same tape, same seven hours, two verdicts. The commodity that pays on a supply disruption refused, for the fifth time this war. The metal that pays on the currency was bought at the highs.
Fifth ‘spike and fade’ of this war. Fifth.
**Flight Check:**gold bid, bonds bid, yen bid, dollar offered. Yesterday that read gold offered, bonds offered, yen bid, dollar bid, and I called it a discount-rate rotation. Three of four legs inverted overnight. When everything is bid except one thing, the one thing is the trade.
THE CASE AGAINST, and it is a serious one.
The honest alternative is that this is two central banks and not a currency. Waller said this morning that the September decision is heavily influenced by August CPI, that he is inclined to support a hold if disinflation continues, and that current policy is only slightly restricting demand. Yields went to session lows and futures to session highs on the sentence. Meanwhile the Bank of Japan is reported to favor a quarter point on the 18th. A dovish Fed against a hawkish BOJ is a rate differential, and gold is the asset with no coupon, so gold rallies. That read requires no story about the money at all, and it is probably 60% of what happened. A dollar offered on a dovish surprise does not have to mean anything about the currency itself.
Second, and this one is uncomfortable. Gold at 4,522.60 is still BELOW its own 200-day at 4,597.04. The benign read is that it ran to 5,626.80 earlier this year and the 200-day is the wrong yardstick for a metal still working off that hangover. Fair. A 2.45% session inside a downtrend may simply be a bounce until it clears 4,597, and one candle does not make a regime. Which is small, and one session, and I am not going to pretend otherwise.
Third, one session is one session, and I said exactly that yesterday about a financials sort which has since inverted on me. It did precisely that: the reinsurance-versus-life pair swung 70bp the wrong way on a curve that did not move a single basis point, and the trigger I had written could not fire on a flat tape. That evidence sits in this paragraph, free, because a variant view a reader cannot check is an advertisement rather than a view.
Where I part company with the two-central-bank read is the size and the company it keeps. 2.45% is a large number for 25bp of expected path, the dollar is offered against everything and not just the yen, and the Dutch central bank has spent March to August moving roughly 86 metric tons of gold, about $12 billion of it, out of New York and Ottawa and into London, citing increasing geopolitical unrest (Bloomberg). Central banks moving custody is not a rate trade. Custody is a counterparty trade, and counterparty trades are what the hose looks like from the inside.
**THE POLICY PATH, PRICED.**Futures had roughly 66% on a September hike a week ago and roughly 60% this morning. Waller did not kill it. He moved the decision off the meeting and onto a print nine days out, and options flow now reads as positioning for a September skip while keeping some premium for December. If you own five tickets that need the front end to sell off, and a voting governor has just said the vote depends on one number, then you do not own a meeting trade any more. You own a CPI trade, and you should say so out loud.
Here is the part that gets left out. Core PCE, year over year, is running 3.7%, and that is the number the committee will look at. Core PCE on a two-month annualized basis has rolled to roughly 1.7%. The backward window is hawkish and the forward window is dovish, the series has whipsawed like that three times since 2024 without breaking trend, and this is not a call that inflation is beaten. The claim is narrower: the committee will probably act on the slower window, and the trade after the meeting runs opposite to the trade into it.
**LABOR IS THE OTHER HALF, AND IT IS WEAKER THAN THE HEADLINE.**ADP at 38,000. A separate private read has August nonfarm rising about 36,500 month over month. Challenger cuts jumped. Consensus tomorrow is 65,000 with unemployment at 4.2%.
Take unemployment and subtract annual nonfarm payroll growth and you get one number for how hard it is to find work. That number is currently worse than roughly two thirds of the months since 1950. Not recessionary. Not fine either.. and it is the second read this week pointing the same way.
And the counterweight, which is why I am not simply short the front end into tomorrow. Job openings per unemployed worker, pushed forward nine months, has been a decent lead on wage inflation, and it has turned up off the 2024 low. Softer hiring and firmer wages at once is the exact composition that keeps a hawkish committee hawkish while the growth data rolls. Stagflationary in shape, and the branch this book is least well built for.
**THE WAR’S JOB IN THIS NOTE IS THE ARM LEVEL, NOT THE DIRECTION.**Six months in, and the Pentagon is quietly extending deployments rather than winding down (Wall Street Journal). Iran destroyed the Navy’s logistics base in Bahrain on day one, and supply ships now run 2,200 miles to Diego Garcia, or 3,700 to Singapore through the Strait of Malacca (New York Times). Not a campaign with an off-ramp. A campaign with a supply chain problem.
The second-order effects are where the money is. European gas storage is 65% full, the lowest going into a winter in at least fifteen years, because buyers bet the war would end and Qatari cargoes would come back through Hormuz. LNG has printed a 3.5 year high and Asian and European buyers are bidding against each other for the same cargoes (Wall Street Journal). Russian and Ukrainian grain exports have roughly halved on attacks around Odessa and Novorossiysk, from a combined 27% of world grain trade, and wheat has gone with it (Eurointelligence). Diesel printed $5.783 a gallon, the highest since mid-2022 and inside three cents of the June 2022 record.
None of that makes me chase a 97 print. All of it is why the 95.00 line was the right trigger and why it went through last night. A conflict with a resupply channel and no negotiating table does not resolve and does not escalate decisively, and two constrained parties escalate in gestures. Gestures make a tape that spikes and mean reverts, five times now.
So the arm goes on at a quarter, as a call spread rather than an outright, because when the trigger level and the settle sit a few cents apart the size should say so.
**08:30 ET, jobless claims and the trade balance.**The July goods and services deficit came in at $88.6bn, up 24.4% on June, driven by computer and tech equipment imports for the AI build. A trade gap widening on capital goods is a different animal from one widening on consumption, and the market keeps pricing it as though it were the same.**10:00 ET, ISM services and factory orders.**Services carries the prices-paid line, and prices-paid is what a committee reading the backward window looks at first.**Through the session, the barrel.**A second settle above 95.00 confirms the arm rather than firing it again.
**The two biggest movers this morning contradict each other on the same theme, and I am not going to resolve it for you.**One says AI demand is accelerating and the other says the market has stopped paying for it.**BROADCOM, 367.24 into the print, down about 2.6% after it.**AI chip revenue +221% year over year to $16.7bn. Total revenue $29.59bn, up 86%, a record. Guided AI revenue to roughly $115bn in fiscal 2027 and $230bn in 2028. The stock fell.**So what:**when a company doubles its forward AI revenue guide and the equity goes down, the demand is not in question and the multiple is. Memory cost is eating the margin, and a guide does not fix a supply chain.**SNOWFLAKE, 305.84 on the close, up about 25% pre-market.**Product revenue accelerated, full-year guide raised, the AI assistant driving incremental seats.**So what:**the same dollar that shrugged at 221% hardware growth paid 25% for software beating on monetization. Value is moving from the people selling picks to the people selling what the picks dug up.**NVIDIA buying Hugging Face for roughly $13bn.**18 million developers, 200,000 companies, three million models, open source commitment maintained.**So what:**the largest supplier of shovels just bought the marketplace, which tells you it agrees with Snowflake’s tape rather than with its own.
Behind the wall this morning: the financials sort that inverted on me in one session and what it cost, including 522 basis points of subsector dispersion on September 2nd and the 58bp reversal in the reinsurance-versus-life pair on a curve that did not move a basis point. Two intra-sector financials expressions, both dollar neutral, one of them the inverted side of the worst line in the record. The full sheet, twenty-nine live lines with the factor each one monetizes and the condition that kills it, the netting arithmetic in units against the caps, and the front-end failure that neither half of the book could see on its own. The positioning picture, including a global hedge ratio at 41%, its lowest since at least 2015. And the decision tree, with two weights that moved ten points and now sit twenty apart.
Subscribe at marketmusing.com.