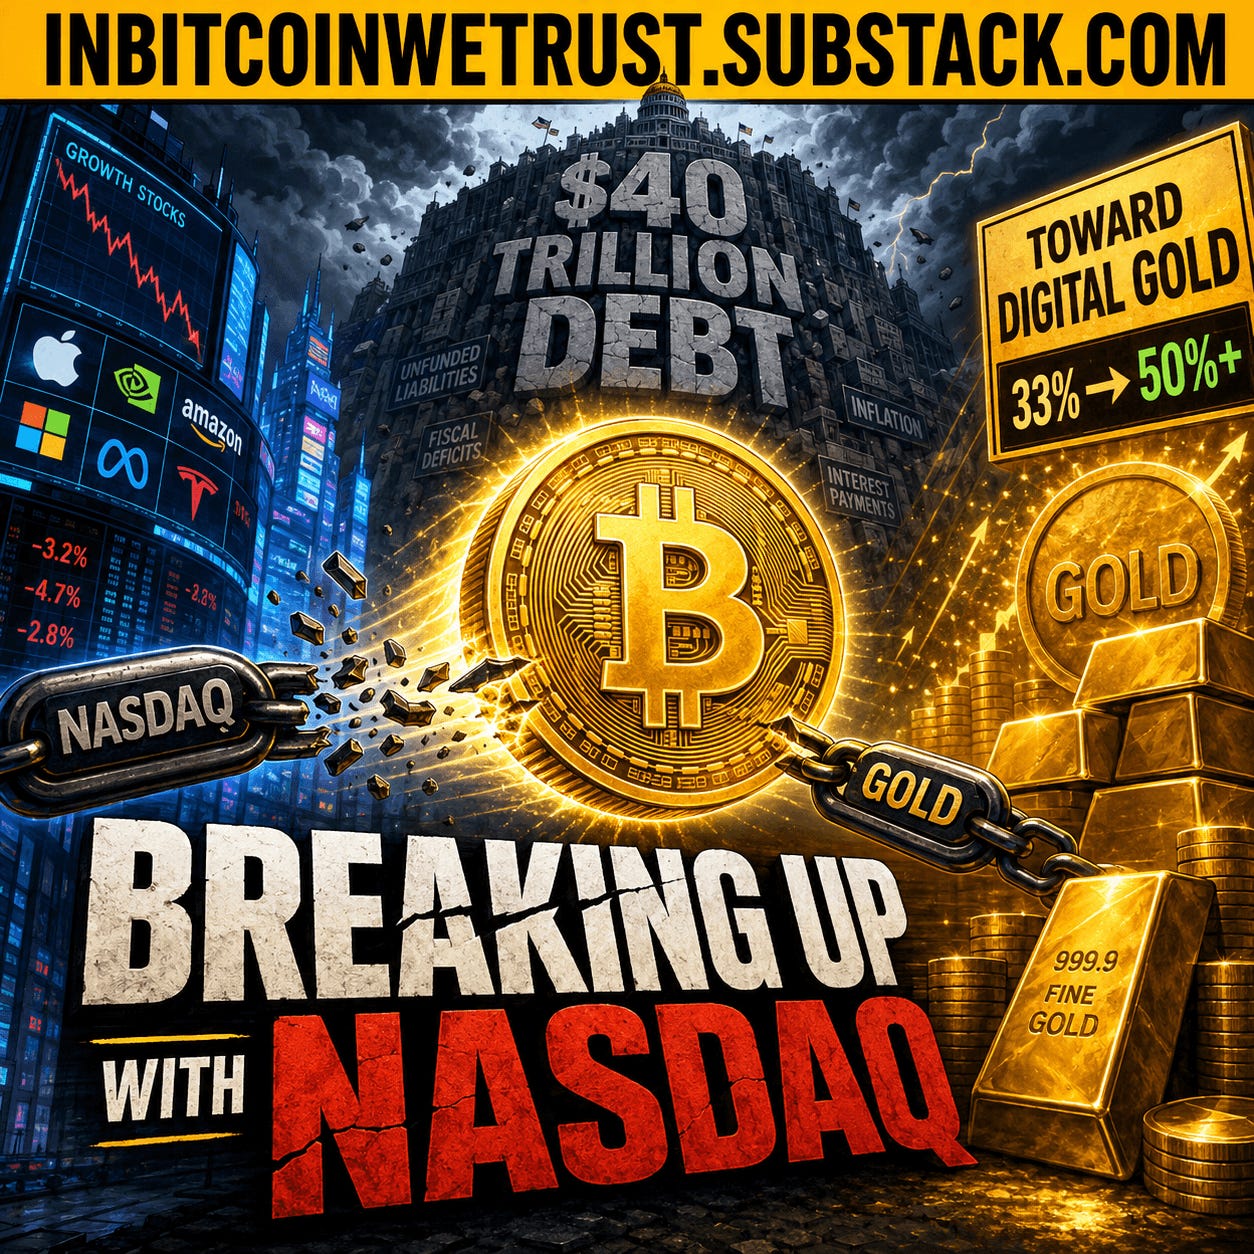
Bitcoin’s 90-day Nasdaq correlation has collapsed to 33% while its correlation with gold has surged above 50%. If this survives the next market panic, Bitcoin may finally be changing what kind of asset investors believe it is.
For years, Bitcoin had an identity problem.
Bitcoiners called it digital gold. Wall Street traded it like leveraged Nvidia.
The Federal Reserve raised rates? Bitcoin fell with tech.
Liquidity flooded markets? Bitcoin ripped with tech.
The Nasdaq sneezed? Bitcoin caught pneumonia.
It didn’t matter that Bitcoin had a fixed supply. It didn’t matter that nobody could print another 10 million BTC. It didn’t matter that Satoshi Nakamoto designed a monetary network rather than an AI company.
When investors wanted risk, Bitcoin behaved like risk.
When investors dumped risk, Bitcoin often got dumped harder.
That was the uncomfortable reality behind the “digital gold” narrative.
But something unusual is happening now.
According to research published by Grayscale on August 27, Bitcoin’s 90-day rolling correlation with the Nasdaq 100 has fallen from above 60% to roughly 33%.
At the same time, Bitcoin’s correlation with gold has moved from almost zero at the beginning of 2026 to:
above 50%.
Grayscale describes the move as a potential return of the “debasement trade.”
Bitwise is seeing something similar.
Its latest data show Bitcoin’s correlation with gold at a six-year high, its Nasdaq correlation around a one-year low, and its relationship with the U.S. Dollar Index significantly negative.
Those are not small changes. But the timing may be even more important than the percentages.
Because while Bitcoin appears to be moving away from tech and toward gold, America’s gross federal debt has crossed: $40 trillion.
The Congressional Budget Office projects another $1.9 trillion federal deficit in fiscal 2026, equal to about 5.8% of GDP. CBO expects deficits to remain historically large and public debt to continue climbing over the coming decade.
Meanwhile, long-term government borrowing costs are rising again.
The U.S. 10-year Treasury yield is hovering near 4.8%, while bond markets around the world are struggling with higher inflation, massive government borrowing needs and an explosion of private-sector debt issuance linked partly to the AI infrastructure boom.
Put those developments together and a fascinating possibility emerges:
Bitcoin may finally be moving from the AI trade to the debt trade.
From: **high-beta technology proxy **toward: scarce monetary asset.
Not because Bitcoin changed. Because the macroeconomic problem investors are trying to solve changed.
And if this behavior survives the next genuine market shock, we may be watching something far more important than another Bitcoin rally.
We may be watching an asset class change in real time.
Bitcoin has always looked like gold conceptually.
Limited supply.
No central issuer.
Globally tradable.
Hard to confiscate when properly self-custodied.
No sovereign balance sheet behind it.
No monetary-policy committee deciding how much should exist.
Gold’s above-ground supply expands slowly because extracting new gold requires enormous physical effort.
Bitcoin’s supply expands according to code.
Approximately every four years, new issuance is cut in half.
Maximum supply: 21 million BTC.
The analogy is obvious. But financial markets do not care about analogies. They care about behavior. And for long stretches, Bitcoin behaved nothing like gold.
Gold traditionally attracts capital when investors become nervous about:
inflation,
currency credibility,
geopolitical instability,
sovereign debt,
financial-system risk.
Bitcoin frequently attracted capital when investors became excited about:
liquidity,
technology,
growth,
speculation,
risk appetite.
Those are very different regimes.
Gold says:
protect me.High-growth technology says:
multiply me.
Bitcoin spent much of its history trying to be both.
The AI boom reinforced Bitcoin’s high-beta identity.
Throughout 2025, markets became increasingly dominated by:
Nvidia.
Semiconductor spending.
Data centers.
AI capex.
Hyperscalers.
Growth stocks.
Risk capital.
When markets wanted AI exposure, capital flowed aggressively into technology.
Bitcoin often participated in the same liquidity regime.
Grayscale notes that for much of the past year Bitcoin behaved more like a high-beta risk asset than a monetary hedge.
That distinction matters.
Imagine two investors.
Investor A buys Nvidia because they believe: AI will transform productivity and generate enormous profits.
Investor B buys Bitcoin because they believe: scarce digital money becomes more valuable when sovereign balance sheets deteriorate.
Those are completely different theses.
But if both assets rise and fall together because the same marginal capital trades them as “risk-on,” Bitcoin’s theoretical monetary characteristics become almost irrelevant to short-term market behavior.
That is exactly what frustrated Bitcoiners.
Bitcoin’s code said:
hard money.The market said:
volatile tech stock without earnings.
Microsoft’s Maia 300 could turn one of Nvidia’s biggest customers into its own chip supplier — and the real threat isn’t replacing Nvidia. It’s making Nvidia optional.
At the end of 2025, Bitcoin’s 90-day correlation with the Nasdaq 100 exceeded 60%.