“Almost everything will work again if you unplug it for a few minutes, including you.” ~Anne Lamott
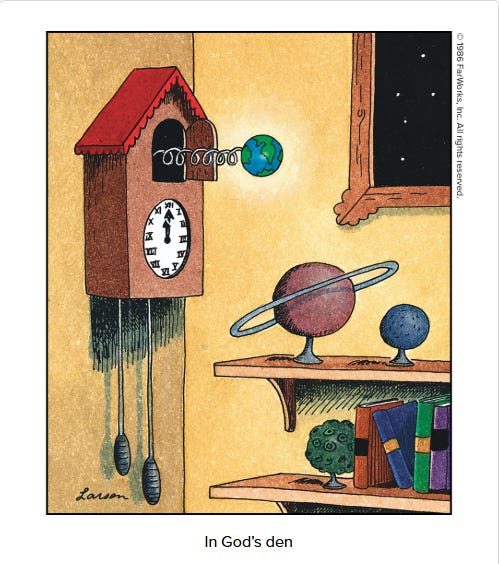
A cuckoo clock runs on exactly one idea. Something small and mechanical pops out, makes precisely the noise it made last time, retracts. On schedule. Regardless of who is listening, regardless of what else is going on in the room, and regardless of whether the room happens to be on fire.
In this one the bird is the Earth. Which is the best piece of market commentary anybody has ever drawn, and it ran in a newspaper in 1986, next to the crossword. Why? Because that is precisely what our instruments do. Out on the spring, same noise as last time, back in. And the noise they are making this morning is ‘everything is fine’.
So let us have a look at the room.
The President of the United States posted an AI-GENERATED VIDEO of Kharg Island, the terminal that ships about ninety percent of Iranian crude, being destroyed, captioned ‘blown to smithereens’, at 10:18 at night. His own Defense Department had to come out the next morning and clarify that no such attack occurred. Ten hours later he posted that Iran is ‘officially a Failed Nation. IT IS DEAD!’ with an inflation figure roughly four times the one actual reporting carries.
Two supertankers were hit leaving Hormuz with their transponders switched OFF, which means the ‘fragile recovery’ in transit traffic everyone has been citing was smuggling. With very large ships. In the world’s most watched waterway.
A top American commander says the lanes are open. The President says thirty ships a night are getting out. The Revolutionary Guard says a tanker hit a mine. The security consultants say projectiles. Four parties, four incompatible accounts of the same square of water, same morning.
Immigration enforcement is buying two million dollars of ROBOT DOGS.
The White House announced it secured sixty-five billion barrels of Venezuelan reserves. From a government it installed. At a production rate that does not exist.
A twenty-four year old with no finance background blew up a forty-five billion dollar fund. His stated long-term ambition, told to friends at dinner parties,
Actual galaxies. His friends had to leave the room to check whether he meant a type of private jet.**was to buy galaxies.**And the largest private artificial intelligence company in the world is preparing to tell IPO investors its addressable market is above thirty trillion dollars. Thirty trillion. Global output is about a hundred and ten.
Donald Trump renamed Lake Ontario, just because he felt like it. And Google and Apple acquiesced and changed it on their maps.
So here is the thing about that clock. Not commenting on any of this. A clock does not know the weather. It does not know the room is on fire or that the man who wound it has been posting. It tells you what time it is, and it will keep telling you accurately right up to and through the moment everything else falls apart, which is exactly what makes it so reassuring and so useless. Which is my whole problem this morning.
Because look at the instruments. VIX in the low fifteens. High yield spreads a whisker off the tightest in a year. The official financial stress index reading BELOW ZERO on all three engines, credit, funding, equity valuation, every one of them saying conditions are easier than normal. The S&P a hair under its record. And on Monday, with two ships burning in the Gulf and the thirty-year at levels last seen before the crisis, high yield credit closed GREEN.
Green.
The lazy read is complacency, and I have been guilty of it. Complacency is a claim about people. It says they are wrong. What I am going to argue is duller and worse: the gauges are wrong. Not because anybody lied. Because of how they are built.
Every instrument in that paragraph is a composite. High yield OAS is market-weighted, so the biggest safest issuers drown the small ones. The VIX prices an index, and an index is a portfolio of correlations. The S&P is cap-weighted, five hundred names with seven that matter, which is not a survey. A poll of seven people. And an average is engineered to make the tail disappear. Not a flaw in the construction. The purpose of it.
Fine. Excellent, even. Right up until the tail is where the news is.
The chair went to Wyoming on Friday and said he wants clean signals, unfiltered, no hall of mirrors. Good instinct! Genuinely. Then in the same speech he looked at a market-weighted composite spread of 260 basis points and concluded credit shows few signs of policy restraint. He read the average. The average is the filter.
Nine sessions to the meeting. Somebody is going to have to open that little door and look.
**STAY SHORT THE LONG END, FULL SIZE.**The thirty-year has closed at or above five percent for 39 straight sessions, the longest run since 2006. Nothing in the buyback stops that.**THE WHOLE BOOK IS ONE BET WITH AN ENERGY KICKER, AND I AM NOT DRESSING IT UP.**Three tickets monetize the cost of long money. Add a short credit leg and a long energy leg elsewhere and the correlation goes up, not down.**FADE THE FLAT-CURVE PANIC.**Two of the last five hiking cycles began FLATTER than today’s 39 basis points, and both flattened less afterward, not more.**BUY THE FRONT OF THE VOL CURVE, NOT THE BACK.**One-year against one-month sits at the 96th percentile. The cheap month is the one holding payrolls, CPI and the meeting.
The thirty-year has held at or above 5.00% for
39 consecutive sessions, 7 July through 28 August, the longest stretch since 2006.**2s10s at 39bp.**Two of the five prior hiking cycles started flatter, at 28bp in 1999 and 24bp in 2022, and both saw shallower subsequent flattening than the steep starts did.Five separate credit markets are repricing their tails at once while every covering index sits calm. Roughly
$1 trillionof investment grade paper trades wide of its own rating.HYG closed green Monday, up 0.09%, on a session with two tankers hit in Hormuz and the long end at nineteen-year highs.Multifamily serious delinquency has pushed
above its post-crisis peak, the highest since at least 2004.
Start with the number I did the work on, because it is the one carrying the most weight and I want you to see the provenance rather than take my word.
The thirty-year has closed at or above five percent for
39 consecutive sessions, 7 July through 28 August. I counted it off the constant maturity series, every observation back to 1977. Since 2006 only two runs beat it, ninety-two sessions in 2006 and forty-four in 2007, and nothing since has managed eleven. Longest in nineteen years.
Read those three together and the shape is obvious. The move is at the BACK. Two-year at 4.34, exactly where it landed after its twelve basis point jump on the speech, and flat since. Everything in the last two sessions happened past ten years.
Which brings me to the chart everybody is passing round this morning, and to the only genuinely non-consensus thing in this note.
The claim: this curve cannot afford a hiking cycle, a start this flat inverts almost immediately, and the evidence offered is 1994 at 155 basis points and 2004 at 190 against roughly 47 now.
So I computed the slope on the day of the first hike in every cycle since 1994. Here is what is actually there:
One caveat on the table before it does any work: the five historical rows are slopes on the day of a first hike, and my row is a slope eleven sessions before a hike that may not come. Close enough to compare, not the same object, and I would rather say so than let the row alignment imply a precision it does not have.
Two of the five began flatter than we are now. Not marginally. 1999 started at twenty-eight and 2022 started at twenty-four, both inside today’s thirty-nine. The chart draws both of those lines and then the caption walks past them to reach for the two steepest starts in the set.
And look at the right-hand column, because it inverts the whole argument. The cycles that began STEEP are the ones that flattened hardest. 2004 lost a hundred and fifty-eight basis points. 1994 lost a hundred and nineteen. The two flat starts lost sixty and sixty-six. 2015, at a middling hundred and twenty-eight, did not flatten at all.
A flat curve at the first hike is not the accelerant. The receipt. The front end has ALREADY done the work, which mechanically leaves less room to do more. Cherry-pick two observations from five and you can prove whatever you fancy... and the two left out are usually the two that matter.
The honest caveat, and it cuts at me. Five cycles is an anecdote with a line through it. My finding is narrow and I want to keep it narrow: the claim that this start is uniquely dangerous BECAUSE it is flat is not supported by the record it cites. Believe the curve is a problem for other reasons. Several are good. Just not that one.
**SO WHAT IS ACTUALLY WRONG, THEN.**Five credit markets. All at once. Here they are.CCC spreads near the top of their own 52-week range while BB sits at the very bottom of its. Same asset class, opposite ends, same week, and the composite splits the difference and reports calm. Emerging sovereign protection wider four sessions running, longest since April. Distressed loan volume among US consumer cyclical borrowers at $14.7 billion in August. Multifamily serious delinquency through its post-crisis peak. And roughly a trillion dollars of investment grade paper, $580bn here and $400bn in Europe, trading wide of its own rating, a dislocation that has more than DOUBLED since January.
Five. Not one market with a story. Five different borrower sets, in different currencies, under different regulators, with no shared index.
And now the objection that matters, which I would raise first if somebody handed me this. They are not five independent observations. The holder base overlaps, heavily. Insurance general accounts, private credit vehicles and multi-strategy books own CCC paper, wide-of-rating investment grade, emerging sovereign, consumer loans and agency multifamily AT THE SAME TIME. One pool of yield-seeking capital bought all five over a decade. So five markets moving together may simply be one position moving, with one cause, showing up in five places. Which would make my five confirmations a single observation wearing five hats.
I think the shared holder base makes it worse rather than weaker, because a common owner is a common seller. But I am not going to pretend the count is five when the honest count might be one.
Each one could also be read on its own terms and dismissed. Multifamily is an agency book with a rate problem. Emerging market protection widens every time the dollar firms. Consumer cyclical distress is a small base. The investment grade dislocation may simply be ratings lagging a violent rate move, which is what ratings always do. Taken one at a time, every single one of them has an innocent explanation and I would accept it. What I cannot accept is five innocent explanations arriving in the same week in five markets that do not share a holder base.
Every composite covering those five is quiet. The official stress gauge above all of them reads EASIER THAN NORMAL on all three engines at once.
The steelman, and it is a real one: an index dominated by upgraded survivors and by issuance from rate-insensitive borrowers genuinely IS lower-risk than it was two years ago. Upgrades have run well ahead of downgrades. The composite is not lying about the population it measures. Telling the truth about a population quietly reshaped underneath it. Subtler, and worse, because there is nobody to blame and therefore nobody to correct it.
The transmission channel, because a divergence with no mechanism is just a coincidence with a chart: every one of those five tails is a FLOATING or SHORT-DATED borrower, and the composite is stuffed with fixed-coupon paper that has years of maturity to hide behind. Higher base rates hit the floating book as interest expense this quarter and the fixed book as a mark you never have to take. Same rate move, two entirely different experiences of it, and only one of them shows up in a spread.
Which is the part of the artificial intelligence trade I keep circling. Not demand. FINANCING. Thirty-five billion of compute committed yesterday, three and a half billion into a chip designer, another billion and a half into an energy developer, all in one session. Issuance tied to this buildout accounts for essentially all the growth in global capital markets supply while everything else shrinks. And the productivity payoff runs well behind the last general purpose technology at the same point.
Borrowing against a return the aggregates cannot yet see. Where have we heard that?
Though the gap may simply be measurement lag. Total factor productivity is a residual, it revises hard, and fifteen quarters against a full Netscape run is not a fair fight. The honest objection, and the one I would raise first.
AND A SECOND CASE AGAINST, ON THE ENERGY LEG, WHICH ARRIVED OVERNIGHT.
The White House says it has secured sixty-five billion barrels of Venezuelan reserves (NPR). Take the number at face value for a second, which nobody should, and it is roughly seven times what the strait moves in a year. Reserves in the ground are not barrels on a ship, the production is not there, the infrastructure is not there, and the counterparty is a government Washington installed. But it is a real supply answer to a supply shock, announced within days of one, and if the market chooses to trade it as such then my inflation transmission runs into a headline it cannot outrun. Politically it is the same move as the buyback: reach for a lever, announce it loudly, and hope the level does the rest.
THE FRAME I KEEP COMING BACK TO, and it is not mine. Six months into this war none of the stated objectives has been met, and the comparison being made in serious places is Suez. Not the canal. The lesson of it: an imperial power announces a thing, the world declines to go along, and the announcement itself becomes the evidence of decline. Washington spent last week telling every government on earth to sever commercial ties with Tehran. This week the Iranian president is in Kyrgyzstan being courted by Modi, by Pakistan’s Sharif, by Azerbaijan, with Putin and Xi to follow. Nobody said no. They simply carried on. And neither side in the Gulf can escalate or climb down, which is a stalemate that produces headlines without producing resolution, and a market cannot price a stalemate. It can only price the tail of one.
THE CASE AGAINST ME.
The tail always looks like this. Always a bottom decile in trouble, which is what a bottom decile is for, and dispersion inside credit is a feature of a working market rather than a warning. Every number I just cited has a boring explanation. Multifamily at forty-seven basis points against a 2010 print of forty-four, on a far smaller book. A billion of consumer cyclical distress in a month is noise at that base. Paper trading wide of its rating is what ratings lagging a violent rate move looks like, and implies nothing about default.
If that holds, the composites are fine, the tails are ordinary, and I have pattern-matched five unrelated markets into a thesis. Entirely possible. I have done it before.
The kill is high yield through 300 with the thirty-year BELOW 5.10. Credit finding the tail without the long end forcing it means the mechanism was wrong, and the mechanism is the whole argument.
**10:00, ISM MANUFACTURING.**Survey 55.2 against 55.6. The headline is the least interesting part. Prices paid, surveyed at 70.75 after 71.1, is the number that either arms or disarms the September hike, and a print holding above seventy with the energy complex where it is makes the sixteenth a very short conversation.**10:00, JOLTS.**Survey 7,313k after 7,359k. Openings have become a labor-supply story rather than a demand story and a s…