Dear Nike,
You have spent the better part of five years accomplishing something I once would have thought nearly impossible: turning one of the greatest brands in the history of capitalism into something that makes consumers and stockholders alike want to barf up their lunch. The brand simply no longer means what it once it and the stock is down -42.7% this year *alone. *
Nike has lost roughly three quarters of its value from its 2021 peak, vaporizing more than $200 billion of market capitalization along the way. Shares recently traded below $37, their lowest level in roughly 12 years, and Nike was just booted from the S&P 100 after an 18 year run.
This wasn’t caused by one catastrophic decision, it was death by a thousand corporate PowerPoints. The company leaned too hard into direct to consumer, damaged wholesale relationships, let Hoka, On, New Balance and Asics gain ground, relied endlessly on old franchises, lost momentum in China and somehow made one of the coolest brands on Earth feel corporate and predictable.
Fiscal 2026 revenue fell 2% currency neutral, Nike Direct revenue dropped 6% and Greater China remained ugly. There are signs CEO Elliott Hill understands some of this. Wholesale relationships are being repaired, inventory is getting cleaned up, Nike is trying to restore full price selling and ACG is being relaunched as a serious outdoor business. But Nike doesn’t need a slightly better version of Nike. Nike needs a corporate defibrillator.
If you handed me the keys tomorrow, here’s the five steps I’d be taking to try save the brand, the company, its customers and its investors.
First, stop trying to manage Wall Street’s feelings right off the bat. Silence the investor crowd for the time being so we can get down to work and reset expectations. Kitchen sink the guidance, estimates and turnaround timeline. Write off whatever needs to be written off. Clear inventory. Close mediocre stores. Kill mediocre products. End projects that exist because nobody in Beaverton had the courage to kill them up until this point.
Then tell Wall Street something it almost never hears from management: we haven’t earned a premium multiple.
Nike still trades around 17x earnings despite the absolute demolition of the stock. If resetting expectations means shares have to fall another 20% or 30%, so be it. The objective shouldn’t be engineering a good quarter. It should be engineering a great decade.
Put essentially everything about the existing strategy up for review. Every category, sponsorship, distribution relationship, executive position and product line gets reevaluated from scratch. Give investors deliberately conservative targets that Nike has a chance of beating instead of optimistic targets management has to explain away every three months. Make sure sentiment is so bad the stock has *no where to go but up *over the next 5 years. Take the medicine once. Wall Street will survive.
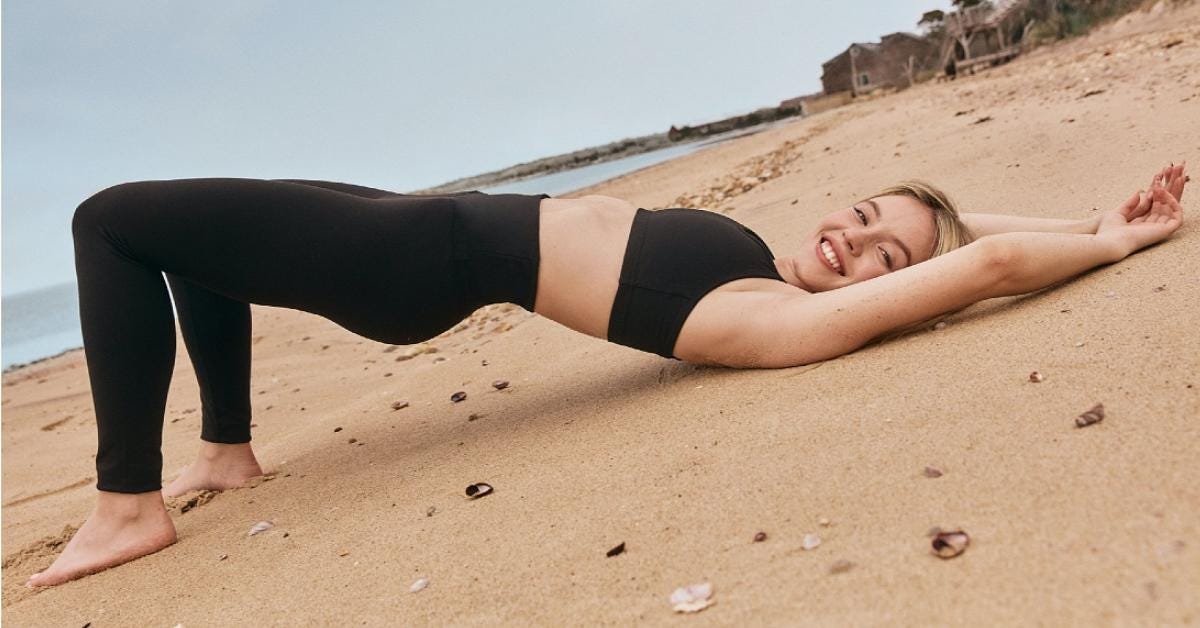
Yes, I’m serious. You can reinvent two brands at once, expand into yoga further and put clothes tailored to accentuate….the female form…on the woman who is best suited for it and who creates massive controversy and clicks in one ad.
I’ve written about Lululemon before because I’ve always thought it was an obvious adjacent growth opportunity for Nike. Now the market has practically gift wrapped it.
Lululemon’s market capitalization has collapsed to just $10.8 billion. Its shares trade around 8x trailing earnings and roughly 12x forward earnings and it generates billions in cash a year. Nike, despite its own implosion, still has an equity value around $54 billion and trades around 17x forward earnings.
That creates a fascinating potential arbitrage. Nike could use a combination of its still more expensive equity and cash to acquire an internationally recognized athletic brand at a dramatically lower earnings multiple. Obviously you’d have to model the premium, financing, dilution and integration before declaring the transaction accretive, but strategically I think it deserves serious consideration.
More importantly, Lululemon gives Nike something it desperately needs: a much stronger position in premium women’s athletic apparel and enormous runway internationally.
Then I’d immediately hire Sydney Sweeney. Yes. T&A. Welcome back to advertising. Sex sells. It has sold for approximately the entire history of civilization, and I have yet to see convincing evidence otherwise.
Maybe you don’t find Sweeney attractive, personally. That’s fine. But Sweeney offers something considerably more valuable than simply being attractive. Everything she touches becomes a cultural argument. Her latest sports related campaign generated exactly that kind of reaction. Critics attacked it, supporters defended it and everybody talked about it. That’s the point.
I’m not suggesting Nike deliberately offend half its customers. I’m suggesting Nike remember that advertising is supposed to make people feel something. Anything. For decades, Nike understood this better than almost anybody. Nike ads were events. Sometimes inspirational, sometimes funny, sometimes controversial, sometimes uncomfortable. But people talked about them.
Today, too much corporate advertising looks like it was constructed by 19 people sitting around a conference table trying to make sure the campaign couldn’t possibly upset the twentieth. Nike has lost its edge. Sweeney is edge.
Pair her with Lululemon and make the first campaign impossible to ignore. Make it sexy, athletic and funny. Let people argue about it on television for three days. It would be a neutron bomb of a headline. Nike doesn’t need everybody to agree with its advertisements. Nike needs people to notice Nike again.
Nike should stop waiting for sports to become gigantic before deciding they’re worth its time. Start with fighting. Build Nike Fight Camp.
Go after MMA, Brazilian jiu jitsu, judo, wrestling, boxing and grappling with the aggression Nike once brought to basketball. Sponsor elite fighters and grapplers. Sponsor gyms and academies. Build fight shorts, rash guards, training apparel, recovery gear and footwear. Get involved with UFC and the broader combat sports ecosystem.
Make Nike the aspirational brand for the 14 year old walking into a jiu jitsu academy for the first time.
And don’t stop there. Go find the sports whose cultural relevance is rising faster than their sponsorship budgets. Padel, pickleball, women’s soccer, climbing, skateboarding, trail running, volleyball, badminton and table tennis all deserve attention.
And table tennis in China.
If Nike wants to rebuild China, maybe it should stop treating China exclusively as a place to sell American cultural exports and start attaching itself to athletes Chinese consumers already worship. Wang Chuqin is currently the world’s No. 1 men’s table tennis player. Wang Manyu recently became women’s world No. 1. Sun Yingsha spent 217 consecutive weeks at No. 1 before Wang overtook her and earlier this year became the first woman to win three consecutive Women’s World Cups.
Sign people like them. Build signature products. Build campaigns specifically for China. And while you’re at it, turn ACG into an absolute monster. Nike is already moving in this direction by rebuilding ACG around trail running, hiking and exploration. Now spend.
Outdoor is an obvious place for Nike to compete harder. Trail running has affluent customers, expensive footwear, passionate communities and aspirational athletes. Stop conceding culturally hot categories to specialists.
Nike should be where sports are going, not where a McKinsey presentation says sports were five years ago.
Nike’s greatest competitive advantage was never foam. It was mythology. Michael Jordan didn’t merely sell sneakers. Nike helped construct an entire universe around an athlete. The company needs to start thinking that way again.
Create an internal group with essentially one job: find the next Jordan.
Not literally another Michael Jordan. Find the athletes who could define their sports for the next 15 years and sign them before everybody knows their names.
Being from Philadelphia, one name immediately jumps out at me: Cavan Sullivan. Sullivan became the youngest player ever to appear in an MLS match when he debuted at 14 years and 293 days. Now, just shy of his 17th birthday, he’s exploding, with six goals and five assists across his last eight matches. He’s already tied to Manchester City for an eventual move to Europe when he turns 18.
He’s an off the radar up and comer with room to grow…in a sport with a massive growth trajectory for the United States still.
Is he the next Messi? Probably not, because statistically almost nobody can possibly be the next Messi. But that’s exactly the kind of bet Nike should make.
Sign him now. Build the relationship now. Let everybody else discover him when he’s scoring Champions League goals later.
Then do the same thing everywhere. Who is the 15 year old basketball player nobody outside recruiting circles knows yet? Who is the next generational women’s basketball player? Who is the 16 year old boxer? Who is the teenage Brazilian footballer? Who is the next Chinese superstar?
Nike should have the best athletic scouting department outside professional sports.
The old Nike didn’t simply sponsor famous people. It helped make people famous.
Finally, I’d do something bordering on corporate heresy. I’d announce that Nike is dramatically reducing Jordan releases. Hell, maybe I’d announce a five year moratorium on selected retro Jordan releases.
Imagine the headline: Nike Stops Making Air Jordans.
CNBC would spend the entire morning talking about it. Resale markets would start repricing inventory. More importantly, consumers would suddenly remember that Jordans are supposed to be special. Scarcity is marketing.
Nike spent years training consumers that if they miss one release, another one will arrive shortly afterward. Reverse that psychology. Stop producing endless quantities of mediocre shoes simply because factories can produce them. Stop putting everything everywhere. Stop training customers to wait for discounts.
Make the Swoosh mean something again….and take the same approach in China. Nike’s instinct shouldn’t be to respond to weakness by screaming louder. Pull back. Reduce distribution, promotions and inventory. Close weak locations. Stop begging consumers to love Nike.
Let the brand disappear slightly. Let scarcity rebuild curiosity.
Then, a year or two later, start turning the volume back up. And when you do, don’t arrive with some generic global campaign. No desperate sale banner. No 40 product launch. One athlete. One shoe. One memorable advertisement. And not enough inventory. Make people hunt for Nike again.
The irony here is that Nike’s problem really isn’t that complicated. Nike became enormous by being cool. Then it became enormous enough that being enormous became the strategy, and then being cool just goes away naturally…
More channels, more SKUs, more releases, more optimization, more corporate strategy and more attempts to squeeze another dollar out of franchises whose cultural capital was built decades earlier. Eventually you wake up and discover Hoka owns part of running, On owns another piece, Lululemon owns premium women’s apparel, specialists own the trails and teenagers aren’t sitting around wondering when Nike’s next quarterly earnings call is.
You cannot spreadsheet or focus group your way out of that.
Reset Wall Street’s expectations. Buy growth while it’s cheap. Put some sex, humor and controversy back into advertising. Invade emerging sports before everybody else. Find generational athletes when they’re teenagers. Turn ACG into a legitimate outdoor empire. Rebuild China around Chinese sports culture. Manufacture scarcity instead of drowning the world in another 17 Dunk colorways nobody asked for.
Most importantly, stop protecting the stock price. The stock has already been annihilated. Nike has lost more than $200 billion of market value. What’s left to protect?
Let it fall another 30% if that’s what a genuine reset requires. The objective shouldn’t be getting Nike back to $50 this year. It should be building a company that deserves to eventually be worth $250 in 5 to 10 years.
QTR’s Disclaimer**:** Please read my full legal disclaimer on my About page here.
Contributor posts, guest posts and curated posts have been hand selected by me, but have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author or reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.
I cannot guarantee the accuracy of any or all facts and figures included in this article though I made an effort to get them right. I have been wrong before and will be wrong again, and encourage you to always double check, do your own research and speak to a licensed financial professional, which I am not.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things I’m bearish on. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.
Starting in 2026, I have been attempting to no longer actively trade as much as I once did ( read my story here). My goal is for my investing/saving to be done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. It is possible I could own, have exposure to, or not own anything, at any point. In an attempt to lead a healthier lifestyle, I’ve also excluded myself from fantasy sports, sports betting, online and in-person casinos and prediction markets.
Any of my positions can change immediately as soon as I publish, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier. Hence, why I am a writer.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. Many times I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour.
Also, again I just straight up get shit wrong a lot. I mention it multiple times because it’s that important you understand.