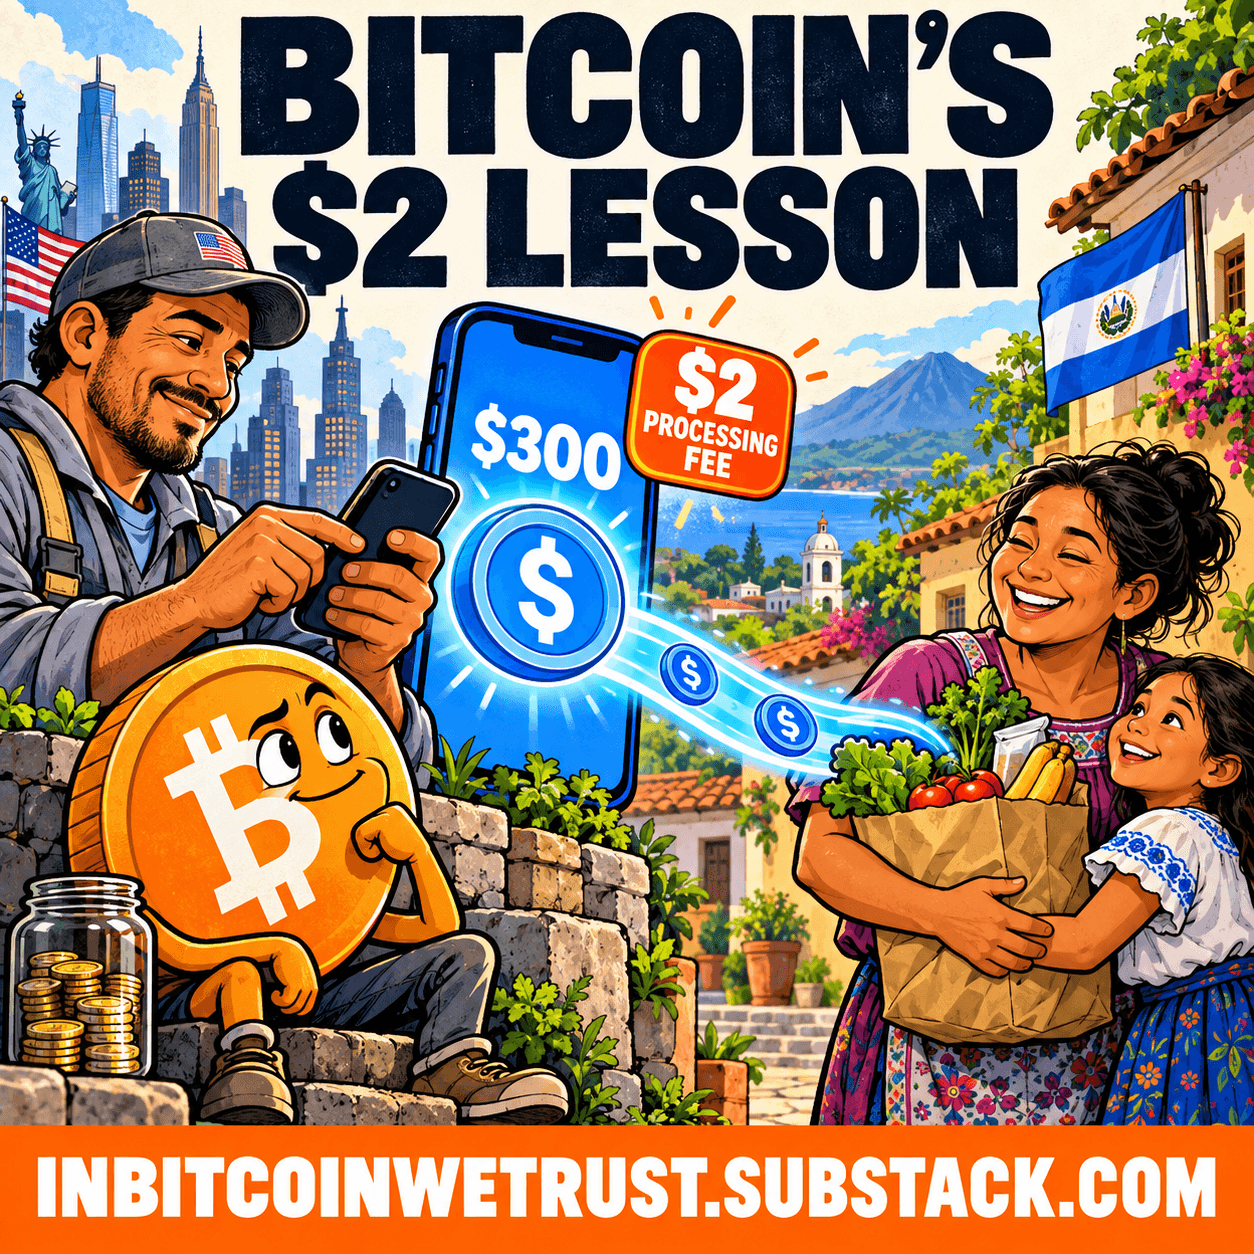
Imagine finishing a working week in the United States and opening your phone to send $300 to your mother in El Salvador.
You know what that money is for. Groceries. Electricity. The prescription she needs to collect. A school expense that cannot wait until your next paycheck.
You want to know how much sending it will cost, when she can use it, and whether the amount arriving will cover the bills you discussed.
You are probably not looking for a debate about the future of money.
Yet that ordinary transaction sits at the center of one of the most uncomfortable questions in Bitcoin.
Five years after El Salvador made Bitcoin part of its national monetary experiment, a new app called Sivar is offering remittances through stablecoins on Base. Coinbase supplies the payments infrastructure. The advertised cross-border processing fee is $2. Bitcoin is outside this payment flow.
The obvious response is to turn the announcement into a scoreboard.
Stablecoins win. Bitcoin loses. Bukele changes sides. Someone posts a victory thread. Someone else explains why the victory thread is fake news.
I think the more important story starts with that mother waiting for her money.
Her household budget does not exist to validate anyone’s monetary thesis.
A payment system earns her trust by working. A monetary asset earns its place by offering properties she values. Those can overlap, but they are not automatically the same job.
Sivar makes that distinction unusually visible. Its fine print also makes the story more interesting than the headline suggests.
Because the $2 fee is only one part of the receipt. Self-custody is only one part of control. And a private company’s product announcement is only one part of a country’s monetary policy.
If we get those distinctions right, El Salvador offers a much better Bitcoin lesson than another round of tribal celebration.
Claude’s maker is reserving the infrastructure for an AI-powered economy before anyone knows its profit margins. The danger is that AI succeeds—and the financial bet still fails.
According to ** Coinbase’s September 29 announcement**, eligible U.S. users can fund Sivar transfers through Coinbase Onramp. Users receive non-custodial wallets, transfers settle in stablecoins on Base, and recipients can withdraw cash through more than 1,000 locations in El Salvador. Coinbase reported over 25,000 registrations before launch.
Its description includes a revealing sentence:
“Crypto is abstracted throughout the experience.”
That is a product decision with a monetary argument hiding inside it.
The customer should not have to select a blockchain, understand gas, or explain token contracts to a relative before sending money home. The app wants the experience to begin with a dollar amount and end with money someone can use.
I like that ambition.
We do not expect people to understand internet routing before making a video call. We should not expect a family to complete a crypto seminar before receiving the money that pays its electricity bill.
But a clean interface answers only the first question: can the customer operate the product?
The next questions are harder. What does it cost? What happens when something goes wrong? Who can restrict access? Can the user leave?
Making complexity disappear from the screen does not make it disappear from the system.
That is where the real analysis begins.
Everyone is obsessing over AI’s profitability. But the creators aren’t trying to build a business—they’re building a new reality where money itself becomes obsolete.
There is an important correction to the simplest version of this story.
Sivar’s ** published fee schedule** separates cross-border processing from wallet funding and cash withdrawal.
The same schedule lists these separate components:
For a $300 funding operation, 2.5% is $7.50. For a $300 cash withdrawal, the listed withdrawal charge is $1.75. The transfer fee is separate. Actual charges depend on the selected route and transaction amounts.
Those distinctions matter to a family choosing a service. They also matter to anyone comparing Sivar with an existing remittance provider.
A cheap middle step can coexist with expensive edges. A fee-free funding route can produce a very different result from a card-related route. A recipient who keeps a digital balance has a different cost experience from someone who needs cash immediately.
We should compare the money leaving the sender’s pocket with the usable money reaching the recipient.
That is the comparison that pays a bill.
This does not make Sivar’s pricing proposition meaningless. It makes precision essential. A flat processing fee can be attractive, especially for larger permitted transfers, without representing every possible cost of the journey.
The most useful remittance number is the amount a family can actually spend.
Crypto companies deserve credit for reducing costs when they do. They also deserve the same scrutiny we apply to the companies they want to replace.
Now put the fee table aside and return to the $300.
The sender earns dollars. The recipient’s immediate expenses are expressed in dollars. The purpose of the transfer is to carry a known amount from one household to another.
That gives a dollar stablecoin an obvious advantage at the level of denomination.
The sender does not have to decide how much Bitcoin the family should own. The recipient does not have to choose a selling moment. The number on the screen can remain aligned with the number on the bill, provided the stablecoin maintains its peg and the relevant services work.
That last qualification matters. A stablecoin’s price target is a design objective, backed by a particular structure. It is not a magical guarantee.
Still, the objective fits the task.
If money arrives today and gets spent tomorrow, short-term predictability can matter more than the monetary policy of the asset used for settlement.
People who have room to take financial risk sometimes underestimate how valuable that predictability is.
A family with very little spare cash cannot casually absorb a bad exchange rate or a delayed withdrawal. A few missing dollars can change which expense gets postponed.
There is nothing intellectually shallow about preferring a payment that matches the bill.
Nor does that preference settle what the same person should want from savings held for years. The time horizon, purpose, and acceptable risks have changed.
The mistake is treating one transaction as a referendum on every possible form of money.
There is also a mistake Bitcoin critics should avoid.
Using Bitcoin as a transfer rail does not necessarily require a family to hold an unhedged BTC balance for days.
Consider a service designed to accept dollars, convert immediately before a transfer, move value through Bitcoin or Lightning, and convert back at the receiving end. A provider could quote the recipient’s dollar amount in advance and manage the exposure itself.
That architecture shifts conversion, liquidity, and market risk toward the service provider. It does not make those costs vanish, but it can greatly reduce the customer’s exposure.
So the argument that Bitcoin remittances inherently force every mother to gamble with the grocery budget is too crude.
Bitcoin-based services can also offer simple interfaces. Complexity hiding is a product capability, not a stablecoin monopoly.
The serious comparison is between complete systems: funding, exchange spreads, payment reliability, available liquidity, cash access, support, and restrictions.
Which architecture delivers the better result for this customer, on this route, at this amount?