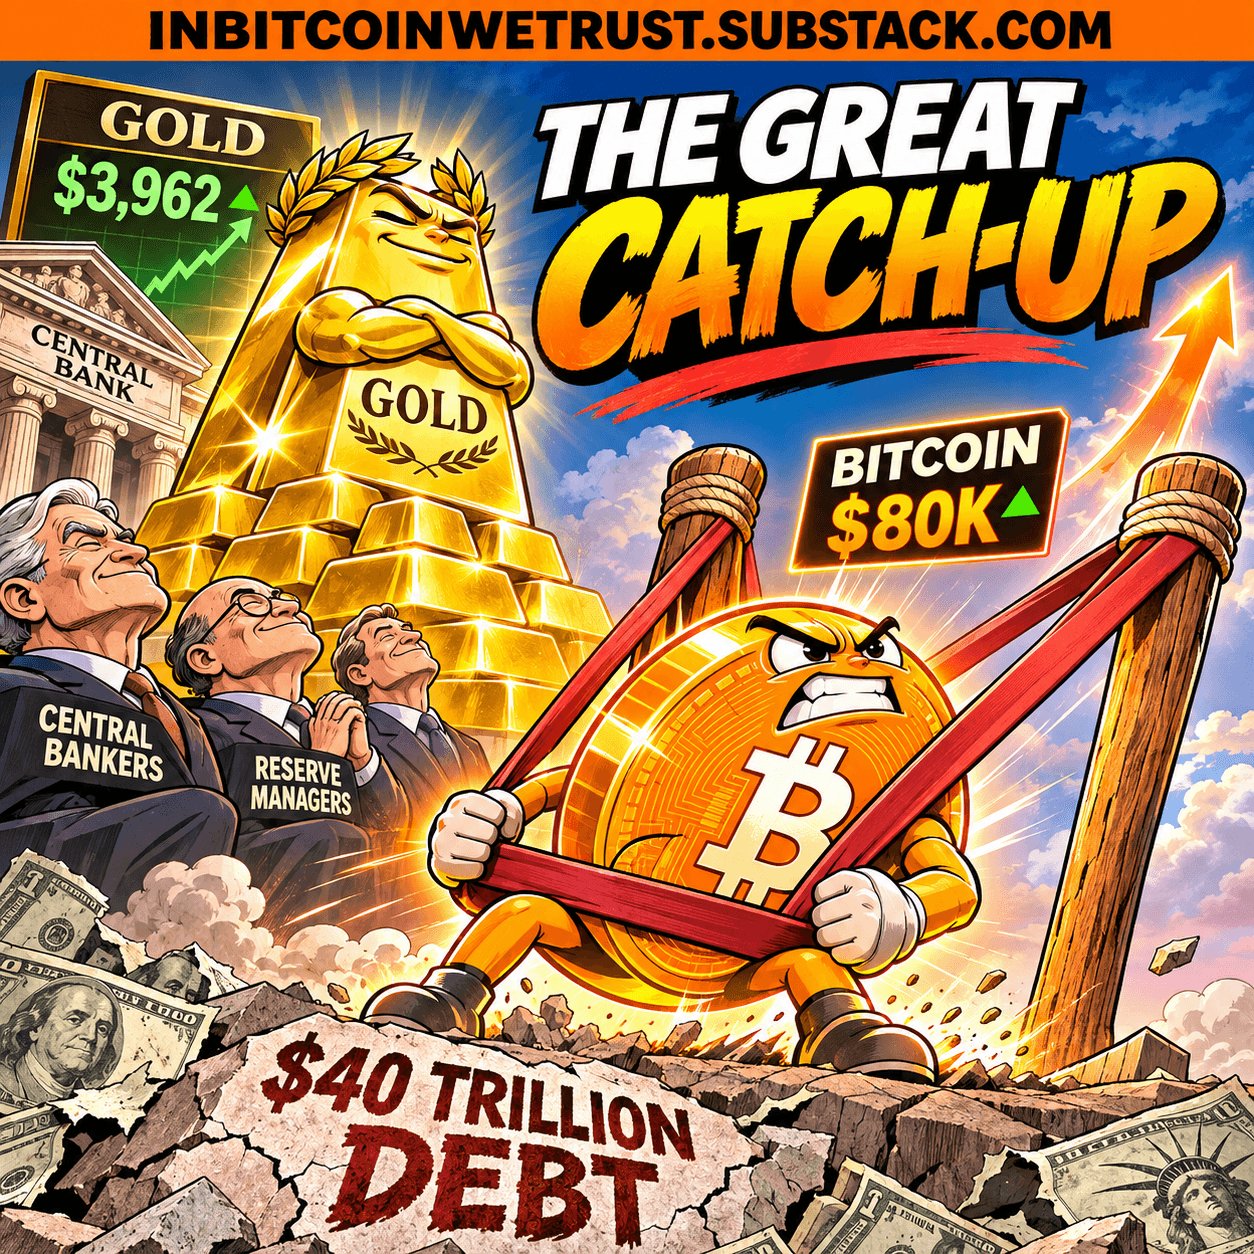
Gold has crushed Bitcoin over the past five years, surging to multi-decade highs before settling at 3,962.28 dollars an ounce today, while the world’s premier digital coin consolidates near 80,000 dollars. Wall Street skeptics call it the death of the “digital gold” thesis. History and monetary physics say it is the coiling of the greatest asymmetric spring of our lifetime.
In the autumn of 2026, a strange and unsettling optical illusion hangs over global financial markets. If you walk into a private wealth management office in Zurich, London, or Paris today and ask the resident strategist about the war against monetary debasement, they will point to a single, gleaming chart with an air of quiet vindication.
That chart belongs to physical gold.
Over the five-year window stretching from early November 2021 to early November 2026, gold has delivered a cumulative return of more than 120 percent, climbing from roughly 1,790 dollars an ounce to 3,962.28 dollars today—after having shattered the 4,370-dollar barrier in late 2025 and briefly touched 4,620 dollars in August 2026. Over that exact same five-year period, Bitcoin—the unstoppable thermodynamic monetary network that was supposed to render shiny yellow metal obsolete—returned roughly 37 percent, leaving gold ahead by more than 80 percentage points over half a decade.
Look closer at the recent calendar and the divergence appears even more jarring to the casual eye.
Throughout 2025, as geopolitical fractures widened and fiscal deficits spiraled out of control, gold staged its most explosive annual rally in more than four decades, soaring 64.46 percent. Silver joined the stampede, surging 85 percent toward 57 dollars an ounce. Meanwhile, Bitcoin—after touching a brief all-time high above 126,000 dollars on October 6, 2025—spent the final months of 2025 and the first half of 2026 locked in a brutal, grinding correction. It closed 2025 down 6.33 percent, plunged beneath its 200-week moving average to test 58,000 dollars during the liquidity panic of June 2026, and even after a vigorous 42.9 percent rebound in the third quarter, it finds itself fighting trench warfare around the 77,000-to-81,000-dollar zone as November unfolds.
For the mainstream financial press and traditional gold bugs, the verdict is already written. Asset managers go on television to declare that the June 2026 market stress proved Bitcoin is “clearly not digital gold,” but merely a high-octane technology stock in disguise. Retail tourists, exhausted by sideways chop and lured by the recency bias of bullion trading near 3,962 dollars an ounce, are questioning their conviction.
As an economic observer who has spent the past decade studying the intersection of monetary history, energy thermodynamics, and protocol architecture, I look at this performance gap—and gold’s recent pullback below the 4,000-dollar psychological mark to 3,962.28 dollars—and see the exact opposite conclusion.
The outperformance of physical gold in 2025 and 2026 is not the refutation of the Bitcoin thesis. It is the prerequisite for its next vertical phase. And gold’s current consolidation at 3,962.28 dollars is the early tremor of a capital rotation that has played out in every previous monetary cycle.
To understand why, we have to step back from the emotional noise of twenty-four-hour price tickers and examine how capital actually migrates during a sovereign debt crisis. We must ask why central banks always buy gold first, why Bitcoin was temporarily held back by an artificial wall of macro and technological friction in 2026, and why the laws of physics guarantee that when the dam of global liquidity finally breaks, the catch-up between the analog past and the digital future will be historic.
Reddit is losing over a million weekly search referrals as AI Overviews break the economic bargain that built the open web.
In their monumental work , Will and Ariel Durant observed that human nature changes at a glacial pace, and that when civilizations confront existential fiscal crises, institutions do not immediately leap toward radical innovation. They reach instinctively for ancestral memory.
We are living through the terminal arithmetic of the post-1971 fiat currency experiment. On August 25, 2026, the gross federal debt of the United States officially crossed the 40-trillion-dollar threshold. Across the Atlantic, European sovereigns are trapped in a fiscal vise where structural deficits collide with stagnant demographics and rising defense expenditures. The mathematics are no longer debatable: Western governments cannot tax their way out of a 40-trillion-dollar hole without triggering an economic depression, and they cannot allow real interest rates to remain permanently elevated without watching debt service costs consume their entire national budgets.
This predicament has given birth to what institutional desks from London to New York now openly call the Debasement Trade—the systematic rotation out of decaying sovereign promises and into hard, scarce assets that cannot be conjured out of thin air by a central bank printing press.
Yet a crucial question arises: if the Debasement Trade has been in high gear since early 2025, why did it propel gold to an August 2026 peak of 4,620 dollars an ounce and hold it at 3,962.28 dollars today, while leaving Bitcoin trailing roughly thirty-five percent below its October 2025 peak?
The answer lies in who is executing the first wave of the Debasement Trade.
When a cycle of currency debasement begins in earnest, the first trillions of dollars to flee sovereign bond markets do not belong to nimble cypherpunks, family offices, or Silicon Valley entrepreneurs. They belong to the largest, slowest, most bureaucratic pools of capital on the planet: central banks, sovereign treasuries, and state reserve managers.
Look at the forensic footprint of the physical gold market over the past twenty-four months. According to data from the World Gold Council, central banks purchased a net 863 tonnes of physical bullion in 2025. When gold dipped 4,000 dollars an ounce below during the hawkish interest-rate shock of the second quarter of 2026—testing the exact 3,900-to-4,000-dollar structural support zone where it trades today at 3,962.28 dollars—sovereign reserve managers did not panic; they stepped into the market and bought a second-quarter record of 289 tonnes between April and June 2026, five times their first-quarter total. The National Bank of Poland alone added 51 tonnes to its vaults during that window, while the People’s Bank of China officially added another 33 tonnes. Even private monetary giants operating at the edge of the dollar system joined the physical hoarding: by January 2026, stablecoin issuer Tether had quietly accumulated 140 tons of physical gold valued at 24 billion dollars alongside its Bitcoin reserves.
Why did the central banks of Poland, China, Turkey, and India buy hundreds of tonnes of gold rather than sweeping the Bitcoin order books at 65,000 dollars?
Because central banks are creatures of twentieth-century institutional plumbing. Under the Bank for International Settlements (BIS) and Basel III frameworks, physical gold is classified as a Tier-1 zero-risk-weighted reserve asset. A central bank governor in Warsaw or Beijing does not need to rewrite constitutional statutes, overhaul decades of auditing protocols, or explain elliptic curve cryptography to a parliamentary committee in order to buy fifty tonnes of gold bars. The vaults already exist. The legal charters are already signed. Furthermore, in an era of intensifying de-dollarization and geopolitical fragmentation, Eastern and non-aligned powers view physical bullion sitting in domestic vaults as the immediate, familiar antidote to the weaponization of Western sovereign debt.
Gold moves first because gold is the institutional reflex of the old world.
Whenever the tectonic plates of the global monetary order begin to fracture, the dinosaurs smell the smoke first because they are standing closest to the volcano. Central banks know better than anyone else that the fiat debt structure is unsustainable because they are the ones operating the printing presses. Their relentless, price-insensitive accumulation of more than 1,150 tonnes of gold across 2025 and the first half of 2026 built the foundation beneath the precious metal.
To look at central banks front-running the debasement crisis with gold and conclude that Bitcoin has lost the war is like watching nineteen-thirties generals buy up every horse in Europe before a conflict and concluding that the internal combustion engine has no future. The central banks have not invalidated Bitcoin; they have validated the exact macroeconomic premise upon which Bitcoin was built.
If gold benefitted from a price-insensitive sovereign bid, why did Bitcoin spend so much of the past twelve months acting like a coiled spring held down by lead weights?
To understand the compression of Bitcoin’s price in 2026, we have to dissect three distinct headwinds that converged simultaneously: the monetary policy shock of the Warsh Federal Reserve, a wave of misunderstood technological fear surrounding quantum computing, and the structural mechanics of an institutional ownership hand-off.
First, consider the interest rate channel.
Throughout the first half of 2026, as inflation proved stubbornly resistant to polite central bank rhetoric, the Federal Reserve under Chair Kevin Warsh adopted a notably hawkish posture, pushing benchmark interest rates into the 3.75 to 4.00 percent range. When geopolitical hostilities escalated in the Middle East in late summer—sending WTI crude oil past 90 dollars a barrel and Brent crude above 92 dollars—global bond yields spiked higher as markets priced in higher-for-longer real rates.
In the short term, Bitcoin and gold respond with different velocities to a sudden spike in real yields and a surging US Dollar Index (where Bitcoin maintained a tight negative correlation of minus 0.86 in late August 2026). Because Bitcoin is the only truly free, 24/7 liquid market on earth—with no circuit breakers and no sovereign central bank standing by with a taxpayer checkbook to buy every dip—it acts as the global financial system’s most sensitive barometer of marginal liquidity. When real yields spike, and the dollar tightens, leveraged macro funds liquidate their most liquid winners first to raise cash. In June 2026, that liquidity vacuum pulled gold down 28 percent from its highs to test sub-4,000-dollar levels, hammered silver by more than 50 percent, and pulled Bitcoin down roughly 50 percent from its October 2025 peak to nearly 58,000 dollars. And today, as bond markets digest the Federal Reserve’s latest autumn positioning, even gold has cooled from its August highs to 3,962.28 dollars.
Second, as research analysts at Grayscale documented in their 2026 market commentary, Bitcoin faced two asset-specific narrative headwinds that allowed gold to pull ahead earlier in the year: legislative friction in Washington and a sudden surge in mainstream media coverage regarding quantum computing.
Throughout late 2025 and 2026, every time IonQ, IBM, or Google published a hardware roadmap milestone or an algorithmic paper on logical qubit optimization, traditional financial journalists ran breathless headlines claiming that fault-tolerant quantum computers were on the verge of cracking Bitcoin’s encryption overnight. For conservative institutional allocators who do not understand the difference between a hashing algorithm and an elliptic curve signature, that uncertainty was enough to make them pause their Bitcoin ETF allocations and park their debasement hedge in physical gold ETFs instead.
Yet when we examine the quantum narrative from first principles, the panic evaporates. Bitcoin relies on two completely different cryptographic primitives: SHA-256 (for Proof-of-Work mining and hashing public keys into addresses) and secp256k1 (for generating public-private key pairs and digital signatures).
Against SHA-256, Shor’s quantum algorithm does not work at all; a quantum attacker is limited to Grover’s algorithm, which offers only a quadratic speedup. Reversing a 256-bit hash even with Grover’s algorithm requires 2
128quantum operations—a thermodynamic impossibility that would require more energy and time than exists in the solar system.Against secp256k1, Shor’s algorithm can theoretically derive a private key from an
exposedpublic key once a quantum computer possesses thousands of stable, error-corrected logical qubits (composed of millions of physical qubits). Crucially, in modern Bitcoin usage, your public key is not revealed on the blockchain until the exact moment you broadcast a transaction to spend from an address. As long as an investor practices basic cypherpunk UTXO hygiene—never reusing an address after spending from it and avoiding archaic 2009-era Pay-to-Public-Key scripts—their cold storage remains shielded behind a cryptographic hash while the protocol’s developers prepare post-quantum signature soft forks.
In other words, the 2026 “quantum discount” priced into Bitcoin relative to gold is a textbook case of information asymmetry: generalist capital pricing in a science-fiction caricature while protocol engineers quietly build the fortress walls.
Third, and most importantly, the sideways grind between 70,000 and 85,000 dollars in 2026 represents a massive structural transfer of ownership. When Bitcoin crossed 100,000 dollars and hit 126,000 dollars in October 2025, early retail adopters, venture funds, and short-term speculators who had accumulated coins at 10,000 or 20,000 dollars began taking life-changing profits. As on-chain data from early September 2026 revealed, short-term and medium-term holder profit-taking frequently exceeded 500 million dollars per day around the 81,000-dollar battle line.
Who has been absorbing that relentless wall of supply? Corporate treasuries led by pioneers like Strategy, sovereign wealth funds quietly replacing fast-money hedge funds inside spot ETFs, and long-term institutional allocators. In August 2026 alone, US spot Bitcoin ETFs recorded their strongest month of the year with 3.52 billion dollars in net inflows—including 1.9 billion dollars in a single week that propelled Bitcoin from 62,679 dollars back above 80,000 dollars.
A market where impatient, low-conviction hands sell billions of dollars of supply to permanent, low-time-preference institutional vaults looks boring on a price chart. On a supply-and-demand chart, however, it is nitroglycerin waiting for a spark.