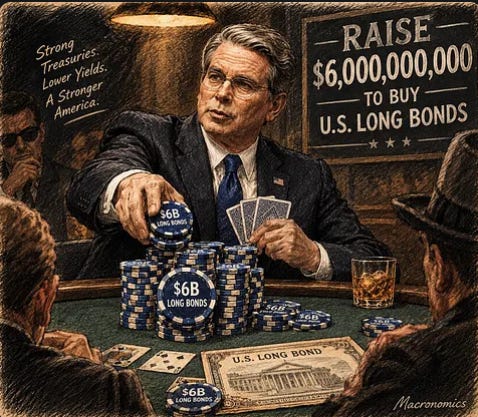
**“At the end of the day, we can endure much more than we think we can.” ~Frida Kahlo****Some random thoughts this morning as it becomes obvious that autumn is here:**Scotty B saying he’s ‘The House’, has asymmetric information, and daring the markets to bet against him is ironic, given that his boss bankrupted casinos-the ultimate ‘house’ six times. Just saying.
September 10th was a Monday, the first day of our brand-spanking-new trading floor at Lehman Brothers. I took the train in from Ridgewood to Hoboken, and then the ferry across. The sky was that special kind of blue, not a cloud to be seen. Some small planes buzzed through the vista doing early morning practice, I suppose. To this day, whenever I see that unique clear blue sky, I remember that day. And the next one.
Let’s do the math. This comes $1.35 trillion dollars. Kinda seems a. illegal, since Congress controls the disbursement of money, not the Executive branch, and b. guaranteed to cause rates to skyrocket. But why let reality get in the way, eh?
More and more reports indicate Iran is running out of money as the U.S. blockade effectively shuts down oil exports. Whilst that’s good news, there’s a dark side to it. In true ‘if you have a hammer, everything is a nail’ fashion, why would we think a militaristic autocracy would fold and come to the negotiating table? Instead, isn’t it more likely that it will escalate the kinetic engagements in an attempt to cause maximum pain for its adversaries (US, GCC, Israel) in an attempt to make them blink first? Note that attacs have indeed increased. Also note that Israel has not been attacked recently. I suspect this is because Iran understands that Israel would not hesitate to retaliate in an unlimited fashion if the damage inflicted was too serious.
According to the New York Times:
-
Across the lower 48 states, the average temperature last month was 75.6 degrees Fahrenheit, the highest on record for August and 3.5 degrees Fahrenheit above the 20th-century average, the National Oceanic and Atmospheric Administration said on Wednesday.
-
The average air temperature at the planet’s surface last month was 1.65 degrees Celsius, or roughly three degrees Fahrenheit, higher than it was at the start of the industrial age, when large-scale burning of fossil fuels began raising global temperatures.
-
August tied the record for the oceans’ hottest month in history as well, scientists said. El Niño conditions caused warm water to gather at the surface of the tropical Pacific.This is no bueno
Based on my life experience, the odds of humanity ending are higher.
Worth a look:
“Liberalism after 9/11: We’re still living in the shadow of the war on terror.”(Jerusalem Demsas)
**THE LONG END.**Treasury tripled its bid to $6 billion and the 30Y closed 3bp cheaper through it. Short duration at 1.50 units, no cover left behind it. I’M WRONG IF the 30Y rallies 15bp through today’s 1:00 auction.
**THE PRODUCT, NOT THE BARREL.**Diesel at a record $5.967 and a crack near $108 is the shock; Brent 102.91 is the headline. Long the refiner against the major. I’M WRONG IF distillate cracks give back a third of August with crude flat.
**FINANCIALS.**Wednesday sorted the sector by who pays the 4.43% 2Y and who earns it. Long the custodian, short the regional cohort. I’M WRONG IF core CPI prints 0.2% or under tomorrow.
ONE BET.
Primary inflation exposure is 3.25 of 4 units and it is concentration, chosen this time. I’M WRONG IF the 2Y breaks 4.25 and Brent settles under 95.
Brent 105.25 after a 105.84 high on the PPI print and a 101.21 settle, the first settle above 100 since July; diesel $5.967 a gallon, up 36.8 cents in a week, above the June 2022 record of $5.82.
The 10Y closed 4.83% after a 4.857% intraday high, the highest since November 2023, and the 30Y 5.28%, both 3bp higher on the day Treasury tripled its long end buyback to $6 billion.
VIX 17.40 at the high of the morning, up 5.7%; high yield 267bp and 1bp tighter at the 7:30 mark; the S&P closed 7,636.36, 23.6 points through its ~7,660 gamma flip.
Gold 4,370.50 (-2.0%), silver 64.62 (-5.9%), USDJPY 154.37: three of four havens offered on a morning oil is up 4%.
PPI printed +0.4% on the month as expected and 5.4% on the year, core 4.6%; goods +1.1%, services +0.1%, diesel fuel +24.1% and truck freight +2.0% inside it. Hike odds for Wednesday went to 70%. The ECB hiked 25bp to 2.50% and did not pre-commit. August CPI is tomorrow.
I think Wednesday was the first honest test the supply reading has had since the add on September 8th, and it passed. Treasury put $6 billion against the 10- to 20-year sector, three times the $2 billion that was normal three weeks ago, and the 30Y finished 3bp higher at 5.28%. The largest line on the sheet needed a 15bp rally to be wrong; the tape produced the opposite sign.
The 30 year gilt at 5.9 and Bunds at 15 year highs say it in two other currencies. A Bruegel paper by Gene Frieda (via Eurointelligence) gives the list I would have given: private demand for capital from the AI build, higher inflation expectations, more government borrowing pushed out the curve, and central banks gone as the buyer of last resort. A ‘scarcity premium’ on safe paper that took 15 years to build is coming out in weeks.
THE SETUP. The street read on a bigger buyback is lower yields; the tape’s read is that a bigger bid means Treasury is worried about the private bid, and I side with the tape. Mark Spindel’s line, “the market has called his bluff,” is the one that gets quoted (Bloomberg). Robin Brooks goes further in
The Dollar Debasement Trap: markets treat the buyback as a yield cap; a cap gets tested, and Japan showed you can hold the yield or the currency but not both. On 19 August and again Wednesday, the pattern was dollar down, metals up. This morning it reversed (gold -0.83%, silver -3.4%, the yen weaker at 154.18, the dollar flat).THE PRODUCT IS THE SHOCK. Brent at 105.25 is the polite version. Retail diesel printed $5.967 for the week of 7 September, up 36.8 cents in one week and $2.20 in a year, through the June 2022 record of $5.82; ULSD futures (the diesel contract) settled $4.80 on Wednesday, and the US diesel crack hit an intraday record near $108 a barrel (Eurointelligence), against roughly $36 when the war started in February. Saudis say production is lowest since 1990, Russian refinery runs are at a 25-year low near 3.8 million barrels a day, a 380,000-barrel-a-day plant in Bahrain is out, and US refineries are running at 97.2% with nothing left to squeeze. Products got no reserve release; crude did.
Now trace it. The benchmark that printed Monday sets most trucking fuel surcharges with a week’s lag, so this week’s 36.8 cents lands on shipper invoices next week; a Class 8 tractor burns a gallon every 6 or 7 miles, so $2.20 a gallon since March is 30 to 35 cents a mile on a spot rate near $2.20 with fuel. Ocean is calm (the Drewry composite is $4,465 a box and flat), so the transmission is domestic, by road and rail, into food, construction and anything delivered. Diesel is not in the CPI basket by name; it enters via the PPI for transportation and warehousing, then into core goods two to three quarters later. Today’s PPI (headline consensus +0.4% on the month, 5.3% on the year) is the first print with September’s crack in it and Friday’s CPI is the second. I do not need either to be hot for the sheet; I need the products chain to keep transmitting, and it is.
THE CASE AGAINST, and I read the whole thing. Henrik Zeberg laid out
twelve exhibitsthis week and his conclusion is the opposite of my sheet in the short run: a final Nasdaq melt-up to 37,000 to 39,000 with the VIX crushed to 10 to 12 first, then the break. His economy exhibits are real (a 52,000 a month twelve-month payroll average against a 130,000 to 200,000 recession-entry band). His altitude exhibits are real (market cap near 238% of annual GDP against 146% at the 2000 peak; the top ten at 41 to 42% of the index; margin debt at 4.45% of annual GDP, nearly half again the dot-com extreme). Where I part with him is the crowd. His “all in” is retail: Citadel’s “unprecedented” participation and JPMorgan’s finding that retail sold the other 470 names to buy the top 30. The institutional crowd is doing the other thing: Goldman’s long-short clients cut net exposure sharply this month, its sentiment indicator is back at -0.1 and Schwab’s activity index fell for the first time since April. Two crowds, and a melt-up needs the second one. Could the de-grossing institutions be the fuel for his last leg? Yes, and that is why the index volatility line is long and held to the 18th.
The consumer is where the two shocks meet. Homebuilders (ITB) closed 90.31, under every moving average and testing the 88 floor that held in June 2025 and June 2026, with the 30 year mortgage at 6.85% and the qualifying income for a median home at $124,674, 5% above what a median household earns. Consumer discretionary (XLY) closed 112.46, -1.34% Wednesday, under all three averages, with 104.50 the next support. Signet and Academy beat and raised on the same day Car-Mart lost 41% and Casey’s lost 14%; the middle is fine and the bottom of the credit stack is not. The retail short and the card pair on the sheet are that sentence, expressed at the checkout.
8:15 ET, the ECB, delivered. 25bp to 2.50%, effective the 16th, with the Middle East named in the first sentence and ‘not pre-committing to a particular rate path’ in the guidance. No ‘last one’ language in the statement; Lagarde at 8:45 is where it would come, and the European bank pair holds until she says it.
8:30 ET, August PPI, printed. +0.4% on the month as expected, with July revised up a tenth; core +0.2% after a July revised up to +0.3%. On the year, 5.4% headline and 4.6% core, against a 2% goal that is written for consumer prices. Goods +1.1% on energy +4.2% (up 24% on the year), services +0.1%. The composition is the supply reading’s: diesel fuel +24.1% on the month, truck freight +2.0% and 14.3% on the year, air cargo +1.5%, rail flat. The other line in it is hardware: electronic components +3.4% in August and 28% year over year, computers up 22.5% year over year, which is the AI build showing up as producer inflation and not just as capex. Yields moved higher on it and WTI is back at 100; hike odds for Wednesday went to 70%. I mark which end of the curve led at the open, and that, not this paragraph, decides the 30Y-versus-2Y test. No size changes.
1:00 ET, the 30 year auction, plus another buyback. The higher variance event. A 2bp tail with soft indirects puts 5.40% in play; a stop-through with a 30Y back under 5.25% is the print that makes me wrong.
After the close, Oracle. Options price an 11% move. ServiceTitan and Braze set the bar this week at ‘show AI revenue or get sold.’
**The conflict, up top:**semis are bid pre-market (SOXX +0.68%) on the morning TSMC’s record August (+53% year over year) was sold, while the Russell lost 1.32%. One tape is paying AI and selling everything that needs a bank.**TBBK, -22%.**Chime is buying Stride Bank for $590 million and moving its banking there, which removes the largest customer from the rent-a-charter model. Pathward, Coastal Financial and Green Dot are the read-across; none is on the sheet, because the short leg of the custody pair already carries the small-bank funding argument.
**FCX, -6.8% pre-market, copper -3% from a record $14,875 a ton.**The White House has not decided on refined copper tariffs (Reuters). The sheet’s only metal-adjacent line is CF, which runs on European gas and not on a tariff.
**ORCL, tonight.**Lagging all year on the debt behind the AI build, options price 11%, and TSMC’s record month could not lift its own ADRs. A miss on backlog turns an AI capex worry into an index problem with the index already through its gamma flip, and the front-dated volatility position is the only thing on the sheet that pays for that.
Behind the wall this morning:
THE BOOK: 15 live lines, 4 new today, each with the factor it monetizes, its size and the condition that kills it, at the line cap for the first time.
The financials sleeve rebuilt off Wednesday’s 286bp of subsector dispersion: the regional cohort moved from the long side of one pair to the short side of another, and why.
Why index volatility at 16.68 is the cheapest line on the page into a $9.6 trillion expiry, with the flip level that already broke.
Every kill switch with its distance to trigger as a number, including the one that is live on this afternoon’s auction tape.
Everything above this line is free and always will be. What’s below is where I put my own capital. $450 a year at marketmusing.com, or the price of one bad lunch a month.
Disclaimer: Opinions are mine alone and may change. It does not constitute an offer to buy or sell or a solicitation of an offer to buy or sell any security, loan or asset or to participate in any trading strategy. It is not intended to form the basis of any investment decision, should not be considered a recommendation, and does not constitute an offer or solicitation with respect to the purchase or sale of any investment, nor is it a confirmation of such terms.
PAID SUBSCRIBERS BELOW THIS LINE