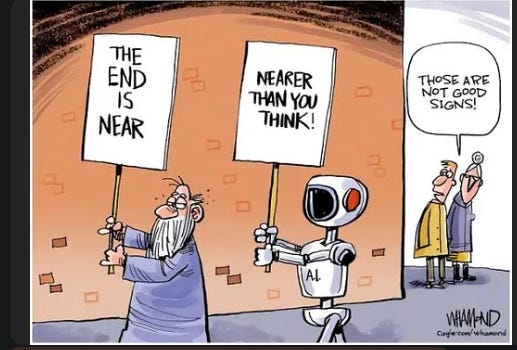
"Over? It’s not over. Nothing is over until we decide it is." Bluto Blutarsky
Asymmetry
Some topics live on the back burner. This one has been sliding between burners for the better part of a year, and with the midterms coming into view, it moved to the front, and somebody turned up the heat. So I have had more time and more reason to cogitate (one of those words you never hear anyone actually say out loud), and I have had a few long conversations with a dear friend who helped me parse it. Thank you, GBG.
Fact: the electoral system is broken. Not “strained.” Not “under stress.”
**Broken.**Start with the arithmetic, because it’s not up for debate. The Electoral College math all but precludes a real third party. You can admire the idea, you can fund the idea, you can put a very rich man’s name (hello, Ross) on the idea and buy the ballot access.
t. Every serious third-party run of the last fifty years has been a spoiler or a footnote, and usually both.The map still eats iThen layer on the primaries, which have handed an extraordinary and frankly dangerous amount of influence to the passionate (read: the extremes) of each party. They are the ones who show up. They are deeply involved, zealous, and the vast majority of primary voters. The rest of us are ‘busy’, and we have decided that being busy is a reasonable excuse. It is not.
Now add a deep and well-earned distrust of the country’s institutions, the government, and ‘traditional’ politicians. Stir. Voila. The wing candidates on each side punch way above their weight class.
So — actual wing nuts and wiccans aside — we get MAGA candidates, and we get DSA candidates, and the great silent majority on each side spends its evenings wringing its (our?) hands about the radicals across the aisle. Turnout does not move. Distress goes vertical.
Here is the part I needed help working through, and it is the part that vanishes inside the echo chamber: the two sides are NOT symmetrical.
On the Right, the extreme wing is now a significant faction, arguably the controlling one. On the Left, that is not yet true.
. Those two words are critical.Not yet
THE LEFT
I am no fan of Chuck Schumer ( please retire, Chuck) or Hakeem Jeffries, but whatever else they are, they are not socialists, democratic or otherwise. I was and remain repulsed by Graham Platner, but note what actually happened: he was not the party’s choice; Janet Mills was. A dissatisfied wing voted for him ( see above). I wish the party would disavow Hasan Piker and his anti-semitism, but the man is an influencer, not a party officer. You can reject most of Abdul El-Sayed’s policies and positions, as I do, without missing the forest for the trees. He is the exception, not the rule.
Look at who is actually winning the arguments. Roy Cooper in North Carolina. Jon Ossoff in Georgia. Josh Turek in Iowa. James Talarico in Texas. Mary Peltola in Alaska. Yes, the populist and progressive wing has a bigger seat at the table than it had ten years ago. But it is one voice in a group conversation, not the only perspective allowed in the room.
THE MECHANISM
Perspective: this is not virtue.
**Democrats have not developed better character since 2016.**They have four things the other side does not, and only one of them is structural.One, there is no enforcement node. On the Right, one man’s endorsement functions as a switch, and everyone in the conference knows the position of that switch at all times. There is no Democrat whose disapproval ends a career. Not Schumer, not Jeffries, not Obama, not AOC. Disapproval on the left is a bad news cycle. On the right it is a retirement announcement.
Two, the money points the other way. Republican primary money funds challengers to incumbents. Democratic institutional money, the committees and the large donors, funds incumbent protection and general-election viability. Same dollar, opposite direction, completely different party.
Three, the electorate itself. The Democratic primary electorate still runs through Black voters, older voters, and union households, three of the most reliably moderate blocs in American politics. The Republican primary electorate is far more ideologically uniform. The median Democratic primary voter therefore sits much closer to the median general election voter than his Republican counterpart does. That is the whole ballgame, and almost nobody says it out loud.
Four, fear. A party out of power and organized around beating one man selects for who can win, not for who is pure. Loss aversion is a powerful moderating drug.
Look at that list again. Only the third one is structural. The other three are cyclical, and cycles turn.
THE RIGHT
Let’s call it like it is.
Support Trump and MAGA policy, or the party primaries you. That is not a characterization; it is an operating procedure with a track record. Thom Tillis. John Cornyn. Bill Cassidy. Thomas Massie. Different men, different states, different sins, same lesson. And notice how often the mechanism works without a primary ever being held. The threat clears the field. That is the tell of a controlling faction, not a loud one.
Then look at who funds it and who whispers to it. The leading contributor to the Republican Party, Elon Musk, is an open anti-semite. Read his posts on Twitter (yeah, yeah, “X”). He wrote enormous checks to the AfD, a resurgent fascist party, in Germany. Tucker Carlson, a major supporter of and advisor to J.D. Vance, has openly blamed Israel and the Jews for everything he believes is wrong with this country. His latest podcast pins gambling and pornography on them. Laugh if you want. He has an estimated 30 to 35 million followers; he has floated starting a third party, and a lot of serious people think he runs in 2028. Peter Thiel, another Vance advisor, has called for a technological autocracy. He is an acolyte of Curtis Yarvin. Look him up. I will wait.
These are not fringe accounts shouting into a feed. These are the leading influencers of the party’s leadership.
WHY “NOT YET” IS THE WHOLE PROBLEM
Honest tension, stated and not buried: three of the four things restraining the Left are conditional. Take away the fear by winning big, and the electability discipline goes with it. Give the Left a single figure whose blessing decides primaries, and the enforcement node appears overnight. Point the donor money at incumbents instead of at Republicans, and the direction of travel flips. None of that requires a change of heart. It only requires a good election.
So the asymmetry is real, it matters enormously right now, and it is not a permanent feature of the landscape. It is a lead, and leads get closed.
One party has a loud wing. The other has a wing holding the yoke. The question for the next four years is not whether that is true today. It is.
Somebody has been measuring this, and the series runs a hundred and fifty years. The share of Congressional floor speech that codes as angry now sits near 25% in the House and near 21% in the Senate on a three-year average, against a band of roughly 10% to 15% that held from the 1870s to the 2000s (Harvard working paper, Y. Algan et al., August 2026). Whatever you want to call the last decade, it is not a wobble inside the normal range. The normal range is on the chart and this is not in it.
Which is a strange thing to read on a morning when a Treasury Secretary told a room in Texas that he has ‘asymmetric information’ on what the Bank of Japan is going to do, and then said, out loud, “I am the house now. You can bet against me if you want” (FT).
Two dares in one morning. Step out of line and the party primaries you. Sell the yen and the sovereign takes the other side. Neither one is an argument. Both are somebody announcing that the outcome is already decided,
which is the single most reliable sign that it is not.
Subscribe at marketmusing.com.
**THE BARREL.**Brent 100.58 is being paid in crude and refused everywhere else. Long the premium at a quarter unit, no more. I’M WRONG IF energy equities lead the tape.**THE FRONT END.**Third consecutive front-end-led close, this one with no policy input at all. Short duration at 1.5 units into it. I’M WRONG IF the 30Y rallies 15bp on today’s operations.**FINANCIALS.**Tuesday’s 256bp of subsector dispersion sorts by liability duration, not by margin. Own the cohort ratio, not the sector. I’M WRONG IF high yield clears 290bp with the 10Y still rising.**THE ADMISSION.**Six factors on the sheet and 2.00 of 6.50 units sit in one combined inflation bet. Concentration, stated. I’M WRONG IF the 2Y breaks 4.25 and Brent settles below 95.
Brent printed 100.58 with a session high of 100.95, the first hundred handle since July and a fifth consecutive session above 95.
The curve backed up in near-parallel to 4.39 / 4.80 / 5.25, leaving 2s10s at +41bp and 2s30s at +86bp.
Equity futures are flat against all of that. VIX 15.87. The barrel is the only instrument paying the premium.
Financials were the worst of eleven Nasdaq-listed sectors Tuesday at an equal-weighted minus 1.66% on a session that firmed hike odds.
Sixteen positions closed on the consolidated sheet this morning on the mark rule rather than on a view. Gross fell from 21.75 units to 6.50.
The barrel is doing the whole job and nothing else has agreed to help.
Brent went through a hundred for the first time since July, sat 37 cents off its session high at 100.58, and has now held above 95 for five sessions. WTI 94.59. The reason is not in dispute: US Central Command destroyed five Iranian tankers Tuesday after Iran tried to hit a US warship with ballistic missiles, Houthi strikes on Saudi energy infrastructure wounded 73 civilians and shut facilities in the kingdom’s south, and Saudi Arabia has promised retaliation (Al Jazeera). Throughput through Hormuz is at a wartime record, which is the part nobody says out loud. The oil is still moving. What has repriced is the insurance on it moving. A ‘route problem’, not a price-level problem.
Now look at what refused to move with it. Equity futures came in flat, ES +0.02%, NQ +0.09%. Energy equities averaged +0.03% Tuesday, on the session crude ripped, and XLE closed 64.77 as the best sector in a red tape by a whole 1.11%. VIX 15.87. Gold went to 4,444.70 and ended three straight declines, which is a bid, and it is a modest one.
A ‘supply shock’ the equity market believes gets paid for twice: once in the barrel, once in the multiple.
This one is being paid once.
AS ALWAYS, START WITH THE COMPOSITION, because it is the load-bearing number in the piece and it deserves its construction shown.
Three consecutive sessions. Three completely different inputs. And the front end did more work than the long end every single time. 2s30s went from +91bp to +86bp across them. If the story here were a term premium story, a fiscal story, or a supply story, the thirty year does the moving. It has not, three times, and the third time had no policy input in it whatsoever.
THE CASE AGAINST ALL OF THIS, and it is not weak.
A cohort of the bearish letters, Hussman Funds among the more rigorous of them, would say the whole exercise is beside the question, because valuation and internals already did the arithmetic, and the composition question is a distraction from a market priced for a decade of nothing going wrong. Also fair, and it has been fair for a while, which is the problem with it as a timing instrument.
The second objection is the one I actually respect. Today’s Treasury buyback operations run at no less than $4 billion per operation in the 10-to-20 and 20-to-30 year sectors, twice the prior size. If the long end rallies 15bp into that, then the last three sessions were a supply artifact and the policy reading was wrong, and I will have been offside on the largest position on the sheet at the largest size it has carried since July. Not a hedge. The print, and it lands this morning.
WHAT THE FRONT END IS ACTUALLY SAYING.
Fed funds futures put the September 16 meeting at an implied 3.786% against a current implied overnight of 3.622%, which is 16.4bp and roughly a 65.5% hike. The effective rate is 3.63% under a 3.75% upper bound. Headline PCE ran 3.7% year over year in July and the six-month annualized rate sat at 4.1%, which is what Chair Warsh has been citing, and July core CPI was 2.5% year over year against a 3.4% headline. The Cleveland nowcast has August headline CPI at 3.38% year over year and plus 0.36% month over month, with core at 2.38% and plus 0.20%. The July energy index was already running plus 14.7% year over year before this crude move.
So the leg owes an answer on what it needs beyond the meeting, because 65.5% is mostly in.
Not the hike. What the duration short needs is not the hike. It needs the path: an implied peak that holds near 4.30% out to late 2027 rather than rolling over, and a 2Y that stays above 4.35% while it does. The futures strip currently prices the peak at around 4.295% in October 2027, then down to 4.157% by December. That rollover is the trade’s real opponent. Not Friday.
THE PART THAT IS NOT ABOUT OIL AT ALL.
Line up the safe havens and the composition is more interesting than the direction. Gold bid. Bonds offered, the whole curve backed up. Yen bid, 153.38, up roughly 4% on the month and well under both its 50-day at 160.36 and its 200-day at 158.44. Dollar offered, DXY 98.76, sitting near the May low and approaching a seven-month trough.
Some bid, some offered, so a ‘rotation’ rather than a ‘de-gross’. But read which ones. The two havens being bought are the two that are not American. The two being sold are American duration and American currency. Money is not leaving risk this morning. Leaving America, rather, and paying for the exit in gold and yen.
Which is the tape’s answer to a Treasury Secretary claiming he is ‘The House’. A sovereign that has to say out loud that it holds asymmetric information on another sovereign’s central bank has already told you the position is uncomfortable. The yen is up 4% on the month anyway, and the euro cross against it, EURJPY, is down 3.56% on the week at 178.52. Whatever the intervention is doing, the cross is not behaving like a market that believes the dare.And Europe took the same shock harder than we did. Euro Stoxx 6,345.68, minus 1.05%. DAX 25,775.78, minus 0.89%. Bunds at fifteen-year highs. A far-right win in Saxony-Anhalt is now part of the German rate story rather than a separate news item, and Canada’s retaliation on roughly $20 billion of US goods took effect Tuesday with a US ban on Canadian dairy, alcohol and motorcycles landing September 29. Everybody is repricing the same shock. Only one of these markets is pretending it did not happen.
Ours.
Pump prices set a record for any Labor Day at $4.15 a gallon. That number reaches a household before any of the rest of this does, and it is the reason the trades in consumer sleeve are expressed at the checkout rather than in the credit file.
**Treasury buyback operations, from this morning.**At least $4 billion per operation in the 10-to-20 and 20-to-30 year sectors, twice the prior size. A 15bp long-end rally through the tape flips the largest position on the sheet, and it is the only intraday rule I run.**Poland’s rate decision, expected hold at 3.75%.**All 34 economists surveyed see no change, so this only matters if it moves.**The Huawei racketeering trial opens in Brooklyn.**Trade secrets, wire and bank fraud, expected to run for months. Watch it for the supply chain, not for a print.**No major US release.**Which makes today’s buyback tape the whole calendar, and that is unusual enough to point to it.
**The conflict, up top:**memory and defense are both bid on the same escalation, and one is a demand story with a two-year order book while the other is a re-stocking story that clears on a ceasefire headline. They do not survive the same ne…