"Real knowledge is to know the extent of one's ignorance." Confucius:
Some days — as a parent, as an adult, and certainly as a trader — it is important to be able to say things like ‘I don’t know’ or ‘ I don’t understand it’. Some days, I feel like Sgt. Schultz; watching the market shrug off all the headwinds these days, I feel a kinship with the comic star of Hogan’s Heroes. With that said…
**THE BOND MARKET IS DOING THE FED’S JOB, AND EQUITIES ARE ASLEEP AT THE WHEEL.**Rates, crude and mortgages broke higher; the S&P lost 0.75 percent. I’M WRONG IF the 10-year closes back under 5.00.**ENERGY IS THE INFLATION PRINT THE MARKET KEEPS DISCOUNTING.**Gasoline is $4.48, diesel is at a record, and US crude stocks sit near 1984 lows. I’M WRONG IF Brent settles under $95.**HOUSING IS WHERE THE RATE MOVE GETS PAID FOR FIRST.**A 7.12 percent mortgage, 19.5 percent of listings cut, builders on range lows. I’M WRONG IF the builders fund reclaims its 200-day at 97.84.**THE CALM IS IN THE PRICE, NOT THE DATA.**VIX 16 against a MOVE of 95. I’M WRONG IF the 7-year at 1 PM clears cleanly and the belly rallies 8bp.
I think equities are treating a rates shock, an oil shock and a housing freeze as three separate headlines, and none of them as their problem.
Yawwnnnn. The S&P fell 0.75 percent on the day the 10-year made a 19-year high. That is a shrug, and it looks a lot like complacency; equity investors have decided ‘higher for longer’ is somebody else’s problem. Willful ignorance is a position too, and it gets marked like one.
RATES.
The official curve closed Wednesday at 4.85 on the 2-year, 4.99 on the 5-year, 5.11 on the 10-year and 5.40 on the 30-year. Overnight the 10-year traded 5.14 and the 30-year 5.44, its highest since 2004 (Bloomberg).
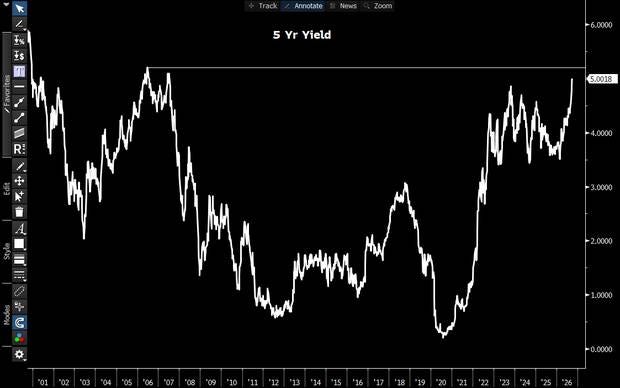
The belly led. The 5-year and 7-year each rose 16bp against 11bp in the 30-year, and the 5-year is back to 5.00, a hair under its 2006 high.
The real 10-year, measured against core CPI, was 2.30 at the end of August, a level it has not held since before 2011. The Fed now owns a positive real rate and it is still hiking.
Fed funds futures price about 2.4 hikes for calendar 2026, last week’s included, from minus 2.7 in November. October odds are near 73 percent (CNBC).
WHAT SET IT OFF. A survey. The S&P Global flash composite hit 58.4, the highest since July 2021, with manufacturing at 57 against 53.6 expected and services at 58.7 against 56. Input prices rose at their fastest pace in 47 months and employment hit a four-year high. Robin Brooks said what I keep coming back to: a second-tier release was enough to spark a global selloff, and the French 10-year rose more than the US 10-year on American data (Robin J Brooks). That is a bond market looking for a reason. It got one at 1 PM, when the $70 billion 5-year tailed 3.1bp with a 2.21 bid-to-cover, the weakest since December 2018.
ENERGY. Crude is the input equity investors have decided to live with. I don’t think they can for long.
**The price.**November Brent touched above $106 overnight, after an adviser to Iran’s supreme leader said Tehran may take the war into the Indian Ocean if attacked again, and after President Pezeshkian told the UN there will be no freedom of navigation through Hormuz while the blockade stands. Crude is up more than 70 percent this year (Bloomberg).The shock absorbers.“This is a market with very little shock absorbers left,” said Emily Ashford of Standard Chartered (Bloomberg). A cargo ship was left adrift and burning in the strait after being hit by a projectile, and an armed group blockaded Libya’s El Sharara field.**The inventory.**Total US crude including the Strategic Petroleum Reserve rose last week and still sits near 700 million barrels, close to its lowest since 1984. The SPR alone fell to about 285 million barrels, its lowest since 1982. EIA showed a 2.97 million-barrel commercial build, with refinery utilization at 94.0 percent.**The products.**Gasoline stocks sit at the bottom of their five-year range and distillates near the low end. AAA’s national average is $4.483 a gallon, above every moving average on the chart and within sight of the spring spike. Retail diesel is at a record (Bloomberg).
THE DIESEL FIGHT. Energy Secretary Chris Wright told oil executives to brace for possible curbs on diesel exports, then floated a voluntary fix. Morgan Stanley says a ban could raise US gasoline prices by pushing refiners to cut runs (Bloomberg). European diesel futures jumped and Repsol and Neste each rose about 3 percent. A policy built for the midterms that raises the pump price is a policy I’d bet against surviving contact with November.
HOMES. This is where the rate move gets paid for first.
**The rate.**The MBA 30-year contract rate hit 7.12 percent, the highest since May 2024, while the effective rate on outstanding mortgages is still near 4.3 percent. Nobody with a 3 percent loan is listing unless they have to.**The cuts.**19.5 percent of listings had a price cut in August, the highest August share in Redfin data back to 2020, and 45 percent of sales carried a seller concession. The typical home sat 50 days, up from 36 when rates were near 8 percent almost three years ago. 1.5 million homes are for sale, up 46 percent from 2023 (Bloomberg).**The anecdote.**A Marlborough, Massachusetts seller cut his $1.28 million listing twice in under a week, $136,000 in all, the second cut on the day the Fed hiked. “Unfortunately, housing is roadkill here,” said Susan Wachter of Wharton. NAR’s Lawrence Yun calls 7 percent the “new normal” (Bloomberg). I’d call it the new normal only if you are not trying to sell.**Refinancing.**The MBA refinance index for 2026 is running near the bottom of every year since 2015.
WHY THE SHRUG BOTHERS ME.
The Fed is hawkish and the multiple is only starting to notice. Bloomberg’s Fed sentiment index has swung hard toward hawkish while the S&P forward multiple has come off from about 22 to 19. It has further to go if the index is right.
Stocks and bonds fell together Wednesday: TLT down 1.58 percent, LQD down 1.14 and HYG down 0.74 on a 0.75 percent S&P day. A 60/40 book had nowhere to hide.
Investment-grade corporate yields hit 5.87 percent and high yield 7.92. Money is expensive again for everybody who has to borrow it.
THE CASE AGAINST. The benign read is that this was one survey and one auction. Surveys that jump 2.4 points in a month often give half of it back, and quarter-end duration buying lands next week. The 10-year spent most of 2023 and 2024 between 4 and 5 percent without breaking anything. If the 7-year clears at 1 PM and the belly rallies, Wednesday was an auction accident with a PMI attached. I would believe that more if gold were rallying (it is down) and the dollar were not on its longest winning streak in weeks; neither looks like a market that expects the scare to pass.
**08:30 ET, jobless claims.**Survey 200,000 against 196,000 prior. A labor market this tight is one more reason the October hike stays priced.**08:50 and 10:10 ET, Hammack and Paulson.**Williams already said this morning in London that a year-end hike is “a reasonable way of thinking about it” and that “inflation’s been above target for five years” (Bloomberg). US inflation ran 3.4 percent y/y in August. Anyone pushing back on October moves the 2-year.**10:00 ET, new home sales for August.**Survey 615,600 annualized against 607,000. The rate move since then makes the number stale on arrival.**13:00 ET, the $44 billion 7-year.**Dealers took 15.8 percent of Wednesday’s 5-year, the most since May 2024, and indirects took 54.31 percent, the fewest since March 2020. A second tail makes the belly the weakest point on the curve into September 30.**Trump and Xi, day two.**Bessent extended the trade truce to January 10, 2027. Chinese stocks fell anyway, on reports the extension was shorter than Beijing wanted (Bloomberg).**The rest of the world is tightening too.**Norges Bank hiked 25bp to 4.50 percent, the Riksbank held at 1.75 and flagged a hike, and the SNB held at zero. The 10-year JGB rose 10bp to 3.075 percent, its highest since 1996, and the average yield on global government debt is near 4 percent, a level last seen in 2007 (Bloomberg).**Darden before the bell, Costco after.**Darden is expected at $2.05 a share after McDonald’s fell 4.8 percent to a 52-week low on a weaker traffic outlook.
KB HOME. Fell 3.0 percent to $47.16 on housing revenue down 20 percent, orders down 12 percent and a weaker fourth-quarter margin guide. D.R. Horton lost 2.8 percent and Lennar 1.8. The builders fund is at 88.79, on the bottom of a range that has held since mid-2025 and under both its 50-day at 95.23 and 200-day at 97.84. A break there is the market admitting the rate move is permanent.
CONSUMER DISCRETIONARY. The group fell 1.50 percent Wednesday. Against the S&P it closed at 0.1441, under every average on the chart. The fund itself is 110.65 with support closer to 104. McDonald’s and Paychex (down 8.8 percent on a softer small-business read) did the damage. Consumer discretionary showing the impact of inflation? I think so.
SMALL CAPS. The Russell fell 1.80 percent Wednesday, its worst day of the three indices. The IWM against SPY ratio is 0.3672, back under all three averages after a failed breakout in July. Year to date the small-cap fund is still up 14.5 percent against 9.7 for S&P futures, so the damage is recent and it is fast.
Behind the wall this morning:
FINANCIALS: why the banks held up on a parallel bear shift, and where the rate move lands inside the sector.
FLOWS AND POSITIONING: who is still leaning long, and why a 16 VIX against a 95 MOVE is the mismatch I’d watch.
I’M KEEPING MY EYE ON: the levels and dates that decide whether the shrug holds.
The free part stops here. The rest is 450 dollars a year at marketmusing.com.