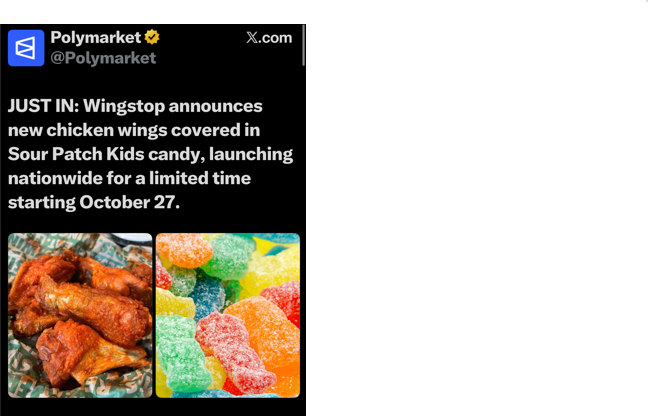
"Your scientists were so preoccupied with whether or not they could, they didn't stop to think if they should." Ian Malcolm, Jurassic Park
Latest example of ‘just because you can most definitely does not mean you should’
So the good people at Wingstop, apparently with nothing more pressing on the agenda, have decided that what America needs right now is chicken wings covered in Sour Patch Kids. Nationwide, starting October 27, for a ‘limited time’ (small mercies). I have questions. Was there a meeting? Did anybody in that conference room put a hand up and say ‘guys, maybe not’? And I learned about it from Polymarket, a betting site, which now apparently also breaks news about bar food. Because it can.
I think that is the problem these days, in the kitchen and well beyond it. Somewhere along the way we stopped asking ‘should we?’ and settled for ‘can we?’ A partial list, from this morning’s reading alone:
The Houthis are building their own medium-range ballistic missiles, Iranian design, Chinese parts, roughly 1,200 miles of range, which puts all of Saudi Arabia and Israel in the box. Aramco’s headquarters in Dhahran took a hit last night (limited fire, per the Saudis). Because they can.
Iran is hitting tankers around Hormuz to keep oil above $100 into our midterms, and its officials say so on the record. Because it can.
The White House announced an ‘energy ceasefire’ in Ukraine that Moscow appears never to have heard of, and cut a diesel deal with Putin three weeks before an election. Russia answered by hitting Kyiv’s power plants. Because it could.
Private credit spent two years lending to buyouts at tighter and tighter spreads (73% of this year’s deals priced under 500 over SOFR, against 9% in 2020) because the money kept walking in the door. Now it wants to walk out; Blue Owl’s tech lending fund has seen redemption requests near 40% three quarters running.
And the people building AI are, per Axios, privately war-gaming the public revolt that follows the first catastrophic AI event, which many of them consider inevitable. They are building it anyway.
None of these, on its own, ends the world. Each is a clever person solving a narrow problem with the tools at hand. Put together, it is a lot of candy on a lot of wings.
As in the kitchen, so in markets. The S&P closed Tuesday a fifth of a percent under its record while the median stock sits 15% under its own high. Fund managers are the most overweight technology since August 2020 and the most underweight consumer discretionary since 2008; NYSE has gone 224 sessions without an 80% downside volume day, the longest run since at least 1996. The index can keep levitating on a handful of names, so it does. That doesn’t mean it should, and in my experience the bill for ‘because we could’ always comes, usually right after somebody orders seconds.
I’ll have the bar pizza, thanks.
**PRIVATE CREDIT GETS THE BILL FOR ‘BECAUSE WE COULD’ FIRST.**I like the premium BDCs from the short side. I’M WRONG IF high yield prints near 290bp with the 10-year above 5.00.**THE BOOK IS ONE BET ON RATES AND SPREADS STAYING HIGH.**I stay short gold and high yield. I’M WRONG IF core prints 0.2 percent m/m or less with the 2-year under 4.75.**MEMORY HAS A PRICE PROBLEM, NOT A DEMAND PROBLEM.**I like Micron from the short side. I’M WRONG IF the Kospi closes above 6,300 on foreign net buying.
I think the market has spent two years doing what it can, and the bill arrives in the plumbing before it arrives in the index.
**THE SETUP.**No regulator forced private credit to lend to buyouts at 450 over. The money was there, so it got lent.In 2020, 9 percent of private-credit LBO financings priced under 500bp over SOFR. In 2026 it is 73 percent, and the share over 700bp fell to 2 percent from 23.
The yield on private credit fell to 9.1 percent by June against 8.6 percent on leveraged loans; the spread premium that used to run above 2 points is close to nothing.
So the buyer is paid almost nothing extra for giving up the exit. That works until investors want the exit.
**THE EVIDENCE.**They do. Redemption requests at Blue Owl’s technology lending fund ran 40.7, 38.1 and 39.0 percent of shares in the first three quarters, against caps near 5 percent (Reuters, from SEC filings). High yield printed 311bp for 12 October while CCC sat at 1,252bp, a fresh cycle wide. The top of the capital structure looks calm because the stress is parked where the index cannot see it.**THE CASE AGAINST.**Three things argue the other way, and I take them seriously:The headline spread tightened 4bp on the first fresh print in five sessions. A credit event usually starts with the index, not against it.
The queue could also be a liquidity mismatch with no loss attached. A gated fund still collects its coupons (and ‘gated’ is a feature the buyers signed up for).
The other read of the buyout table is selection: the best borrowers got the deals, and that would look exactly like complacency in these charts.
**THE RATES LEG.**The rest of my book needs the same thing private credit does not want: rates and spreads staying high. A 10-year at 5.21 and a 30-year at 5.56 on Tuesday’s official curve sit above the whole 4.80 to 5.00 band I started from. The test is 08:30. Headline is known to be hot on gasoline; core decides it. Core at 0.3 percent m/m or more revives October hike pricing, now about one in five. A soft core read that pulls the front end down 5bp from Tuesday’s 4.79 close is the print that costs me the most.**THE WAR.**The Gulf is doing what it can, too, and the barrel keeps absorbing it.A Houthi strike started a ‘limited fire’ at an Aramco administrative building in Dhahran late Tuesday, and intercepts were reported over Riyadh and two other Saudi locations (
Al Jazeera).The Houthis are assembling a version of Iran’s Kheibar Shekan from Chinese-supplied parts, roughly 1,200 miles of range (WSJ, Conflict Armament Research).
The IEA says Gulf crude exports are approaching pre-war levels, and Saudi output rose more than 2 million barrels a day in September.
So Brent at $106.55 is a premium on the risk to infrastructure, not on lost barrels. I own that premium through freight and a small call spread, not through the barrel itself.
**THE AI LEG.**ASML guided fourth-quarter sales to a €14.7 billion midpoint against €14.0 billion expected and said customers are asking to place orders for 2029 and 2030. On the same tape Micron fell 3.6 percent and Applied Materials 6.7 percent on CXMT’s denser memory cell (CXMT is China’s state-backed DRAM maker). Is that a demand scare? The selloff may simply be a crowded long de-grossing after a 5x run, and part of it is. I don’t think that is all of it. The machines sell; the chips they make get cheaper. That is a cost curve, and it hits the memory names before it touches the toolmakers.
**08:30, September CPI.**Consensus +0.6 percent m/m headline, +0.2 core. Small firms’ price plans just turned up again, and they lead headline inflation by about three months.**Before the open, Morgan Stanley, State Street, Progressive.**Wealth flows and trading against a bar Goldman set at $17.01.**14:00, the Beige Book.**Watch the word ‘demand’ next to ‘rates’.**15:00, the official curve.**A 30-year close under 5.55 starts my trim test.**Overnight, China’s September trade.**Exports rose 36.3 percent y/y against 25.7 expected on AI hardware, and PPI ran 5.0 percent y/y; the record surplus is the other side of the capex boom (FT).**Thursday 08:30, PPI and retail sales; TSMC before the open.**Fourth-quarter capex near $20 billion is the street number.
Two of these point opposite ways, and I am short one of them: the toolmaker guided up while the memory maker it supplies kept falling.
**ASML.**EPS €12.93 against €10.71, operating margin 44.4 percent against 41.8, and a capacity review beyond the 30 percent already planned for 2028. Up a couple of percent in Amsterdam. Capacity growth that fast eventually reaches memory supply, which is the part I am short.**MICRON.**Down 3.62 percent to 953.19 Tuesday, the sixth straight decline for US chipmakers, on CXMT’s cell architecture and a patent exclusion filing. I still like it from the short side; TSMC’s guide on Thursday is the next test.**JOHNSON & JOHNSON.**Down 5.73 percent on a MedTech miss inside a raised guide. UnitedHealth gave back a 5 percent pre-market gain the same day. Health care fell 1.35 percent, the worst sector, and the defensive bid did not show up at a 5.2 percent 10-year.
Behind the wall this morning:
THE BOOK: 10 live lines, 0 new today, each with the factor it monetizes, its size and the condition that kills it.
FINANCIALS: the redemption table, the buyout-spread table, and what Bank of America’s miss says about the funding sort.
FLOWS AND POSITIONING: why the breadth gauges say buy and the crowd still owns ten names.
The note above this line stays free, always; below it is where my own capital goes. $450 a year at marketmusing.com, or the price of one bad lunch a month.