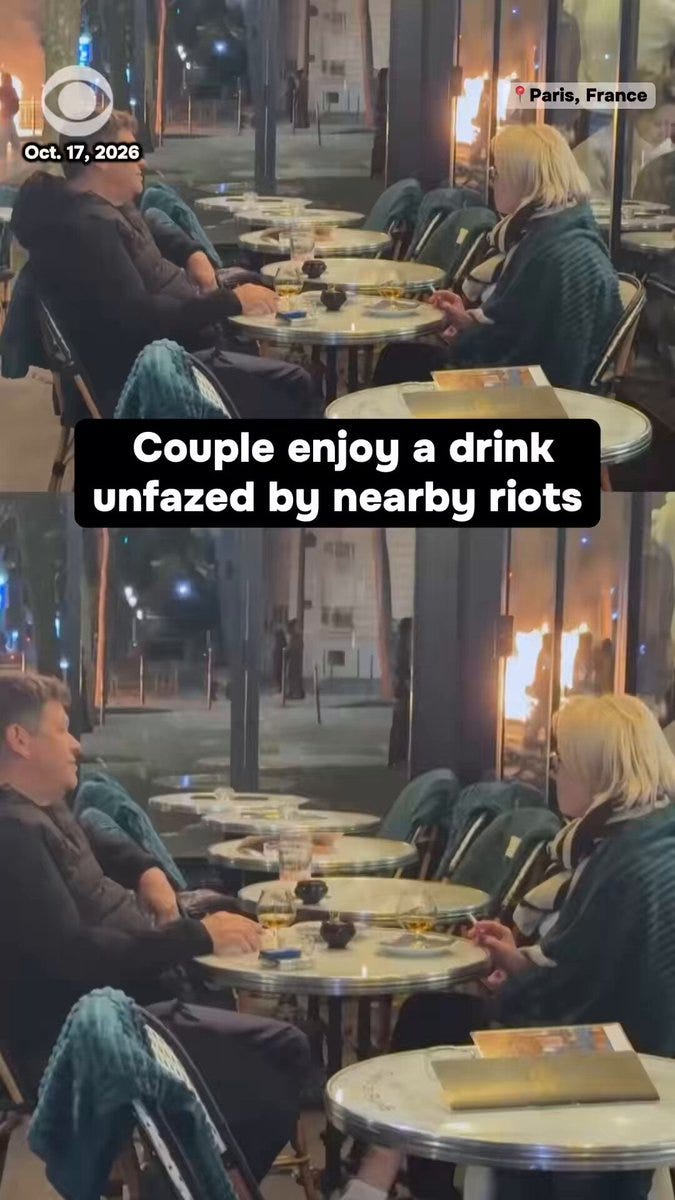
/video/1
"Men have become the tools of their tools." Henry David Thoreau
There’s a video making the rounds from Paris last Friday night. A couple sits at a sidewalk café, cigarette in hand, a glass of something amber on the marble table. A few yards behind them, the street is on fire. They barely look up. Another round, s’il vous plaît.
The market has been doing much the same thing.
High yield spreads pushed through 325 basis points. Brent cleared $110. The long bond sold off even as stocks rallied, which is not exactly the usual flight to safety. Korea fell almost 4% overnight. Yet the VIX is at 18, and the S&P is barely 1.6% off its record.
Apparently, nothing to see here.
Some of this is the French art of sangfroid. Some of it is the market we’ve built. Trend-following funds buy what’s going up and sell what’s going down. Dealer hedging, corporate buybacks, and retail flows can keep things moving in the same direction long after the underlying story starts to change. None of it requires anyone to stop and ask whether the fire is getting closer. The bond vigilantes are trying to get us back on the right path, but equities do not care
It doesn’t matter. Until it does.
The couple can finish their drinks and head home. The café owner has to replace the windows.
**THE LONG BOND IS PAYING FOR THE WAR.**I stay short high yield and keep the duration view in rates. I’M WRONG IF the 10-year closes under 5.00% with Brent above $107.**CREDIT CROSSED ITS LINE BEFORE EQUITIES NOTICED.**I like the credit shorts over the equity shorts. I’M WRONG IF the next high yield print comes back inside 311bp.**THE BANKS ARE BEING MARKED ON DURATION.**I like Wells Fargo from the short side against Citigroup. I’M WRONG IF financials close green with the 10-year at or above 5.15%.**BRENT IS THROUGH $110 ON A CLAIM, AND THE CURVE SAYS IT IS NO CLAIM.**I like Brent’s upside through options. I’M WRONG IF Brent settles below $98 twice.
I think the market spent Monday buying back last week’s chip losers and selling the long bond to pay for it, and the long bond is the part that will stick.
THE SETUP. VP Research put the frame on it this morning: guns, butter or sound money, and a government cannot have all three. Washington is borrowing to put the choice off. The tape is starting to send the bill:
The index rose 0.41% Monday and the 10-year rose 6bp to 5.15%, with gold down and the dollar firm. A rally with no haven bid under it is a policy and supply tape, unless the bond selling was nothing more than CTAs adding to a trend.
The 30-day correlation between stocks and the 10-year sits at minus 0.40. Higher yields are hurting stocks again, the regime of 2022, and Friday’s chip collapse came with it.
Annual federal net interest costs are about 3.3% of GDP, above the early-1990s peak near 3.2% (Axios).
Federal net interest costs as a share of GDP, 1940 to 2026 estimated, via Axios.
The 30-day correlation of stocks and the 10-year has sat negative most of 2026.
THE EVIDENCE. The constraint is physical, so I take VP’s conclusion that sacrificing sound money buys inflation:
Dated Brent printed $126.55 on 14 October against $87.71 for December 2027 Brent, a spread of $38.8. In January the curve was flat near $61.
December 2027 Brent is at its five-year high of $87.71. The back of the curve has repriced, so the market is paying for a lasting shortage; a war premium alone would sit in the front months.
Asian spot LNG is near $30 per mmbtu, up about 200% from pre-war and the highest since December 2022 (Bloomberg).
Japan is “months” from running out of yttrium as China squeezes rare earth shipments, and Tokyo asked Washington for help (
FT).
Dated Brent against December 2027 Brent; the spread is $38.8.
December 2027 Brent at $87.71, its highest print in five years of history.
Asian spot LNG at about triple pre-war levels, via Bloomberg.
THE BALLOT. Butter is getting decided at the pump. Polymarket’s odds of Democratic control of the Senate have tracked retail diesel all year, both near their highs at about 65 and $6.30. Trump’s approval hit a record low of 31% (Reuters), and the White House answered with an $8 billion diesel relief program for farmers on top of last week’s Russia sanctions waiver.
Polymarket’s Senate odds against retail diesel, via Polymarket and Bloomberg.
THE BUNDLE. The crowded trade is a package: long AI cash flows, short duration risk, short credit stress and short persistent inflation, all at once. It breaks if capex stays high while monetization slips and the long end rises:
The Fed’s September minutes named competition for capital from AI debt issuance as one reason yields rose about 35bp across the 2-year to 10-year curve between meetings.
AI-related debt issuance is near $600 billion this year, about 40% of it from investment grade hyperscalers, against tech capex heading for about $884 billion in 2026.
AI infrastructure names are expected to supply more than half of S&P 500 third-quarter earnings growth.
THE CASE AGAINST. The strongest objection is Marko Bjegovic’s (Arkomina Research): September CPI was mostly gasoline, ex-gasoline headline was 0.30% on the month, and the bond market saw through it. The speculative positioning helps him too. Deutsche Bank has trend followers near the bottom of their bond exposure range, so a weak data run squeezes the crowded side fast, and today’s housing starts could be that print. I take it seriously, and I would believe it on a 10-year close under 5.00%. Monday’s 6bp sell-off into an equity rally does not fit his story.
**08:30, September housing starts and permits.**Consensus is 1.30 million and 1.39 million. Builder sentiment already fell 3 points to 29, the lowest since June 2012, with buyer traffic at 18 and the West at 20.**Before the open, GE, GM, 3M, RTX, Northrop, KeyCorp, Synchrony and Ally.**KeyCorp and Synchrony are the first deposit-cost and card prints after Zions.**10:00, September pending home sales; 13:00, the 20-year auction.**A tail at 5.53% on the 20-year is the supply read I care about.**After the close, Capital One, Chubb, Netflix, United and SpaceX.**Capital One’s card book is the consumer read; Netflix is the first large platform print into Wednesday.**Wednesday after the close, Meta, Tesla, IBM, Lam Research and Texas Instruments.**Capex against a higher financing cost is the AI test.
NAHB builder sentiment by region; the West is at 20.
NAHB future sales at 32 and prospective buyer traffic at 18.
The equities have already voted. ITB is down about 11% and XHB about 7% this year against a gain of about 13% for SPY, and the Atlanta Fed’s affordability index is back near its 2023 lows.
ITB and XHB against SPY in 2026, via The Daily Shot.
Atlanta Fed home ownership affordability index at its cycle low, via The Daily Shot.
The New York Fed’s services survey said the same thing in October: business activity fell 12.0 points to minus 20.7, while prices paid held at 70 and prices received rose to 36.3. Activity falling with prices rising is the mix I am positioned for.
New York Fed Business Leaders Survey, current conditions, October 2026.
New York Fed business activity at minus 20.7.
New York Fed business climate at minus 35.0.
Nvidia and Wells Fargo point opposite ways on Monday’s tape: one was bought back, the other was sold to pay for it.
**ZIONS.**Earnings of $1.78 beat the street, but the beat came from an $8 million provision benefit against an $18 million expense expected, while net interest income missed. Net charge-offs were $3 million against $56 million a year ago. Clean credit and a soft margin is the shape that does not lift a bank marked on rates.**WELLS FARGO.**Down 2.47% to 81.80, the weakest of the big four, with JPMorgan down 1.82% and Citigroup 2.05%. It carries the thinnest common equity tier 1 of the six at 10.0%. I like it from the short side.**ELICE.**The South Korean data center builder fell about 30% on its debut (FT), the same morning OpenAI was reported to be accelerating a raise of about $30 billion at a $1.4 trillion valuation (Reuters). I read the two together: AI capital is still available, and the price of it is rising.
Behind the wall this morning:
FLOWS AND POSITIONING: record put volume, trend followers short bonds, retail buying at a record and the buyback window that opens in November.
FINANCIALS: the fee earners against the levered carry, what AGNC’s 17% book value drop says about the belly, and the two financials trades I want into tonight.
What I see stays free. What I do about it, with my own money, sits below this line: $450 a year at marketmusing.com.
Who Knew — We’re #2!!!!