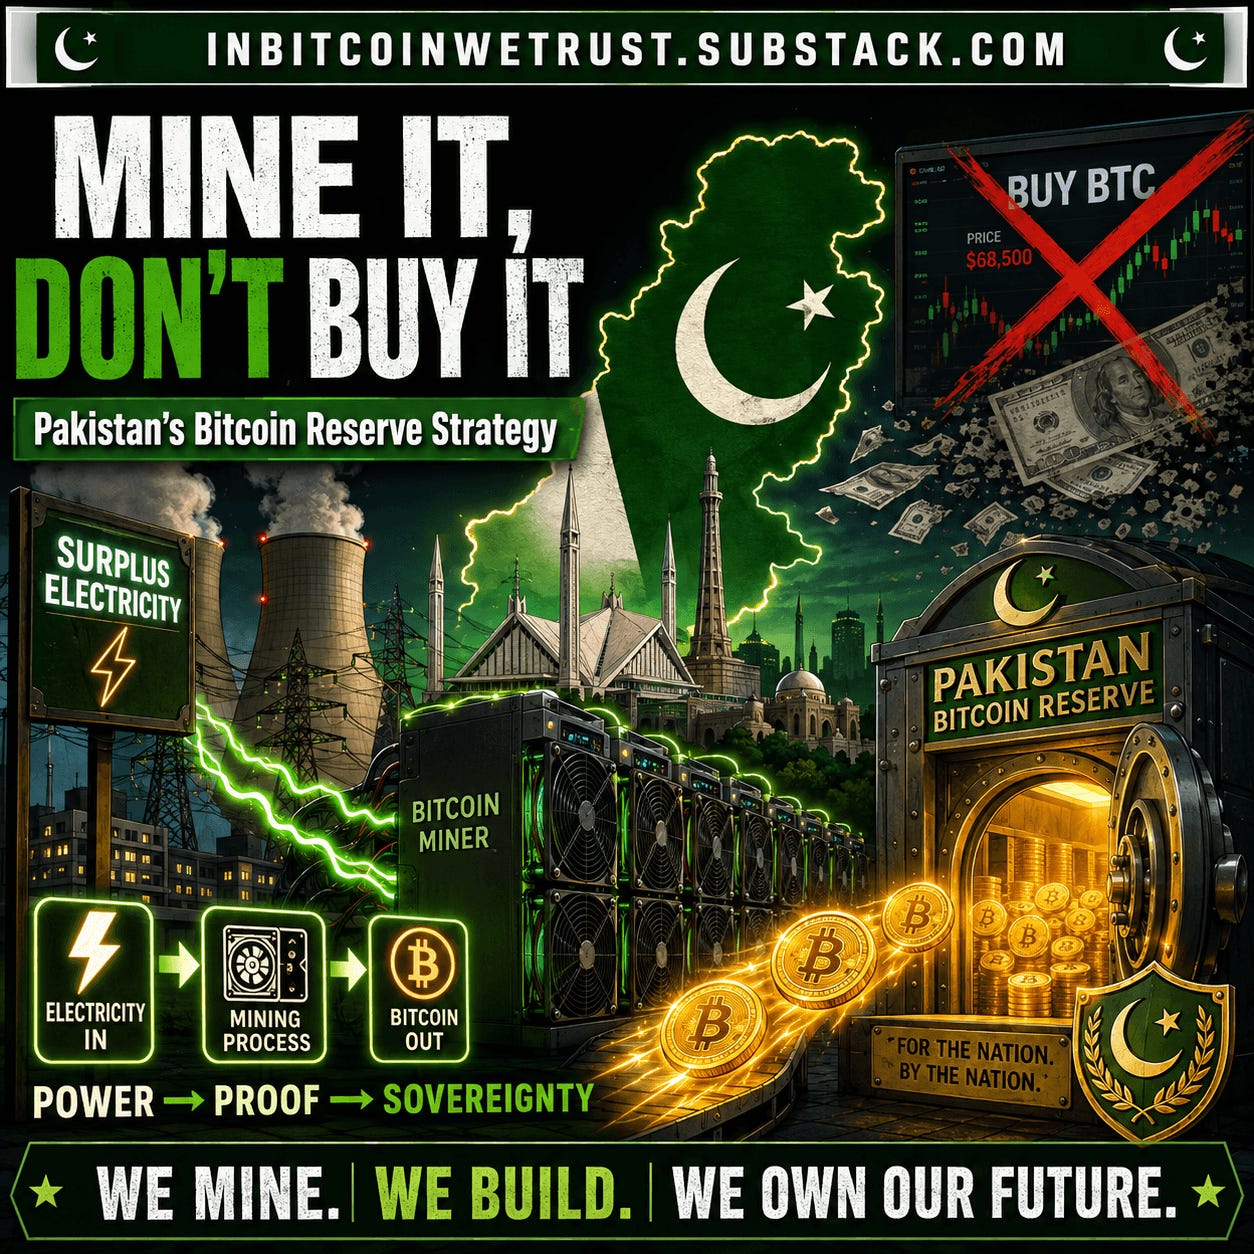
There are two ways for a country to build a Bitcoin reserve.
The obvious way is to buy Bitcoin.
Take dollars. Enter the market. Acquire BTC. Put it on the sovereign balance sheet.
Simple.
Unless you are Pakistan.
Pakistan does not have the luxury of treating dollars as an unlimited resource.
The country is operating under a $7 billion IMF program, rebuilding foreign-exchange reserves, struggling with chronic trade deficits, managing a deeply distorted electricity sector, and trying to convince international investors that its finances are stabilizing.
Spending scarce dollars to speculate on Bitcoin would be politically explosive. So Pakistan appears to be exploring something much more interesting.
Don’t buy the Bitcoin. Produce it.
The government has announced a Strategic Bitcoin Reserve built around digital assets already held in state custody.
At the same time, it has earmarked 2,000 megawatts of surplus electricity for Bitcoin mining and AI data centers.
Think about what that means.
Pakistan could theoretically convert an awkward domestic problem — electricity that cannot easily be monetized — into an internationally liquid monetary asset.
No dollar purchase. No euro purchase. No foreign bond.
Electricity in. Bitcoin out.
And if that model proves economically viable, Pakistan may accidentally have discovered a Bitcoin playbook far more relevant to emerging economies than El Salvador ever was.
This distinction matters.
When El Salvador adopted Bitcoin, the story was largely about monetary rebellion.
Bitcoin as legal tender. Bitcoin bonds. Bitcoin City.
A direct challenge to conventional thinking about national currency.
Pakistan is playing a different game. Pakistan has not made Bitcoin legal tender.
There is no verified public figure showing a large sovereign BTC position already sitting in a Pakistani national wallet. And serious legal questions remain around the entire initiative.
What Pakistan has announced is a government-led Strategic Bitcoin Reserve intended to hold digital assets already in state custody, alongside plans to use surplus electricity for Bitcoin mining.
That difference makes the experiment more interesting, not less. Because Pakistan isn’t trying to replace the rupee.
It is asking something far more pragmatic:
Can Bitcoin turn resources Pakistan already possesses into a reserve asset Pakistan otherwise struggles to accumulate?
That is a question dozens of developing countries could eventually ask.
Pakistan’s electricity system is strange.
The country can suffer power shortages while simultaneously carrying surplus generation capacity.
That sounds contradictory. It isn’t.
Pakistan has spent years adding power generation through contracts with independent power producers.
Many of those agreements contain capacity-payment obligations.
Pakistan can therefore owe generators money for available capacity even when the grid cannot economically deliver or consume all of it.
Transmission constraints matter.
Demand patterns matter.
Industrial electricity prices matter.
Circular debt matters.
Fuel prices matter.
Grid inefficiency matters.
So the question isn’t simply:
Does Pakistan have electricity?The better question is:
Does Pakistan have electricity that can be sold profitably where and when it is generated?
Those are very different things.
Pakistan’s own Finance Division framed the 2,000 MW initiative as an attempt to monetize surplus electricity, attract foreign capital and turn unused capacity into productive economic activity.
And Bitcoin miners have one unusual property.
They don’t need the electricity to come to them. They can go to the electricity.
A steel mill needs infrastructure.
Workers. Supply chains. Transport. Customers. Raw materials.
A data-intensive financial center needs low-latency connectivity. A conventional factory needs access to its market.
Bitcoin mining needs three basic things:
Machines.
Internet connectivity.
Electricity.
That’s why Bitcoin miners have appeared beside hydroelectric dams.
Natural-gas fields. Wind farms. Solar projects. Remote grids.
Places where energy exists but economic demand does not.
Bitcoin mining effectively places a global buyer of electricity anywhere an internet connection can reach. That global buyer pays in Bitcoin.
For Pakistan, this creates a fascinating possibility.
Instead of trying to move surplus electricity across inadequate infrastructure… you move computation to the electricity. Then export the result digitally.
There is no shipping container full of energy.
No new transmission line crossing a continent. No tanker. No pipeline.
The export leaves as Bitcoin.
Suppose Pakistan possesses electricity that would otherwise earn very little.
The government could sell that electricity cheaply to miners. Or operate sovereign mining infrastructure. Or structure public-private mining partnerships.
Those miners convert electricity into hashrate.
Hashrate competes for Bitcoin’s block subsidy and transaction fees.
Successful mining produces BTC. And BTC can be stored globally with no physical export infrastructure.
In economic terms:
stranded domestic energy → computational work → globally liquid digital property.
That conversion is why Bitcoin mining has always been more interesting than the lazy description: “Computers wasting electricity guessing numbers.”
The miner is purchasing energy in one market and selling mathematically provable scarcity into another.
At national scale, that starts looking less like a tech business. And more like an energy-export strategy.
Now we arrive at the part I think most people are missing.
Pakistan does not have unlimited foreign currency.
Its trade deficit recently reached roughly $39.5 billion, while the government remains focused on rebuilding reserves and reducing dependence on external financing.
Imagine Islamabad wanted to accumulate $1 billion of Bitcoin conventionally.
Where does the $1 billion come from?
Dollars.
Those dollars could otherwise:
pay for imported fuel.
service foreign debt.
buy machinery.
finance essential imports.
support the rupee.
strengthen foreign-exchange reserves.
Every BTC purchase would therefore carry an obvious opportunity cost.
Now change the mechanism.
Instead of:
$1 billion USD → Bitcoinyou attempt:
domestic surplus electricity → Bitcoin
The foreign-exchange arithmetic changes.
Pakistan isn’t exporting dollars. It is monetizing a domestic input. That is the real attraction.
And this is where the story becomes much more complicated.
Pakistan’s plan initially included proposals for preferential electricity pricing to attract mining and other energy-intensive industries.
The IMF pushed back.
Why?
Because cheap energy isn’t really “free” energy.
If the government offers miners electricity below an economically justified rate, somebody absorbs the difference.
Taxpayers.
Utilities.
Other electricity consumers.
The government.
Or the already stressed power system.
Reports in 2025 said the IMF rejected the proposed subsidized electricity tariff, citing concerns about market distortion and fiscal risks.
That objection is perfectly rational.
If Pakistan loses $100 of economic value supplying electricity to mine $80 of Bitcoin, calling the electricity “surplus” doesn’t magically make the strategy profitable.
Bitcoin does not repeal economics.
This is the central question.
Not:
Can Pakistan mine Bitcoin?Obviously it can.
The question is:
At what true all-in energy cost?
Whenever a government says “surplus electricity,” be careful.
Surplus at what hour?
At what node?
At what marginal cost?
With what transmission constraints?
Under which contractual obligations?
Generated from what fuel?
Could the same electricity be used more productively somewhere else?
Could industrial tariffs simply be reduced?
Could grid losses be fixed instead?
Could transmission infrastructure unlock conventional economic demand?
An independent Pakistani energy-policy analysis warned that the mining plan needs to be evaluated against grid instability, high electricity costs and weak transmission infrastructure rather than assuming all surplus generation represents economically free power.
That’s the right skepticism.
The Bitcoin thesis is strongest when mining consumes genuinely stranded or curtailed energy. It becomes much weaker when governments manufacture cheap electricity through subsidies.
It actually clarifies it.
**Pakistan doesn’t need subsidized mining. **It needs profitable mining.
Those are not the same thing.
The sophisticated model would be dynamic.
Miners consume electricity when the grid has excess capacity. They curtail when electricity is scarce. They locate beside generation assets where transmission is constrained. They absorb supply that otherwise struggles to find buyers. They potentially provide a guaranteed floor buyer for certain power producers.
In that system, Bitcoin mining doesn’t compete aggressively with households for electricity. It competes for electricity that has weak alternative demand.
That is a much stronger model.
And one that the IMF would find harder to dismiss purely as fiscal waste if the numbers actually work.
Mining isn’t the only route.
Pakistan has said its national Bitcoin reserve would initially contain digital assets already held in government custody.
This mirrors an important development in the United States.
Governments already seize digital assets through criminal enforcement.
Historically, those assets have typically been auctioned or sold.
The emerging Bitcoin-reserve thesis says:
Why sell them?
If the government already owns forfeited Bitcoin, selling it simply converts a scarce asset into fiat currency.
Keeping it requires no new taxpayer-funded Bitcoin purchase.
That’s politically easier.
**It also creates a starting balance. **Then mining provides a possible accumulation mechanism.
So the emerging Pakistani model becomes:
**Seized Bitcoin seeds the reserve.**Domestic electricity grows the reserve.
That is fundamentally different from announcing a giant sovereign-market purchase.
This is where the story becomes much bigger than Pakistan.