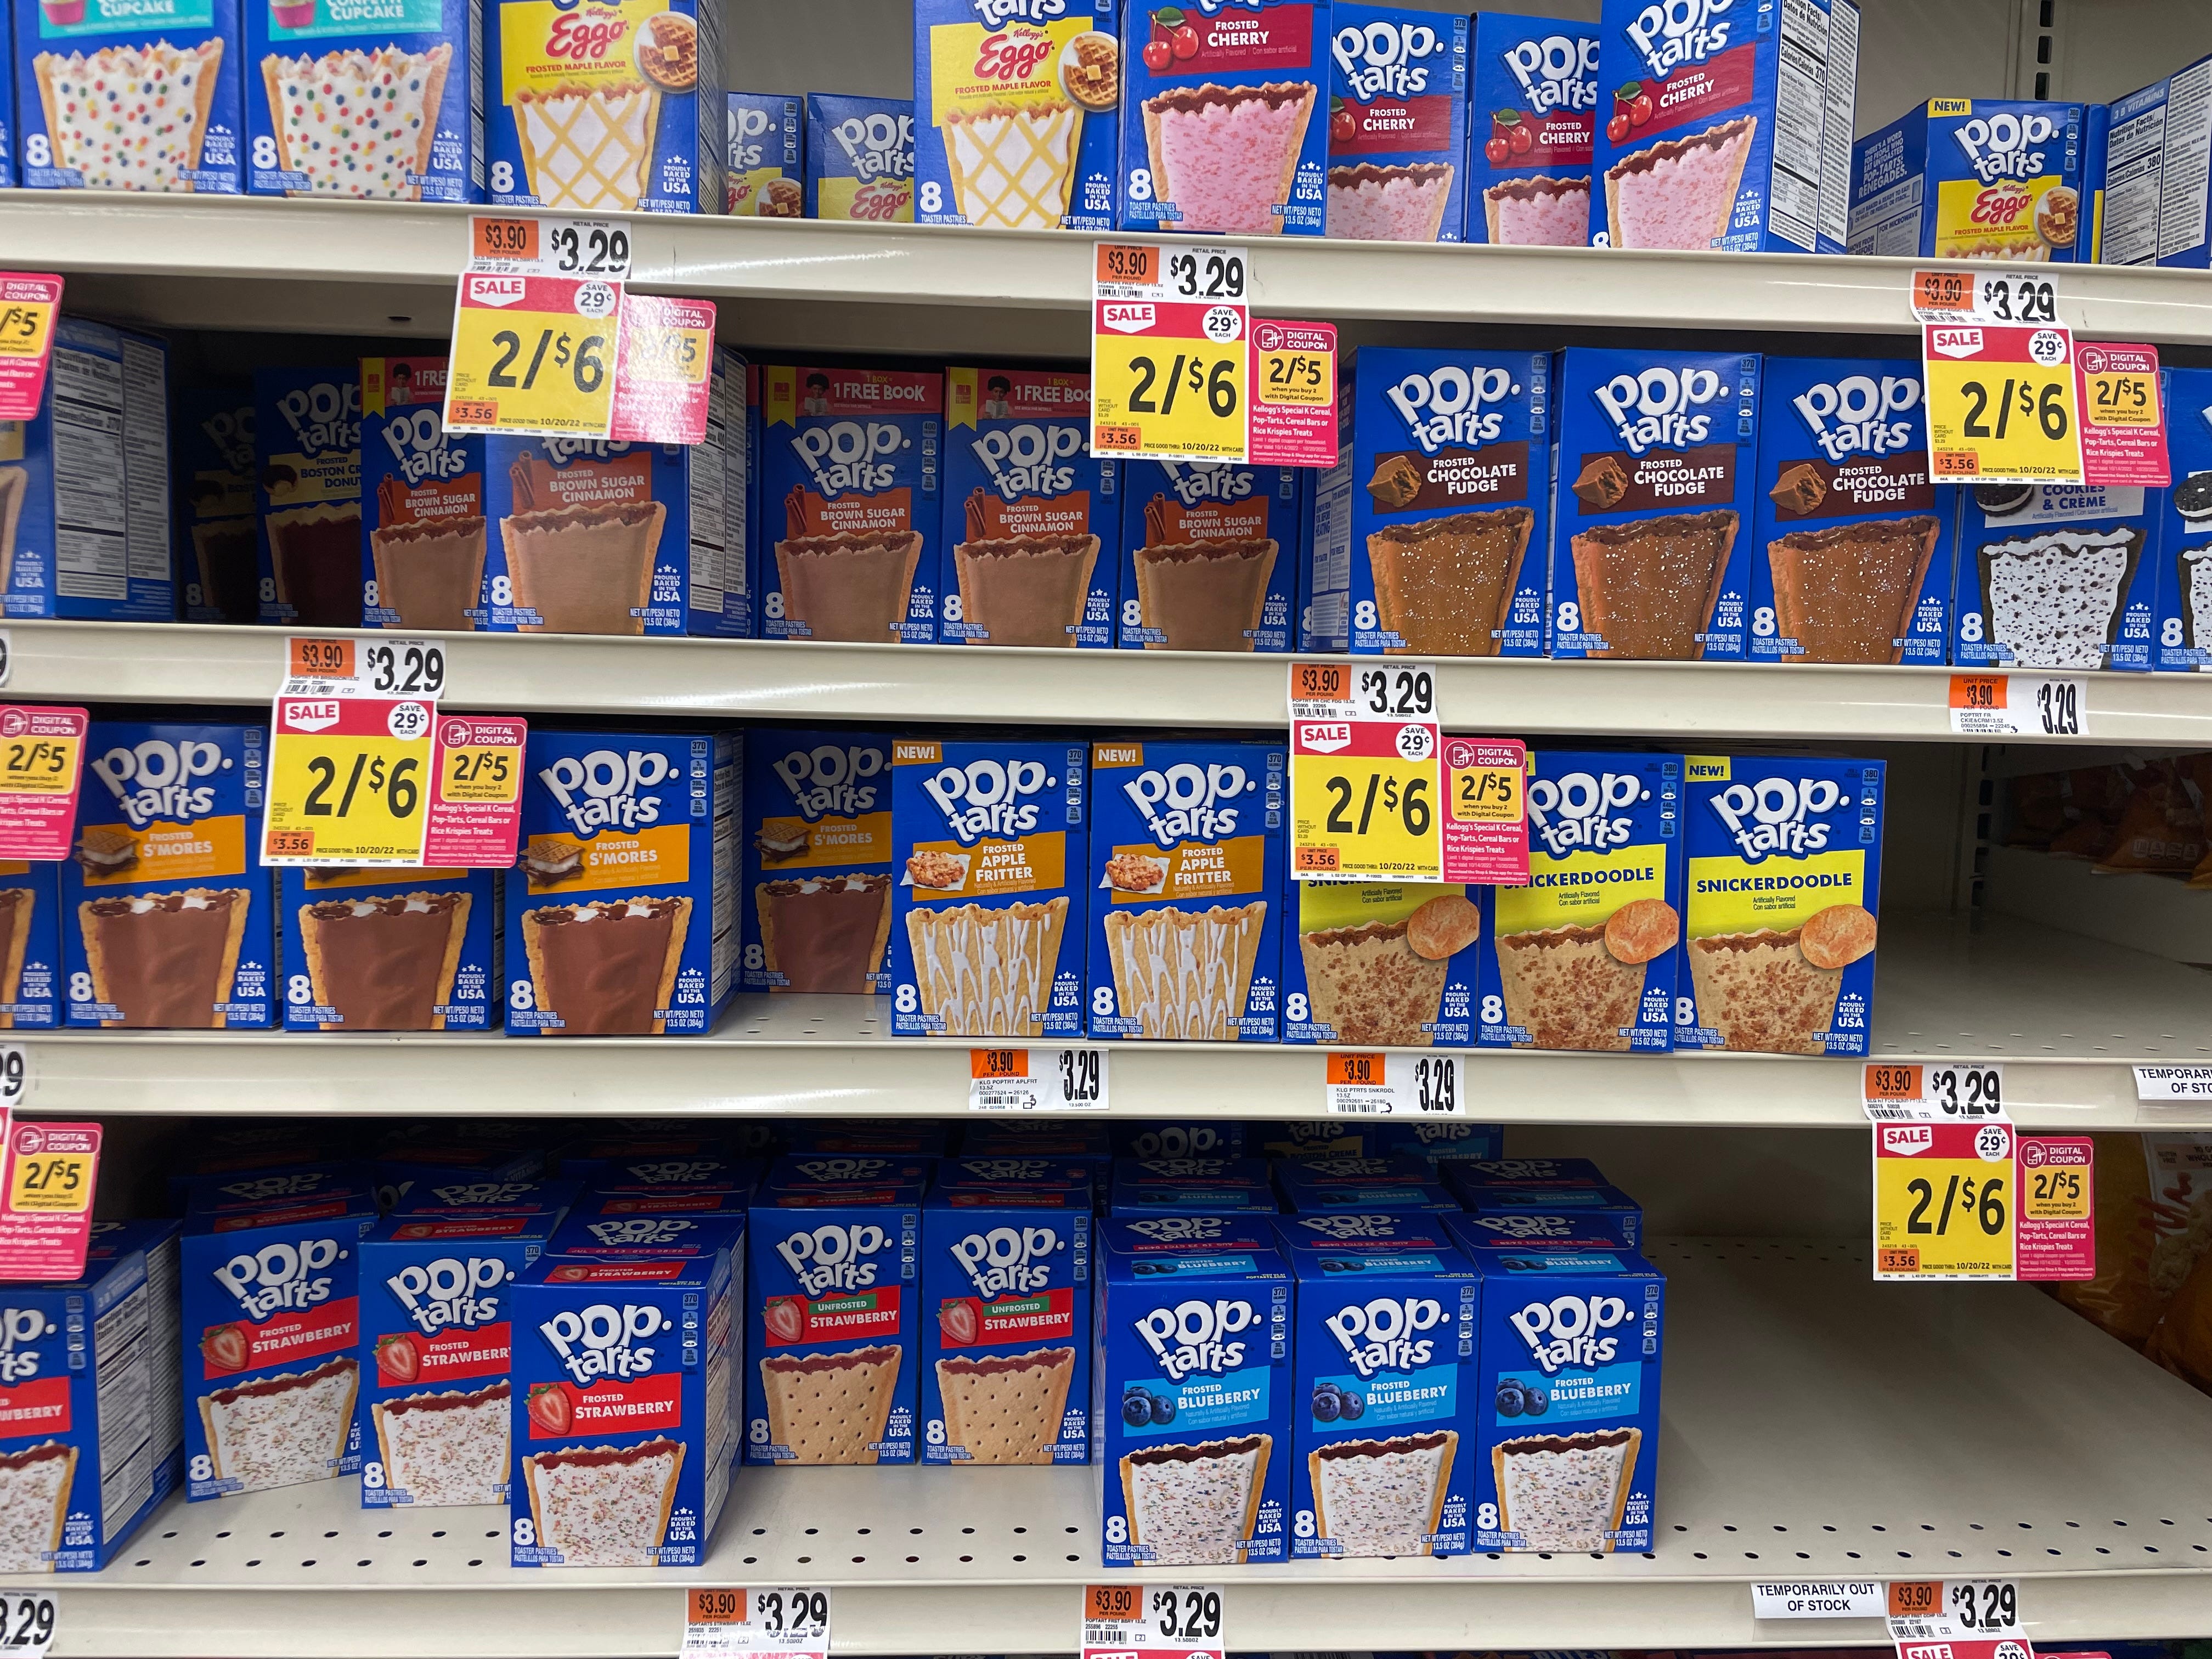
“First rule of understanding: Admit you don’t.” Richard FeynmanGresham’s Law is an economic principle stating that “bad money drives out good”. Let’s use the poetic license granted to us by Substack and apply it to…reality. Look at supermarket aisles. Now, I like a good Pop-Tart as much as ( fine, more than) the next guy, but do we need so many options? And dont get me started on 47 flavors of Ritz Crackers!
Now, I am used to trying ( the key word here!) to assimilate a tsunami of information on the desk; I had 9 screens at JPM, and here is my latest setup — but even I can’t deal with the onslaught of stories, news, rumors, misinformation, and verbal warfare going on right now. My consumption resembles a Sine wave, with periodic peaks and valleys. Sadly, for my peace of mind, I’m at peak consumption right now, and, man, things are messed up.
We have:
An economy with percolating inflation, little job growth, and low home sales,
A low-intensity war continuing to drain resources and American influence with huge downside risk of kinetic conflagration at any moment- with no winning exit ramp in sight for the U.S.,
Climate issues increasing:
Europe is having its hottest summer on record, beating last year, which beat the year before,
An imminent El Niño, which analysts think will be the worst on record with 90% certainty, will impact agricultural production at a time when approximately 30% of global fertilizer supplies are still stranded in the Strait of Hormuz.
Increasing radicalization of the American body politic on both ends of the spectrum, heading into a midterm election season with potentially massive ramifications for the domestic situation—will there be interference? Will there be the widely-expected blue wave, and what does that mean for 2027-2028? Does the center reassert itself, or do we continue down the road to DSA and MAGA being the dominant two forces in their respective parties?
A President who seems more concerned with his legacy than with dealing with the issues; according to Maggie Hberman of the NY Times, he spends 75% of his time focusing on issues such monuments and names on buildings.
Hopefully, my personal sine wave frequency increases, and I stop perseverating on this. Thankfully, it’s still summer, so I can find distractions like chasing small white balls around beautiful fields of green marked by spectacular vistas.
Worth a read
‘The Yen and the US Treasury’s Tightrope Walk’
(Spyros Andreopoulos)‘Inflation
( Simon Hunt)‘Carry Unwind?’
(Oracle)
Three soft prints in five sessions and the front end believed every one of them. Two-year to 4.15 by Thursday. Records on the S&P. And then Friday, on the weakest print of the three, the thirty-year closed at its high for the week and 2s30s finished eight basis points wider than it started.
A disinflation week that bear-steepened. The equity market is trading the Fed. The long end is trading who buys the paper, and those are no longer the same instrument.
I am underweight utilities into a 5.25% thirty-year, short the long end, and the only thing that scares me is a dovish Jackson Hole taking both legs down together.
“What we’ve got here is failure to communicate.”
The data communicated. Consumer price index in line at 3.4%. Producer prices flat. Retail sales the softest in over a year. Three separate messages, all saying the same thing, all sent to a bond market that took delivery on the front end and refused it on the long.
Look at what actually happened Friday. The weakest of the three prints lands at 08:30. The two-year, which had run all the way down to 4.15 on Thursday, backs up two basis points. The ten-year rises five. The thirty-year closes at 5.25%, its high for the week. Soft data, steeper curve, higher long yields.
Not how the story is supposed to go.
Every wire this week wrote the same note: inflation cooled, September is a hold, risk on. Fine, as far as it goes, and the tape cooperated. Third consecutive weekly gain, longest streak since May, a record intraday at 7,816.70 on Wednesday.
But underneath the celebration, the long end spent five sessions doing the opposite of what a disinflation should produce. Thirty-year up six on the week. 2s30s out eight to 108. And it widened
moston the day the consumer looked worst.The market that matters was not pricing inflation this week. It was pricing absorption ... who takes down the paper, at what yield, and whether anyone official still wants it. Different questions, different answers, and only one of them showed up in the equity close.
Five sessions, one divergence.
Small caps led. Tech lagged. In a week the crowd filed under ‘AI melt-up’, the AI index was the worst of the three. Hold that thought.
Read the front end and the long end as two separate votes. The front end voted with the data: two-year down two on the week, and it bottomed at 4.15 Thursday after the producer print. The long end voted against it: thirty-year up six, closing at the week’s high.
When the two ends of the same curve disagree by eight basis points in slope over a week, with no supply surprise and no Fed meeting, the disagreement is the information.
CROSS-ASSET.
Dollar index 99.67, up marginally. Dollar-yen 159.32, up 0.99% and back near the level that triggered the intervention in the first place.
Brent 88.52, up 5.95%. Gold 4,376, up 0.80%. Henry Hub 2.79, up 8.98% and the biggest percentage move on the board.
Investment-grade and high-yield spreads each widened by two basis points, which, in a week this long, is a rounding error and worth saying plainly: credit did not participate in any of this.
VIX 14.25, lowest close since 29 December, seventeen percent below its own fifty-day. Weekly closing range 14.25 to 15.46.
THE CALL. Term premium leads from here, and the front end follows it rather than the other way round. I expect 2s30s to widen again next week, and the thirty-year to be above 5.25% before it is below 5.10%. The equity index can grind higher inside that and probably will, which is exactly what makes it dangerous: the bid is coming from a rate cut that the long end has already declined to price.
I’M WRONG IF. Thirty-year closes below 5.10% for three consecutive sessions. That kills it outright. A single soft close does not.
SHOCK TEST. The book’s exposure is Jackson Hole on the 20th, with July minutes carrying three hike dissents landing the day before. A genuinely dovish Warsh compresses the curve and takes both my rate legs down at once. Single event. I own it.
The prior edition named its falsifier precisely: a hot consumer price print on 12 August, on the argument that a hot number into a contracting labor market was the stagflation combination and would kill the cut-path pillar under the equity melt-up.
It did not print hot. 3.4%, in line with producer prices flat behind it. The falsifier did not trigger; the pillar held; the melt-up continued to a record. Call stands.
Sector of the week was technology, selectively long, monetization over promise. To be honest: the dispersion worked and the direction did not. SMIC rose as much as 6.4% on a beat with a stronger margin outlook while JD.com fell more than ten percent on a revenue miss. Cisco drew eleven price target raises out of thirteen revisions. The monetization-versus-promise line held everywhere you looked. And the Nasdaq Composite still put in +0.14% against the Russell’s +1.12%, which means the sector call was right about the mechanism and wrong about the beta. A selectively long tech book underperformed a blindly long small-cap one. Call it a loss. Dressing the dispersion up as a win would be the easy thing to do here.
The Hormuz shock test from that edition is the one that aged best. It warned that near ten vessels a day of traffic normalization was a rounding error and that a single confirmed disruption re-arms Brent. Attacks resumed, talks stalled, Brent added 5.95%. It did not clear 95, so the test fired at partial strength.
**INTEL AND AMD, in the same week.**Intel sold $15 billion of stock, reportedly its first public share sale since the 1971 listing. AMD raised $4.75 billion in its largest ever dollar bond, four tranches out to ten years, the long end pricing at ninety over and tightening roughly twenty-five basis points from talk. So what? Two of the largest AI-adjacent capital raises of the cycle landed in the same five sessions that the thirty-year sold off six basis points. The AI buildout is being funded at the long end of a curve that is steepening away from it. Nobody has connected those two facts yet because they file under different desks.**JANE STREET LOST ROUGHLY $15 BILLION IN JULY.**First down month in about a decade, driven by volatility in an AI-focused fund it had backed. So what? When the firms that make the market start showing AI exposure in their own monthly P&L, the trade has moved from a position people own to a position embedded in the plumbing of who prices everything else. Different risk shape entirely. It does not need the AI thesis to be wrong. It only needs the AI thesis to be volatile.**BALLY’S FILED A GOING CONCERN WARNING.**Friday, seeking funding alternatives against the risk of breaching liquidity and leverage covenants. So what? High yield spreads moved two basis points all week. Either this is a genuine idiosyncratic accident inside a healthy market, or it is the first name to show what a 5.25% thirty-year does to a leveraged balance sheet with a refinancing wall. I do not know which yet. I do know that credit markets that widen two basis points into a week like this one are not doing much discriminating.
**FINANCIALS.**The sector fell 0.1% Friday, and the internals matter more than the level. Life insurers reinvest into the long end.
Property and casualty reinvests into the belly. 2s30s widened eight basis points this week, so the reinvestment spread moved decisively in one direction, and the tape has been paying it.
Capital markets remain a disappointment: the take-private cluster landed the week before, and the subsector declined into its own catalyst. Elsewhere, Bank of America committed $250 billion to critical infrastructure across data centers, renewables, storage, gas and minerals, which is the same term-premium-funded capex story wearing a bank’s jacket.
Investment grade issuance was $72.3 billion, down ten percent week over week; high yield rose to $11.3 billion.
Positioning: own life over property and casualty, stay flat capital markets until it earns a re-look.
**ENERGY.**Brent 88.52, up 5.95%, and the sector was Friday’s best performer. Every bullish argument runs through Hormuz staying shut, and the shipping data supports it: attacks on two vessels Thursday, another Friday, a bulk carrier hit Saturday morning. But look at what the producers are doing rather than what the price is doing. Chevron, ConocoPhillips and Occidental cut Lower 48 capex by ten to twenty percent in the first half, at elevated prices, choosing shareholder returns over volume. Companies do not behave that way when they believe in a durable supply shock. Meanwhile natural gas ran 8.98% into a winter that a strong El Nino composite says should be warmer across the population-weighted northern tier.**Positioning: long the crude complex, and I would fade the gas move rather than chase it.****TECHNOLOGY.**Semis slipped 0.3% Friday, the composite managed +0.14% on the week, and the dispersion inside was violent. CoreWeave doubled revenue to $2.58 billion. Nebius put up 514% growth in AI cloud. SMIC beat on margins. JD.com missed and dropped double digits. Nvidia reports next week against a projected three to four billion dollar beat and guidance north of $107 billion.**Positioning: the monetization screen still works as a stock-picking tool and has stopped working as a sector call. Neutral the sector, keep the screen.****COMMUNICATION SERVICES.**Berkshire added to Alphabet, now its third largest holding. What this earnings season actually showed, and one wire made it explicit, is that a meaningful slice of megacap earnings growth came from revaluing investment stakes rather than from operations. Alphabet’s holdings did work. Real gain, yes. Operating gain, no. A market paying an operating multiple for the first is making a category error.**Positioning: neutral, and check what you are actually paying for.****CONSUMER DISCRETIONARY.**July retail sales fell across all measures, the worst in more than a year. Michigan preliminary sentiment fell to 51 from 55.2, below the 55 estimate, with one-year inflation expectations rising to 4.3%. Dillard’s beat on earnings and fell 7.3%, because the beat leaned on tariff refunds. Walmart, Target and TJX report next week.**Positioning: underweight, and the off-price names are the only place I would be long inside it.****CONSUMER STAPLES.**No dispersion story this week worth your time. The group did nothing while the consumer data deteriorated around it, which is itself mildly informative and not enough to trade.**Positioning: neutral.****HEALTH CARE.**Led the S&P lower Friday. A bipartisan Senate group unveiled 340B legislation aimed at the discount program that sets drugmakers against hospitals, which is the sort of thing that sits dormant for months and then reprices two subsectors in a session.**Positioning: neutral, watch the bill.****INDUSTRIALS.**The AI data center buildout has broadened into the unglamorous supply chain, paint and bearings and the rest. Against that, European industrials drew the most analyst downgrades on the continent this week. Same theme, two continents, opposite flows.**Positioning: long US industrial exposure to the buildout, avoid the European complex.****MATERIALS.**Thin week. The food and fertilizer channel is where this sector gets interesting over the next two quarters, and it is a next-quarter story rather than a this-week one.**Positioning: neutral, revisit on the September climate update.****UTILITIES.**The apex read of the week, in full below.**Positioning: underweight, and the AI load story is not the reason to own it.****REAL ESTATE.**The Securities and Exchange Commission exempted a large subset of data center securitizations from key risk retention and disclosure rules. A new debt channel, opening for the single hottest category of physical asset, at the exact moment the long end is repricing. Data center REITs get cheaper financing and a more crowded competitive field in the same stroke. Office and residential remain a rates story and the rates went the wrong way.Positioning: underweight the rate-sensitive REIT complex, and treat the data center exemption as a credit event to watch rather than an equity buy.
UTILITIES. UNDERWEIGHT.
Everyone owns this sector for one reason: AI load growth. Power demand from data centers is real; it is measurable, and it is the best fundamental story the group has had in thirty years. I am not arguing with the demand.
I am arguing about the funding. Utilities are the most capital-intensive, most leveraged, longest-duration cash flows in the index, and they are a bond proxy in a week when the bond they proxy just closed at 5.25% and is rising. The AI load story is a capex story. Capex at the long end. And the long end is the one part of this ma…