‘You will become way less concerned with what other people think of you when you realize how seldom they do.’ David Foster Wallace
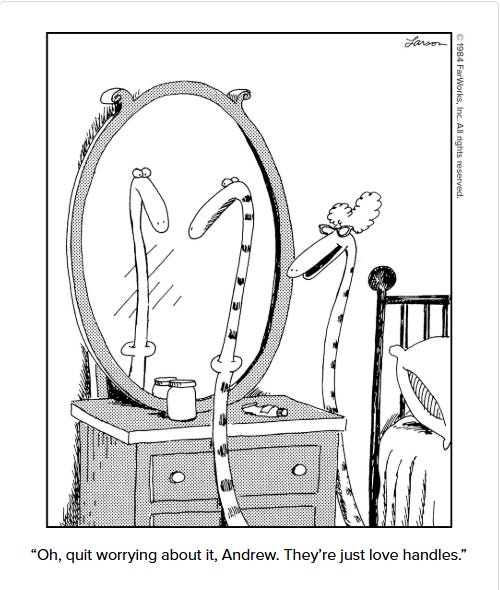
It is amazing to me the amount of attention that gets paid to how public figures live their lives or their personal decisions. We all get caught up with the judgments of others, but it has gone to extremes. Whether Karoline Leavitt decides to be a stay-at-home mom or whether AOC decides to freeze her eggs are personal decisions and shouldn’t be the fodder for rumor mills or judgment. It also shouldn’t be a factor in deciding who we should elect. Sadly, in politics and in our social interactions, we let single issues color our opinions of others. A snake with love handles is still a snake ( yes, I’m torturing the metaphor, but its Friday…)
Last month a catering truck pulled up to Air Force One on the tarmac at Ankara and the President of the United States got into it. Not a figure of speech.
**A catering truck.**Israeli intelligence had flagged a shoulder-fired missile. The Secret Service moved him onto a smaller C-32 and let the big aircraft fly on wearing his name like a decoy duck. Reporters aboard were told to keep the window shades down for the whole flight. Nobody outside the operation knew for a month.
Now read the manifest, because the manifest is the argument. Into the small plane: the Defense Secretary, the President’s personal assistant, the man who runs Oval Office operations, and the man who runs the social media account (yes, his former caddie). Left aboard the aircraft the missile was aimed at: the Secretary of State. The Secretary of the Treasury. Officials could not say with confidence that the Treasury Secretary had even been told (Washington Post, CBS News).
Second and fourth in the line of succession, sitting on the bait. A body man in the safe seat. Every organization carries a stated hierarchy around, and every organization has a real one, and the two are never introduced until something is genuinely at risk. Then the stated one boards the decoy.
Some week for it, too. Four more of the same.
**TWO WOMEN, ONE CLOCK.**Saturday, the congresswoman from the Bronx posted video of herself administering an egg-freezing injection. ‘Don’t be weird about this, even though I know all of you will be.’ She is 36. Her line: ‘a choice that I am making to feel more in control of my life.’ Tuesday, the White House Press Secretary announced she leaves at the end of the month. She is 28, a two-year-old son and a daughter born in May. Her line: ‘I cannot be the best mom my two young children deserve while devoting the constant time, energy, and attention required of the White House Press Secretary.’One bought time. One spent it. Both were told within the hour by strangers that they had done it wrong.
The shouting is not the interesting part. The interesting part is that the shouting got disowned. A commentator went after the timing on geriatric-pregnancy grounds and a senior White House official broke cover to say it out loud: ‘Yes, the Matt Walsh messaging is not helpful.’ A Trump adviser called the whole thing ‘not really a winner for Republicans’ (
Axios).Read that as a political shop eighty-one days from a midterm, looking at its own numbers on women voters, deciding this particular fight does not pay. The label says culture war. The cargo is a poll.
**OVER AT THE KENNEDY CENTER,**despite the court rulings, the board voted this week to put the President’s name back on the building, this time in letters reading ‘Restored and Renovated by President Donald J. Trump.’ He chairs that board. His appointees elected him to chair it. Somewhere there is a man ordering signage for a building he has voted himself the right to name, and I promise you the signage will outlast the appropriation.**THE MIDDLE, ALLEGEDLY.**Every write-up this summer says the Democrats are moving to the center. Forty-seven percent of primary voters told the Times they want exactly that, against 28 who want it left. Gallup has 45 for moderation against 29 for more liberal.
Then they voted. Inside three weeks a democratic socialist took the Michigan Senate nomination off a centrist congresswoman, another ousted a sitting member, and a progressive took the Kansas gubernatorial primary off the governor’s own pick. Same fortnight, opposite direction: a centrist walked the Michigan governor’s race, a moderate took a Virginia swing seat, and Cori Bush lost by 22.
A survey measures a mood. A ballot measures a candidate. When the two disagree this loudly the survey is the label and the ballot is the cargo, and anybody building a November thesis off the polling is reading the fuselage.
**EIGHTY-ONE DAYS.**Then the part nobody has priced at all.Eighty-one to the election. Thirty more for counting and litigation. Then, on 3 January 2027, a room full of people who have just been elected to the House of Representatives, a Clerk with a list, no Speaker, no rules, and no way to make any of it until they vote. Which they cannot do until they are seated. Which the chamber decides. By majority. Of the members already seated.
Article I, Section 5. Each House judges the elections and returns of its own members. Not the courts. The chamber. Dead letter for a century, because the margins were never thin enough to make it worth using, and this is the first cycle in a very long time where three seats plausibly decide who holds the gavel.
The continuing resolution funds the government to 11 December. Inside the certification window, before the new Congress sits. A lame-duck House that believes it lost has to fund the state whilst its successor is being litigated.
Now go and look at the volatility surface for any of those dates.
Everybody on the street has a view on who wins, and I cannot find anyone with a position on the question simply not getting answered.There is no kink. January 2027 trades like an ordinary Tuesday.
Which is the only thing worth asking about a tape that closed at a record last night with the volatility index at 14.5 and private client cash allocation at nine percent, the lowest reading in the twenty-one-year series.
What does the label say, and what is actually in the hold?
**The long end refused, twice.**The 2-year gave up 10bp this week, the 30-year gave up 4. 2s30s out to 106. I am short the long end and not trimming.**Financials are arguing with my rates book.**A 447bp gap Thursday between mortgage names and banks. Somebody is buying a bull flattener inside the sector while I am short one in rates.**Capital markets failed its own catalyst.**The take-private wave landed and the subsector fell 1.1 percent. Standing down. No add.**08:30 settles today. November settles the quarter.**Hot and I add duration. Soft through 4.60 and holding and I cut. Separately: the vol surface prices zero risk that January’s House fails to seat itself.
TL;DR
Two cool prints, and the long end still would not come. The 2-year gave up 10bp this week, the 30-year gave up 4, and the spread between them widened six. Front-end disinflation, back-end refusal, and a curve that has not steepened between 2s and 10s in five sessions. I am carrying the long-end short at held size, no add, with the 10-year three basis points above the trim gate and this morning’s retail sales the two-sided catalyst. Inside financials the tape is arguing with me: mortgage names and exchanges led, banks and capital markets lagged, and the dispersion inside the sector ran 400bp over two sessions. I am expressing the sleeve intra-sector rather than long the group. Gold fell 1.5 percent yesterday and the rotation story attached to it does not survive the print, so the metal leg gets re-underwritten at the mark and not at the narrative. Positioning is the loudest thing in the room. Private client cash at nine percent, equity allocation at 66, the largest weekly private client equity inflow since September 2022, and a volatility index fifteen percent below its own fifty-day into Iran measures, the minutes and Jackson Hole. The hedge stays on.
Start with the only chart that matters this week, and it is not an equity chart.
The 2-year has been running below and around the policy rate for the better part of a year. A market that has priced the cut, priced the pause, priced the whole soft-landing catechism. Fine. Nobody argues with the front end.
The argument is at the back.
Here is the week, and it is four numbers.
Two cool inflation readings inside one week. Hike odds under 35 percent. And the long bond gave up four basis points. Forty percent of what the 2-year gave up, on the friendliest inflation news of the quarter.
No bond market that believed the whole story trades like that. Call it a market that believes the inflation story and refuses the supply story.
And 2s10s? Forty-seven, forty-eight, forty-eight, forty-eight. Pinned. All week. The curve did not steepen into the good news, it translated downward and hinged at the long end. If you want the cleanest statement of the regime I can give you, it is that the entire disinflation rally happened inside seven years and stopped.
WHY. Because the supply is not a forecast, it is an invoice.
Four hundred and thirty-two billion dollars of deficit in thirty-one days. Customs duties printed at negative nine billion, a line item I have read four times and still find remarkable. And underneath it:
Net interest at roughly 1,247 billion, annualized against defense at 1,198. The crossing already happened. Everyone has seen this chart and almost nobody has changed a position because of it, which is the usual fate of a slow fact in a fast market.
The Treasury sold thirty-year paper on Thursday at 5.22 percent. Highest auction yield since August 2001 (FT). After the 2001 auction they suspended the thirty-year for the better part of five years. I am not predicting that. I note that the last time the long bond cleared here, the issuer responded by stopping its issuance.
So the regime call, stated plainly and with its own throat exposed:
Term premium is the surviving leg. Not because growth is bad. Because the borrower is large and the buyer is ..tired.
And that last word is doing real work. Look at who owns this market now. **Hedge fund holdings of Treasuries doubled between 2023 and 2025 and now run about 8.5 percent of the whole thing, which puts levered fast money ahead of Japan, China and Saudi Arabia combined ( FT). **Most of it financed overnight. A market that used to be a byword for dependability is now underwritten by the flightiest capital in the system, on repo.
Ask what happens to a 5.2 percent long bond when the marginal holder gets a margin call. Then ask what the volatility index is charging you for that question this morning. Fourteen and a half.
CONFIDENCE. High on the direction of the term-premium call, because it has now survived two consecutive cool prints without flinching. Moderate on the runway, because the 10-year at 4.63 sits three basis points from the level where my own trim fires. Thin margin. I am not going to pretend otherwise.
I’M WRONG IF. A retail sales print soft enough to break the 10-year below 4.60 and hold it three sessions, followed by a dovish Jackson Hole. A real path, maybe a third of the distribution, and it takes down the duration short and the insurer together. I have said so in the book below rather than burying it.
**08:30. Retail sales, July.**Consensus around +0.1 percent headline, +0.2 ex-autos, +0.3 control. The whole session turns on it. Hot re-cheapens the long end and I add to duration. Soft and the 10-year breaks 4.60 and the clock starts on my trim.**10:00. Michigan preliminary.**Sentiment consensus 55.0. The number I actually care about is the 5-to-10-year inflation expectation at 3.3 percent. An upside surprise there does more damage to the dovish case than a hot retail print, because it is the one series the Fed has said out loud it treats as a regime variable.**Next week. The Iran squeeze arrives.**The Treasury Secretary went on television Thursday and promised measures “like have never been seen in the history of economic isolation on a country,” to land next week, paired with the continued blockade of Iranian ports (Bloomberg). The same week the President told Axios he is “low-keying it” with Iran.Both statements cannot be operative. One of them is for the market and one of them is for Tehran, and I would not want to guess which, but I would note that the man promising unprecedented measures is the same man who was left on the decoy plane. Make of the internal coordination what you will.
Brent sits near 88 with the strait effectively shut for six months and supertankers now going dark for extended stretches to transit it. Oil up more than 40 percent year to date. Gasoline above four dollars, the latest into a summer in more than two decades of the motoring association’s data (Bloomberg).
**The calendar past November, which is where the free option is.**Eighty-one days to the vote, then a certification window that contains the 11 December funding deadline, then a House that has to seat itself on 3 January before it can elect anyone or pass anything. Three seats plausibly decide the gavel and the chamber judges its own returns by simple majority.I am not forecasting disarray. I am pointing out that the distribution has a fat left tail, the surface does not price, and that the cheapest expression of it is simply owning convexity past the events rather than trading the outcome. Everyone is positioned to win. Nobody is positioned for no answer.
Confidence that the market is charging roughly nothing for it: high. Confidence the scenario happens: low, call it fifteen to twenty percent, and I would not put on a directional trade at those odds. Convexity is a different question from a forecast.
The dollar is at a decision point and nobody is talking about it.
99.66 spot, the 50-week at 99.04 and the 200-week at 102.45 overhead. Price is coiled inside a multi-year descending wedge with a horizontal shelf underneath it. RSI dead neutral at 49.7. Least interesting-looking chart in the pile. Most consequential too, because a dollar break lower with the long end at 5.2 is a different regime entirely from a dollar break higher.
And there is a wrinkle. In the last days of July the Treasury intervened to support the yen, and it did so by selling
eurosrather than dollars (Josiah Waters). Dollar-yen had touched 163.99, weakest since 1986. It sits at 159.09 this morning, below its fifty-day at 161.17.Selling euros to defend the yen is an odd instrument. The conventional tool is selling dollars, and the reason to avoid it is that Japan, the largest foreign holder of Treasuries, has been funding its own currency defense by selling them. You cannot weaken your currency to help theirs while they are liquidating your bonds to help themselves. So you reach for a third currency and hope the connection breaks.
An alternative reading is more generous, and I want to state it because I think it is genuinely arguable: that Washington is deliberately protecting the yen carry trade because roughly 250 billion of direct carry, and perhaps a trillion including derivatives, is the funding mechanism for the AI capital expenditure cycle (
Capital Flows). On that reading the intervention is not desperation, it is plumbing maintenance on the thing the whole equity market is levered to.I do not know which it is. The two readings imply the same position and opposite durations, which is the honest reason I am carrying the tail rather than the view.
Brazil, because somebody should mention it.
Down through the uptrend off the December 2024 low, through the 50-day at 34.99, through the 100 at…