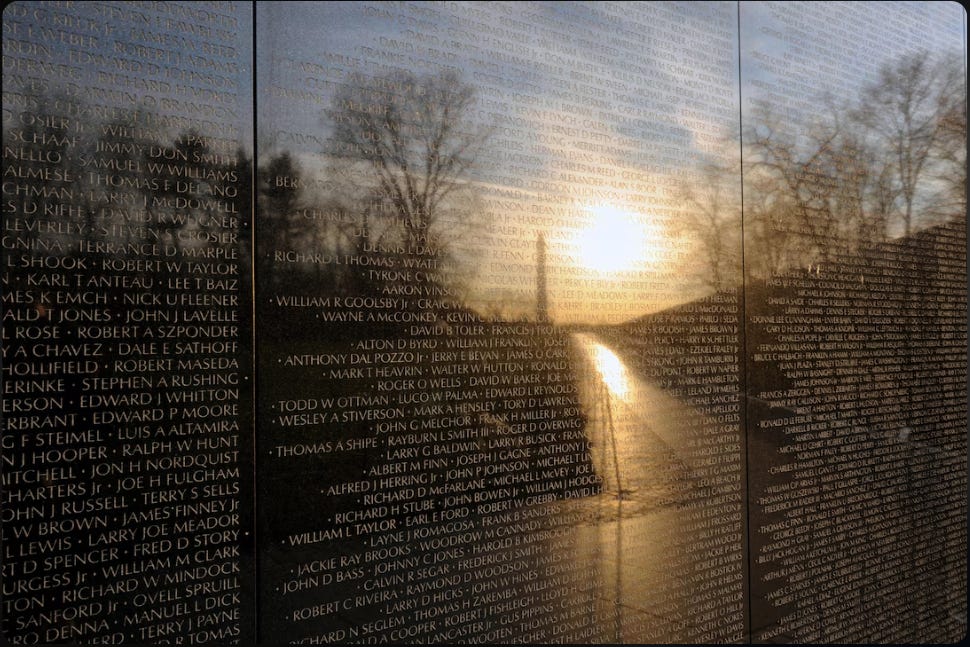
"...to care for him who shall have borne the battle, and for his widow, and his orphan."** Abraham Lincoln, Second Inaugural Address, 1865**
Service. A word with many uses and connotations. Today, it reminds us of perhaps the most important one: doing things for others, for something greater than ourselves.
One of my pet peeves is watching people treat those in the service industry with disrespect. Clerks, food servers, and the like. There, but for the grace of God, go all of us. The sense of superiority and entitlement with which some people treat this cohort disgusts me. If I see you abusing a server, I know we will never be good friends. You just aren’t my kind of person.
That goes exponentially more so for those who choose to serve in the Armed Forces, knowing they may be asked to risk their very lives for the greater good. For the rest of us. So we can play golf, watch movies, and argue about life over a cocktail on the veranda. So our kids can walk to school, have playdates, and grow up to be adults we couldn’t be more proud of.
And yet, we too often take these men and women for granted. Worse, we sometimes treat them with disdain because they served in a conflict or military action with which we disagree. I reject that completely. We can debate the decisions that put our military into harm’s way. We can disagree with the policies and the politicians. But the men and women who serve deserve our respect and gratitude. Those are two entirely different things.
I’m glad we have a specific day set aside to honor them. But they deserve to be honored 24/7, 365 days a year.
Period. Full stop.
Okay, rant over.
**THE FRONT END TOOK DECEMBER.**Core ran hot a third month, and the 2-year carried it. I stay short rate-sensitive equity. I’M WRONG IF Thursday’s reopen puts the 10-year under 4.80% with 2s10s over +40bp.**STOCKS ARE RALLYING WITH THE BOND MARKET AT THE PARADE.**No cash Treasury print backs this morning’s bid. I add no outright longs. I’M WRONG IF the S&P 500 closes over 7,660.**CREDIT STILL WON’T CONFIRM THE SCARE.**High yield tightened on three prints running. I keep the fund short and add nothing to it. I’M WRONG IF the next spread print lands under 326bp.**OIL IS A DIPLOMATIC PRICE.**Tankers are getting hit while Washington talks down combat. I own no oil. I’M WRONG IF Brent settles over $110.
Tuesday’s most important price was set in a market that is shut today, and it stays unrepriced until Thursday morning.
The main argument is that the front end now owns the December meeting, and most of the rate-sensitive shorts on the sheet were written for exactly that. The secondary thesis is the AI funding bill: CoreWeave answered the demand question overnight and left the financing question about where it was (MOVERS takes it apart). Oil hangs off both through the price level, and credit is the one market still declining to go along.
There is no official annual inflation figure for October, because the shutdown killed last October’s survey. Measured from September 2025 instead, prices are up 4.1%; from November, 3.7%. Kevin Warsh would call October ‘information-rich’, and the voters who went to the polls last week were not imagining it.
Food did a lot of the damage. Beef hit a record $6.79 a pound in September, up from $6.32, with the cattle herd at 86.155 million head, the smallest since the 1950s. A steer takes 18 to 22 months to reach market weight, so that line doesn’t get fixed by Christmas, and a headline that stays sticky into 2027 is what the JPMorgan long is written on.
Christopher Waller made the case for 25bp to 50bp in December and said half a point belongs on the table if core printed 0.3% or more. It did. The futures market now puts 89% on a quarter point and 11% on a half, with zero on a hold, and the half-point tail went from nothing to 11% in one session. A December hike reprices JPMorgan’s loans faster than its deposits; it also works against the Bank of America short, which is held and not added to.
The curve flattened from the front. 2s10s narrowed 7bp to +25bp, 5s30s narrowed to +54bp, and the 10-year logged its seventh straight close over 4.80%. The $42 billion 10-year auction landed in the middle of the selloff, and dealers took 10%, the most since May (supply doesn’t reverse on a growth scare).
The real discount rate is the mechanism behind the Realty Income short. A 15-year net lease with escalators near 1% a year is a long bond with a roof on it, and the 5-year real yield closed at 2.56%, a rate that also prices the D.R. Horton short.
THE CASE AGAINST.
Core inflation on a 12-month basis is not running away. Estimated with the geometric-mean method BLS itself suggests for the missing month, headline runs near 4.0% and core near 2.8%. The gap between those two numbers is beef, gasoline and a war, and none of them answers to the funds rate.
On that reading the Fed hikes once into a supply shock, the long end rallies on growth, and the equity bid this morning is right.
Spreads back it: high yield tightened from 348bp to 334bp across three prints while yields rose, and Secretary Rubio said the pressure campaign on Iran works well enough that there is ‘no need for major combat operations any longer.’ Energy is the one input that could roll over by itself.
The two readings are not mutually exclusive; one hike can be both the right reaction and the last one. By Friday’s 4:00 close, two levels tell them apart:
If Thursday’s reopen sends the 10-year back below 4.80% and the curve steepens past +40bp, growth wins and the rate shorts are wrong together.
If the 2-year holds over 4.65% through Friday’s headline PPI and the 10-year trades to 5.05%, the front end keeps the lead and the long end starts to follow.
I put it 60/40 for the front end. I hold the 60 loosely; the instrument that settles it cannot trade until tomorrow.
Today. Stocks open at 9:30 with no cash Treasury market behind them; rate hedging runs through futures only. MBA mortgage applications printed at 7:00, Corteva and Franco-Nevada report after the close, OPEC’s monthly report is due, and the second day of US-brokered Russia and Ukraine talks runs in Abu Dhabi, where Moscow still wants the rest of Donetsk and Kyiv wants the line frozen.
Thursday. Cash Treasuries reopen with initial claims (consensus 194,000) and existing home sales (3.80 million), Cisco and Applied Materials report after the close, and the Treasury sells 30-year bonds at 1:00.
Friday, 8:30. October headline PPI, consensus +0.4% m/m, the second inflation read and the first input that can move the half-point tail.
Iran. The two-day ultimatum Tehran set on Sunday ran out Tuesday evening with no escalation reported by this morning. Mohsen Rezaei, Iran’s security chief, says no talks are under way and that the strait opens when Washington meets seven conditions; Rubio calls them ‘absurd’, reparations included. On Tuesday a tanker was hit by a projectile off Oman, the Revolutionary Guard said another caught fire on a mine in the strait, and an Adnoc vessel was damaged in UAE waters. Treasury Secretary Bessent was reportedly moved to a military base over Iranian threats. None of it reaches the sheet, which holds no energy line and opens one only on a $110 settle.
Washington. The House voted 211 to 204 to send Thomas Massie’s impeachment articles against Pete Hegseth to the Judiciary Committee, which kills a floor vote for now. House Republicans picked Jim Jordan as minority leader, 106 to 73, and Senate Republicans kept John Thune. Democrats take both chambers on 3 January with roughly 254 House seats.
Eleven of eleven midterms that handed Democrats Congress saw the S&P higher six months later, by 16.5% on average. That base rate is the best argument against keeping the equity-beta block in place, and the block stays anyway until the index proves it. Marvin Barth reads the double-digit swings in nearly every demographic, toward Republicans in 2024 and away in 2026, as a competitive democracy doing its job, and expects US outperformance against Europe to persist.
THE REST OF THE TAPE.
The average new vehicle sold for a record $51,109 in October, up 2.1% on the year, while sales slowed to a 15.5 million annual rate from 16.0 million. Automakers are ‘happy to sell fewer cars’ if the ones they sell are pickups.
Beijing called the midterms an internal affair; a president under pressure on prices may be easier to bargain with on tariffs.
Banks are buying credit insurance against their AI lending (FT).
The New York Fed’s household report showed troubled debt rising in the third quarter.
Costco declared a $30 special dividend and reauthorized a $4 billion buyback.
Shinkin Central Bank’s West Japan center went dark on 6 November, taking ATMs and online banking offline at 128 banks; Shinkin has not ruled out a cyberattack.
United Kingdom.A US Army officer assigned to a NATO rapid-reaction unit was arrested on suspicion of spying for Russia.
Bulgaria.At least 11 people died in a multi-vehicle pileup on the Trakia motorway.
Antalya.COP31 opened in Turkey with Guterres urging governments to plan for a post-fossil economy; Iran’s President Pezeshkian is attending.
Jerusalem.The new Knesset opposition is pushing an October 7 inquiry, a repeal of the judicial overhaul and term limits, with Eisenkot still short of a majority.
COREWEAVE. Up roughly 14% to 18% before the open. Third-quarter revenue rose 168% to $3.66 billion, backlog reached $132.5 billion, and the full-year guide went to $13.0 billion to $13.3 billion (Reuters). Then the other column. Net interest expense was $846 million against $310 million a year ago and against $207 million of GAAP operating income, with $1.05 billion to $1.15 billion guided for the fourth quarter. Cash spent on equipment ran $9.44 billion against $1.98 billion of operating cash flow, and the gap closes only if about $9 billion of customer prepayments show up over the next three months as management expects. Demand is fine. The equity holder is the last one paid, and nothing on the sheet trades the name, though that interest bill is the argument for the HYG short.
NVIDIA. Up about 3.5% before the open after Monday’s 4.2% fall to its lowest close since 7 April. Marco Rubio told the President aboard Air Force One in May, en route to Beijing, that the US had intelligence on Jensen Huang’s relationship with a woman believed to be a Chinese spy, and Huang joined the trip anyway; it was at least the second such briefing in seven months. The board has hired Wachtell for its own probe (BBC). A bounce with no company news is positioning, and the quarter lands on 17 November.
THE MEMORY NAMES. SanDisk up about 6%, Micron and Western Digital about 5% each. The Nasdaq 100 trades near 18 times forward earnings, the cheapest since the worst of 2020.
Semiconductors trade near 10.5 times two-year forward earnings and consumer staples near 23. Cheap chips and expensive soup.
Behind the wall this morning:
THE BOOK: 13 live lines, 5 new today, three of them under my 2 to 1 floor for a new line.
FLOWS AND POSITIONING: who is buying the chip dip with borrowed money, and what forces the next move.
FINANCIALS: where a December hike pays a bank, where it costs a bank, and why I think the discount is backward.
The free section is what moved. The paid section is what I did about it, and the level that undoes each line. Subscribe at marketmusing.com.
Disclaimer: Opinions are mine alone and may change. It does not constitute an offer to buy or sell or a solicitation of an offer to buy or sell any security, loan or asset or to participate in any trading strategy. It is not intended to form the basis of any investment decision, should not be considered a recommendation, and does not constitute an offer or solicitation with respect to the purchase or sale of any investment, nor is it a confirmation of such terms.