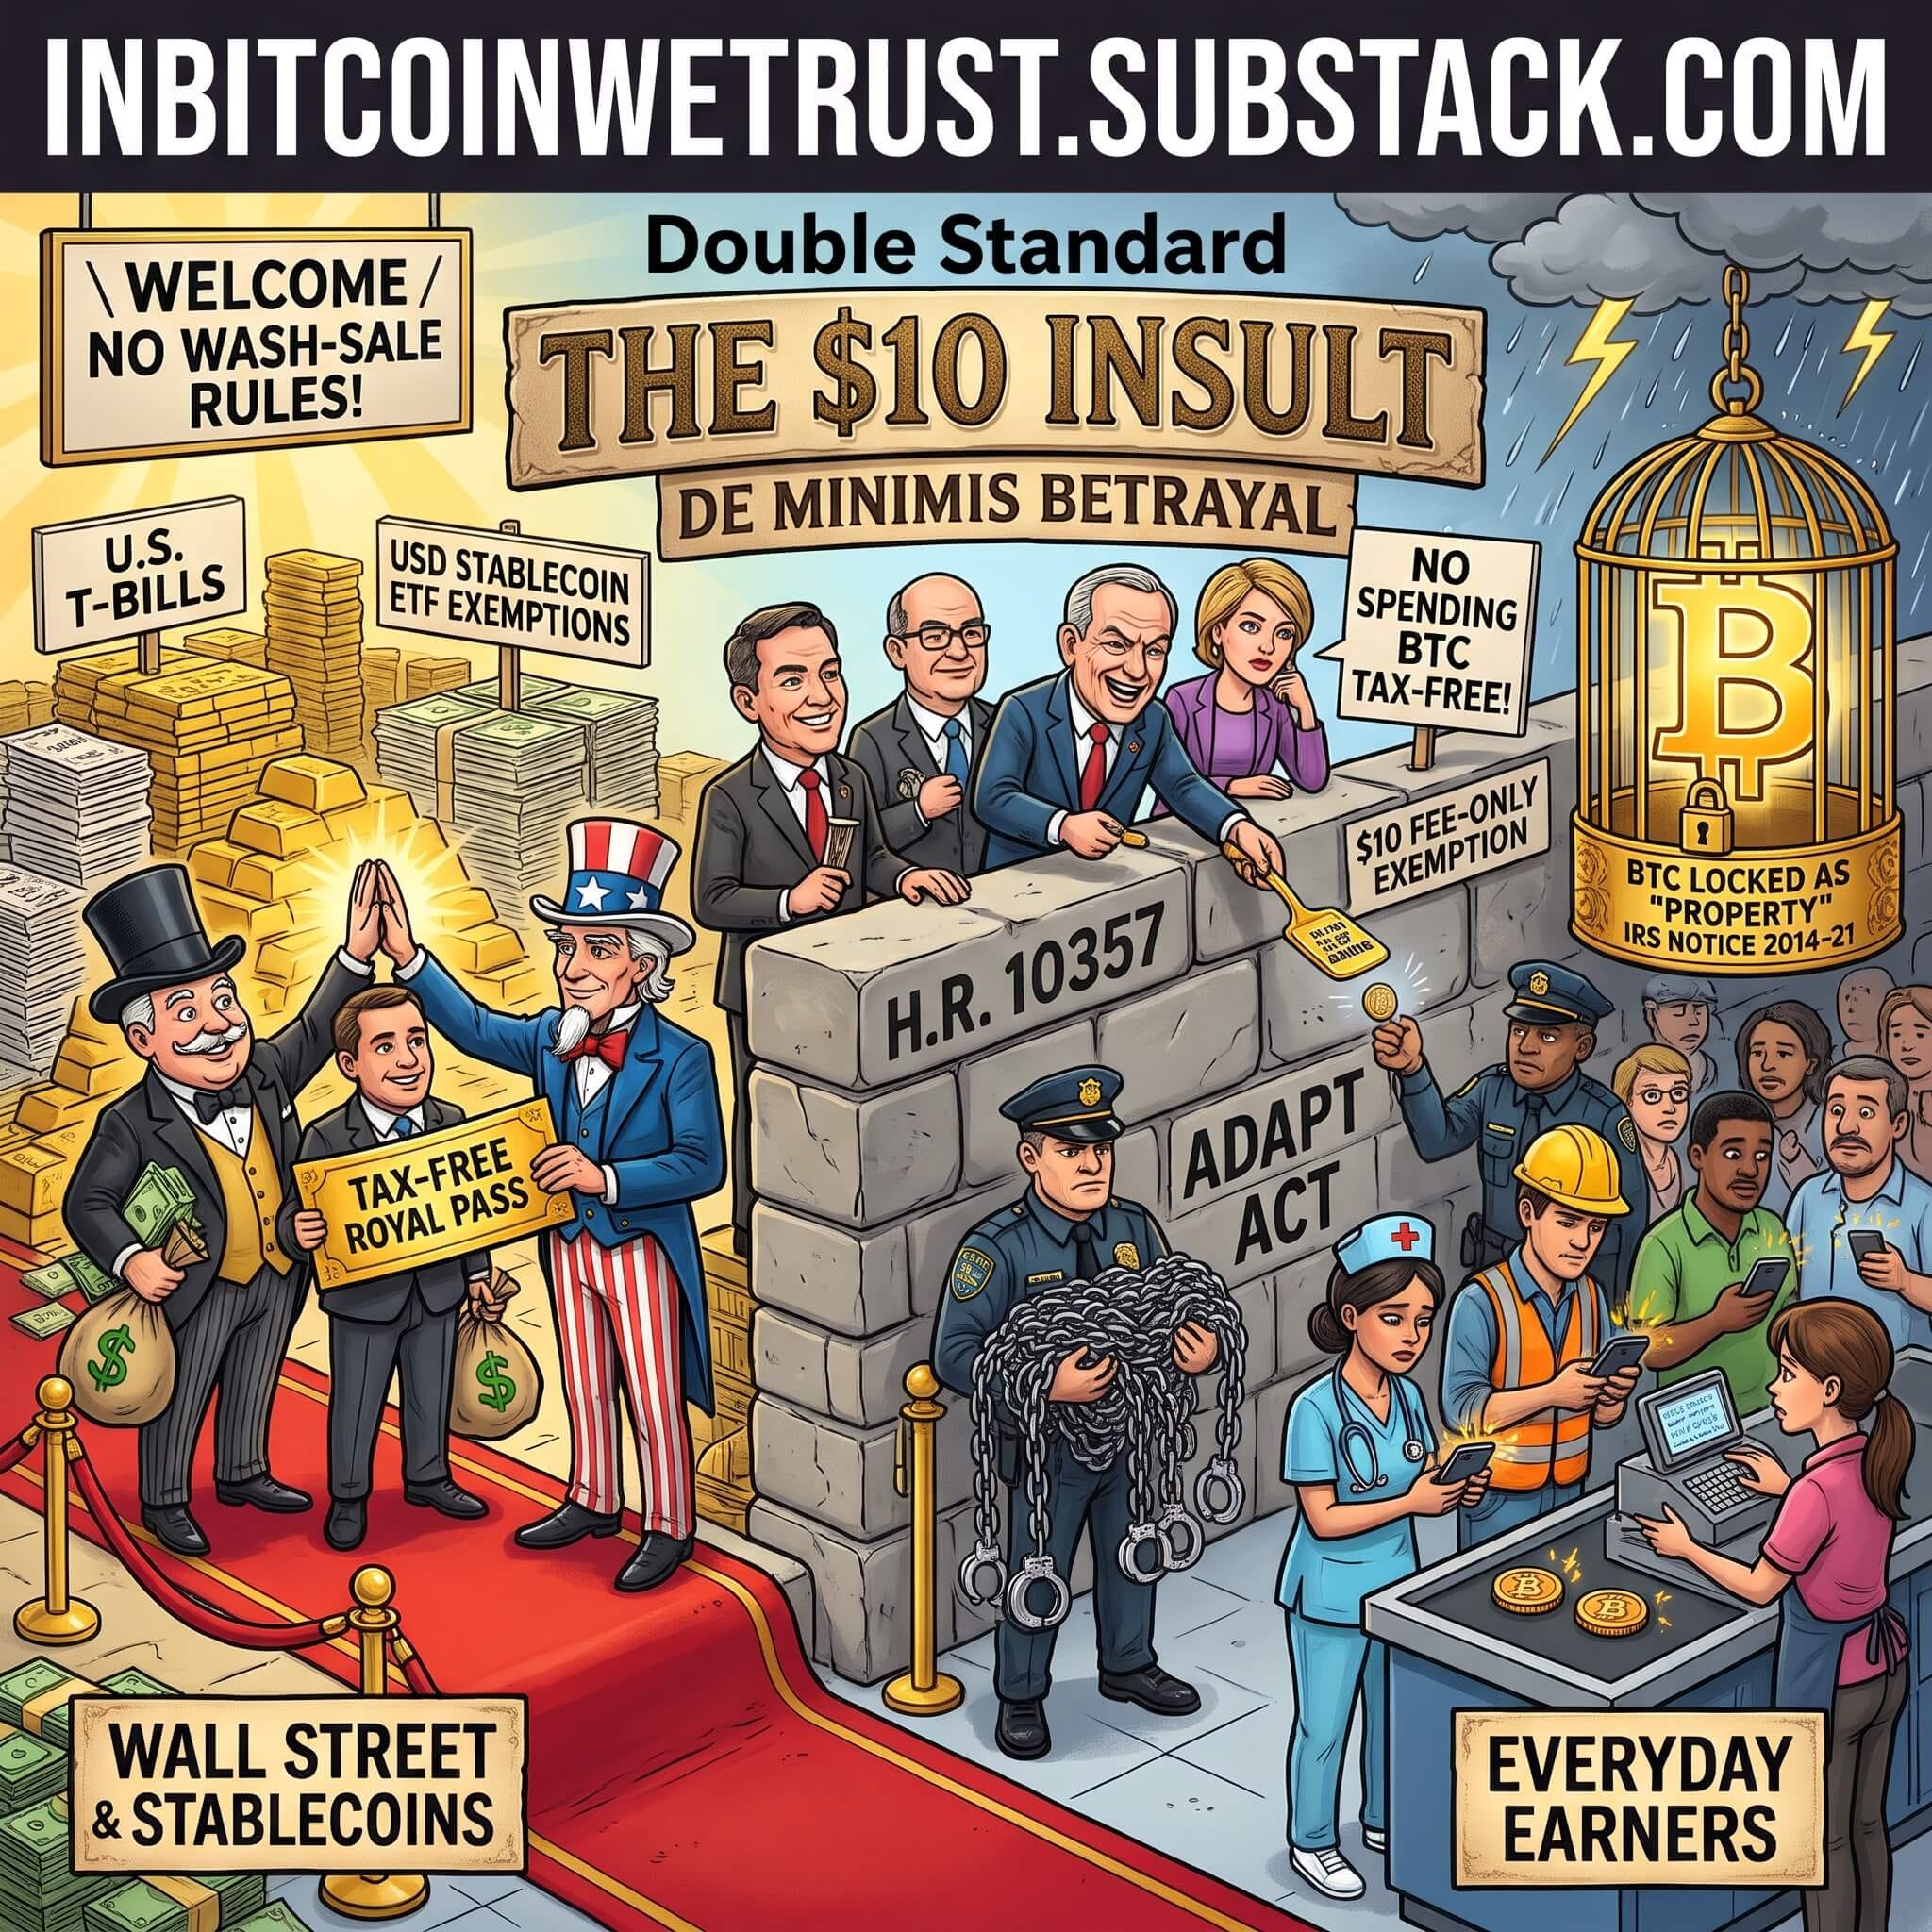
Politicians promised to make America the Bitcoin capital of the world. Instead, H.R. 10357 and the ADAPT Act hand Wall Street and dollar stablecoins a royal pass—while tossing working Americans a $10 network-fee crumb and a brand-new set of IRS handcuffs.
Walk into an independent coffee shop in Austin, a family-owned auto repair garage outside Phoenix, or one of the 219 local Arizona merchants that participated in this autumn’s grassroots Lightning Network field tests.
Pull out your phone, scan a QR code at the register, and tap “Send” on a $14.50 payment for a turkey club sandwich and an iced coffee.
In less than four hundred milliseconds, a cryptographic state update flashes across a decentralized mesh of Lightning routing nodes. There is no Visa interchange fee skimming 3% off the merchant’s razor-thin margin. There is no commercial bank holding the settlement hostage for three business days. There is no payment processor threatening to freeze the shop owner’s account. For a routing fee of less than a fifth of a penny, final, irreversible value moves from one human being to another.
Technologically, in October 2026, Satoshi Nakamoto’s seventeen-year-old vision of “a purely peer-to-peer version of electronic cash” is no longer a whitepaper dream. It works in the palm of your hand, faster and cheaper than any legacy rail ever built.
Legally, however, you just walked into an Internal Revenue Service compliance trap.
Under the archaic doctrine of ** IRS Notice 2014-21**—which classifies Bitcoin not as money or currency, but as “property” akin to a commercial office building or a vintage tractor—buying that $14.50 sandwich is not a simple purchase.
To stay strictly within the letter of federal law, you must determine the exact date and dollar price at which you acquired those specific 17,500 satoshis two years ago, subtract that cost basis from the $14.50 fair market value of the sandwich at the exact minute you bit into the toast, calculate your short- or long-term capital gain (say, $4.12), and report the disposition on IRS Form 8949 and Schedule D of your federal income tax return.
Do that three times a week for groceries, gas, and coffee, and by April 15 you are buried under a 150-page spreadsheet of micro-dispositions—while facing new third-party Form 1099-DA broker surveillance designed to flag every discrepancy down to the penny.
For the past two years, politicians from both parties stood on conference stages from Nashville to Las Vegas and promised everyday Americans that help was on the way.
They vowed to end the absurdity of taxing a cup of coffee. They promised a clean, common-sense de minimis** tax exemption**—blocking capital gains taxes on personal Bitcoin transactions under $200, $300, or $600—so working families could finally save and spend in sound money without hiring a Certified Public Accountant to follow them down the grocery aisle.
Over the past five weeks, the masks came off on Capitol Hill.
Following the dramatic collapse of the broader market-structure bill in mid-September, both the House Ways and Means Committee and Senate tax writers unveiled their long-awaited flagship crypto tax overhauls: ** H.R. 10357 (the Digital Asset Tax Certainty Act)** and Senator Steve Daines’s
Headlines across the financial press dutifully cheered that Congress had finally approved a “historic de minimis crypto tax exemption.”
Then Bitcoiners, tax attorneys, and policy researchers actually read the statutory text. What they found inside those pages triggered an open revolt—culminating on Thursday, October 22, 2026, when the Blockchain Association sent an urgent letter to the top four leaders of Congress refusing to endorse either bill and demanding an immediate rewrite before the legislative clock runs out.
Why the mutiny? Because instead of liberating everyday Americans to use Bitcoin as money, Congress delivered what can only be described as the $10 Insult.
Worse still, when you read the fine print of H.R. 10357 and the ADAPT Act, you discover that for Bitcoin holders, that laughable $10 exemption doesn’t even apply to buying a sandwich. It applies only to network transaction fees—while handing a tax-free retail monopoly to U.S. dollar stablecoins, slapping punitive new wash-sale and constructive-sale restrictions onto retail Bitcoiners, and gutting tax relief for independent miners.
Here is the complete investigation into the great crypto tax bait-and-switch of autumn 2026—how Washington is weaponizing the tax code to protect the dollar, why Wall Street got everything it asked for while working earners got crumbs, and what it reveals about the state’s deepest fear of Bitcoin.
To understand how we arrived at the $10 insult in late October 2026, we have to trace the political choreography of the last sixteen months.
Throughout 2025 and the summer of 2026, a meaningfulde minimisexemption for Bitcoin was the single most popular, bipartisan common-sense reform in Washington.
Even lawmakers skeptical of speculative DeFi tokens agreed on a basic principle of administrative sanity: forcing tens of millions of citizens to calculate capital gains on small, everyday retail transactions wastes billions of hours of human productivity and buries the IRS in useless data that costs more to process than it ever collects in revenue.
In June 2025, Senator Cynthia Lummis (R-WY) introduced S. 2207, a targeted bill proposing a $300 per-transaction de minimis exemption (with a generous $5,000 annual cap) that covered Bitcoin and digital assets across the board. Earlier bipartisan proposals in the House, such as the Virtual Currency Tax Fairness Act, had similarly coalesced around a $200 to $600 threshold. At the Bitcoin 2026 conference earlier this year, making small Bitcoin purchases tax-free was celebrated as a centerpiece of the legislative agenda.
Then came September 2026, and the gears of the Washington sausage factory began to grind.
On Tuesday, September 15, 2026, the broader digital asset market-structure bill—the Clarity Act—crashed into a wall on the Senate floor. The cloture vote failed 49–50, falling well short of the 60 votes needed to advance. Not a single Senate Democrat crossed the aisle; Republicans Susan Collins, Josh Hawley, and Jerry Moran voted no, and Senator Thom Tillis switched his vote to “no” at the last second strictly as a procedural maneuver so he could file a motion to reconsider and keep the corpse technically alive on paper.
With market structure dead in the water ahead of the elections, Capitol Hill pivoted immediately to the one vehicle that could still move: tax legislation.
Less than twenty-four hours after the Clarity Act failed in the Senate, on Wednesday, September 16, 2026, House Ways and Means Committee Chairman Jason Smith (R-MO) brought H.R. 10357, the Digital Asset Tax Certainty Act—a sweeping 114-page omnibus package combining seven earlier discussion drafts—to a committee markup. It passed in a lopsided, bipartisan 38–5 vote. Two weeks later, on September 30 (and formally championed again on October 22), Senator Steve Daines (R-MT) unveiled the Senate counterpart: a 56-page bill known as the ADAPT Act.
Press releases flew out of congressional offices declaring that lawmakers had “removed tax barriers to the use of digital assets as a medium of exchange” to “keep America the Crypto Capital of the World.”
Let’s look past the press releases and examine what Title I of H.R. 10357 and the ADAPT Act actually do:
THE GREAT DE MINIMIS BAIT-AND-SWITCH (OCTOBER 2026)
================================================================================
PROPOSAL / LAW THRESHOLD APPLIES TO BITCOIN APPLIES TO
RETAIL PURCHASES? NETWORK FEES?
--------------------------------------------------------------------------------
IRC § 988(e) $200 gain NO (Applies only to N/A
(Existing Foreign Cash) per tx foreign fiat money!)
Sen. Lummis Bill $300 per tx YES (Full retail & YES
(S. 2207 — Stalled) ($5K/yr cap) peer-to-peer parity)
House Ways & Means Bill $10 NO! (Regulated USD YES (Only fees
(H.R. 10357 — Passed 38-5) stablecoins only!) under $10!)
Senate ADAPT Act $10 NO! (Qualifying USD YES (Only fees
(Sen. Daines — Oct 2026) stablecoins only!) under $10!)
================================================================================
Read that table carefully, because it exposes one of the most cynical legislative sleights of hand in recent memory.
The $300 Threshold Was Slashed by 97% Down to $10:Instead of Senator Lummis’s $300 threshold or the existing $200 foreign currency threshold, the tax committees slashed thede minimisnumber down to$10.**Bitcoin Was Quietly Cut Out of Retail Spending Entirely:*In Chairman Jason Smith’s H.R. 10357, Title I excludes gain or loss on sales ofregulated U.S. dollar stablecoins, and excludes gain or loss on“the use of digital assets to pay network fees and transaction fees under $10.”*That’s it!Neither chamber’s bill contains the exemption for small bitcoin purchases that the industry made a centerpiece at Bitcoin 2026. The House bill’s $10 threshold covers fees, not purchases. The Senate bill’s spending exemption covers stablecoins, not bitcoin.
Think about what that means for an everyday wage earner.
Under H.R. 10357 and the ADAPT Act, if you send a Bitcoin transaction and pay a $1.50 on-chain miner fee, the IRS generously agrees that you don’t have to calculate capital gains on the $1.50 fee you paid to the miner.
Put it this way: if the actual payment inside that transaction was $8.00 of Bitcoin to buy a loaf of sourdough bread and a carton of milk at your local farmers’ market, you still owe capital gains tax and full IRS reporting on the $8.00 purchase!
Congress didn’t exempt Bitcoin payments under $10. They exempted the postage stamp up to $10—while keeping the letter inside fully taxable from the very first cent.
Even if we set aside the exclusion of Bitcoin retail purchases and judge the $10 figure on its own terms—where Sen. Daines’s ADAPT Act applies a $10 cap to small stablecoin payments and network fees, or where defenders of H.R. 9178 (the Less Paperwork for Digital Asset Owners Act) argue that $10 is a “pragmatic starting point”—the number $10 is a slap in the face to every working family in America.
Have the members of the House Ways and Means Committee walked into a grocery store, a pharmacy, or a diner in the year 2026?
Between 2020 and October 2026, the cumulative purchasing power of the U.S. dollar has been shredded by more than 25% on official Consumer Price Index metrics, and closer to 35%–40% on everyday household essentials like beef, eggs, auto repairs, utilities, and child care.
What does $10 actually buy an American worker in October 2026?
REAL-WORLD PURCHASING POWER vs. THE $10 CONGRESSIONAL THRESHOLD (OCT 2026)
================================================================================
EVERYDAY AMERICAN EXPENSE (2026) TYPICAL COST COVERED BY $10 CAP?
--------------------------------------------------------------------------------
On-Chain L1 Miner Fee / L2 Routing Fee $0.01 – $2.50 [✓] YES (The Crumb)
Single Specialty Coffee + Tip $7.50 – $9.00 [✗] NO (If paid in BTC)
Fast-Food Combo Meal for One Worker $13.50 [✗] NO
Two Gallons of Milk + Dozen Eggs + Bread $18.75 [✗] NO
Tank of Regular Unleaded Gasoline (14 gal) $49.00 [✗] NO
Weekly Family Grocery Run (Family of 4) $265.00 [✗] NO
================================================================================
Ten dollars in 2026 does not buy lunch for a carpenter on his break. It does not buy a paperback book, a prescription co-pay, a haircut, a pound of ribeye, or three gallons of gas. Setting a de minimis threshold at $10 in 2026 is the economic equivalent of setting it at $1.50 in 1980.
Why on earth did the House Ways and Means Committee settle on the number $10 during its September 16 markup?
They admitted the real reason right in the committee hearing record. During the markup of H.R. 10357, committee members noted that under the new Form 1099-DA broker reporting regime, the IRS is projected to receive hundreds of millions—and eventually billions—of digital asset transaction forms every year, roughly half of which are for tiny network fees and dust amounts under $10.
Read that again.
The $10 threshold was never designed to give financial freedom to the American taxpayer. It was designed to save the IRS’s outdated computer servers from crashing under the weight of 500 million $0.40 gas-fee forms!
Now contrast this $10 crumb with how the same Internal Revenue Code treats foreign fiat currencies.
Turn to 26 U.S.C. § 988(e) of the Internal Revenue Code, titled “Application to individuals.” Under Section 988(e)(2), if an individual American citizen engages in a “personal transaction” using a foreign currency—say, Euros, British Pounds, Swiss Francs, or Japanese Yen—they are completely exempt from recognizing any foreign currency exchange gain, provided the gain (not the transaction size, the profit!) does not exceed $200 per transaction.
Pause and do the math on how massive that disparity is.
Suppose you take $2,000 of U.S. dollars and convert them into Swiss Francs or Euros. Over the next year, the dollar weakens by 10%, so your foreign currency is now worth $2,200. You walk into a store and spend $1,500 worth of those Euros on a new laptop or a hotel stay. Because your exchange-rate gain on that $1,500 purchase is only $150 (well below the $200 gain limit of Section 988(e)), your $1,500 transaction is 100% tax-free and requires zero reporting to the IRS!
Let that sink in:
If you hold paper currency issued by Christine Lagarde at the European Central Bank or Kazuo Ueda at the Bank of Japan, Congress lets you make a**$1,500 purchasewith up to$200 of pure profitper transaction without owing a single cent in taxes or filling out a single line on your tax return.If you hold decentralized, American-mined Bitcoinand spend$11.00**to buy your daughter a school notebook—realizing a $0.85 gain—H.R. 10357 and the ADAPT Act treat you like a Wall Street hedge fund liquidating a stock portfolio and demand a capital gains filing!
Why does the United States Congress treat the currencies of foreign central banks more than twenty times better than it treats Bitcoin?
Because foreign central banks are members of the same global fiat cartel. Bitcoin is not.
First GPUs. Then memory. Then power. Now the suits think expensive debt will kill AI. Always bet on the engineers.
When you place H.R. 10357 and Senator Daines’s ADAPT Act side by side, a striking pattern jumps off the page.
Both bills are remarkably generous toward one specific corner of the digital asset universe: regulated U.S. dollar stablecoins.
H.R. 10357 explicitly excludes any gain or loss on the sale or spending of regulated U.S. dollar stablecoins.
H.R. 10357 explicitly
exempts qualified dollar stablecoins from the new wash-sale rulesit imposes on every other digital asset.Senator Daines’s ADAPT Act centers its entire medium-of-exchange relief around preventing consumers from recognizing gains or losses when they use compliant dollar stablecoins to buy goods and services.
Meanwhile, both bills systematically strip Bitcoin of every single one of those medium-of-exchange protections.
Why is Washington rolling out the red carpet for corporate dollar stablecoins as everyday money, while locking Bitcoin inside a high-friction “property” cage?
To find the answer, you only have to look at the balance sheet of the United States Treasury in October 2026.
With the U.S. national debt towering past $36 trillion and annual net interest payments exceeding the entire defense budget, Washingto…