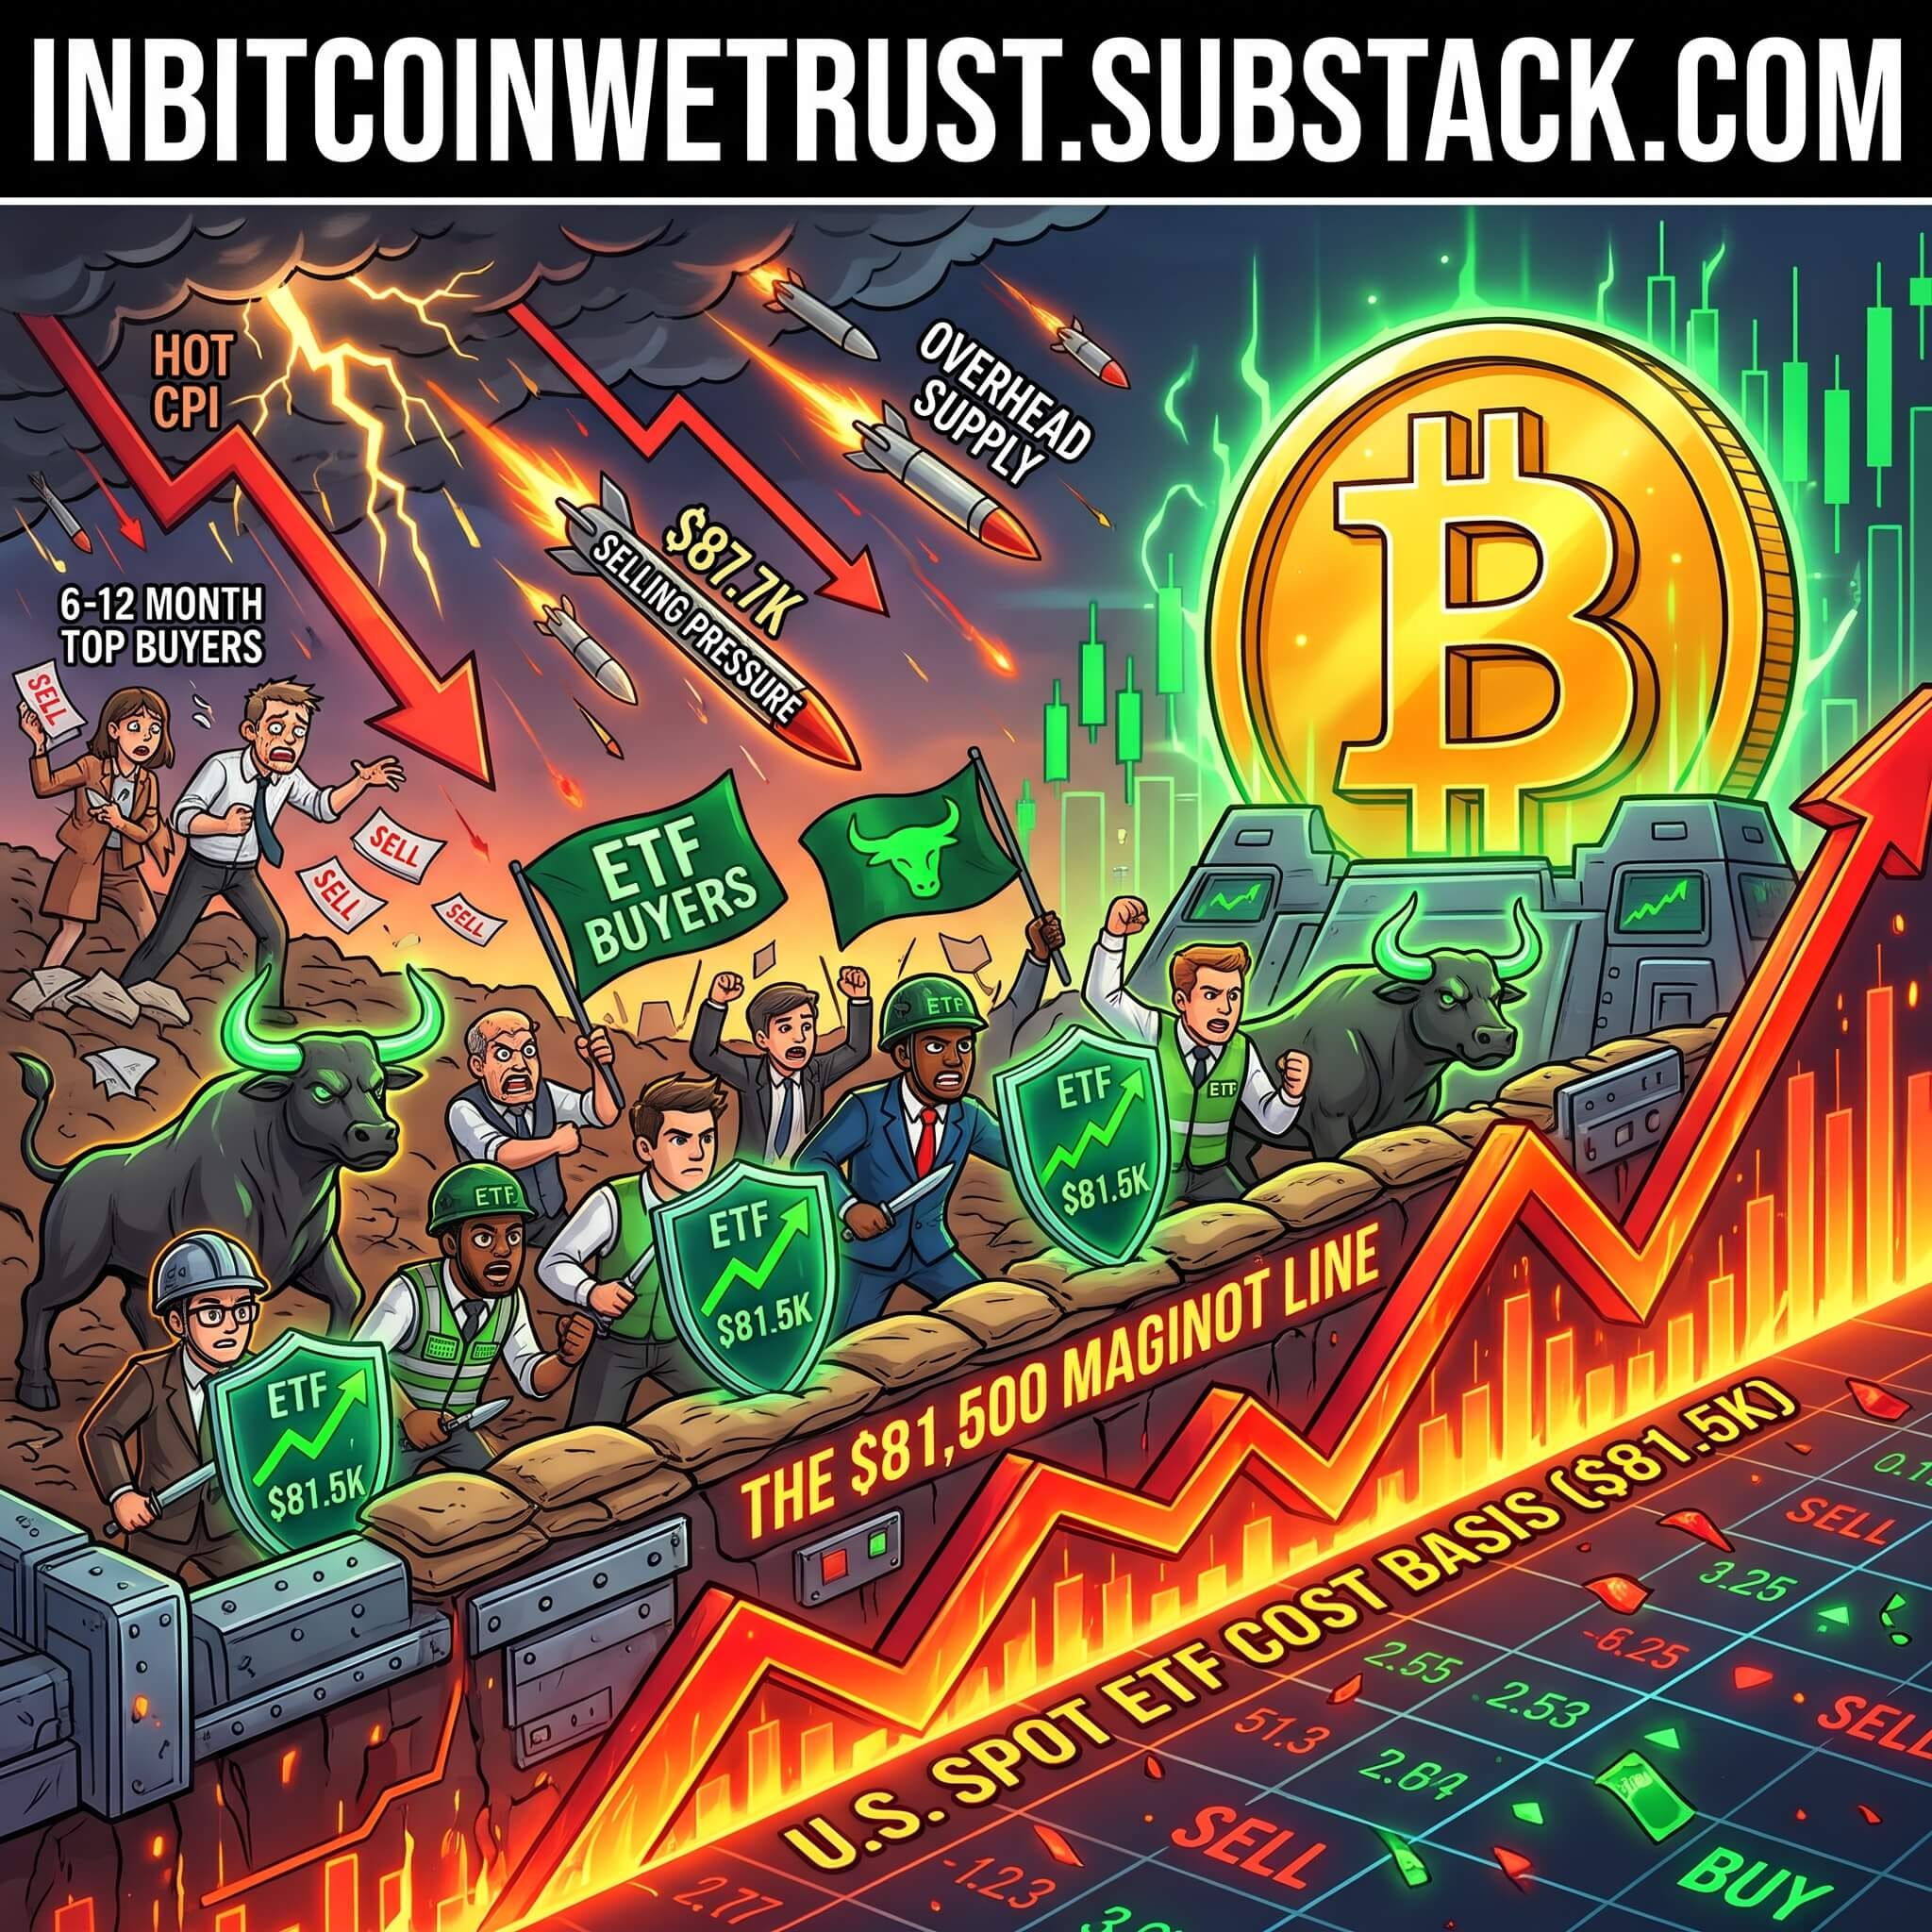
Boxed in between exhausted top buyers at $87,700 and a macro storm on the horizon, Bitcoin’s entire autumn structure now rests on a single on-chain number—the exact price where institutional America goes underwater.
Watch the order book on a professional trading terminal at four o’clock in the afternoon in New York—right as the closing bell echoes across the floor of the New York Stock Exchange and the net asset value of eleven U.S. spot Bitcoin exchange-traded funds is stamped into the ledger.
For the past three weeks of October 2026, that screen has looked less like a speculative mania and more like a World War I artillery duel.
Every time Bitcoin gathers enough momentum to charge toward $85,000—as it did in early October, and again on October 21—an invisible machine gun nest in the hills opens fire. Hundreds of millions of dollars in overhead supply pour onto the tape. The 4-hour Relative Strength Index rolls over, two days of hard-won gains evaporate in a four-percent downdraft, and the price is dragged right back into the mud of the low $80,000s.
Yet every time the bears prepare to celebrate a total breakdown, something equally violent happens in the opposite direction.
When Bitcoin was slammed down to $80,000 on October 15, the panic sellers expected the floor to give way into a summer-style cascade. It didn’t. Within hours, passive institutional limit orders swallowed the liquidation wick whole. Days later, on October 19, U.S. spot ETFs roared back with $653 million in single-day net inflows, hauling the price right back above the trenches.
To a casual observer staring at a basic candlestick chart, late October 2026 looks like random, frustrating chop—a market stuck in purgatory, down roughly 7% year-to-date from its $87,490 January open while gold, oil, and sovereign bond yields steal the macroeconomic spotlight.
But when you strip away the surface price action and look beneath the hood of the blockchain using institutional cost-basis forensics, there is nothing random about where Bitcoin is stalling or where it is bouncing.
The entire global Bitcoin market is currently locked inside a razor-tight, $6,000 structural compression chamber. Above our heads sits a dense concrete ceiling between $85,000 and $87,700, manned by trapped buyers from the last twelve months who are desperate to sell at breakeven. And right beneath our boots sits the most consequential price floor in modern digital asset history: $81,500.
Why $81,500? Because according to on-chain intelligence firm Glassnode, $81,500 is the exact aggregate cost basis of all U.S. spot Bitcoin ETF investors. In plain English, it is the average price that Wall Street pension funds, registered investment advisors, family offices, and retail brokerage accounts paid for their $108 billion mountain of Bitcoin.
With corporate Bitcoin treasuries suddenly freezing their monthly purchases near their $80,000 breakeven mark and crypto-native exchange stablecoin reserves sitting at a one-year low, the ETF cohort is no longer just one participant among many. Right now, the $81,500 ETF cost basis is the final line of defense standing between an autumn consolidation and a deep structural unwind toward $74,850.
Here is the complete forensic anatomy of Bitcoin’s October trench war—who is selling the ceiling, who is defending the floor, and what happens next as the Federal Reserve’s October 28 rate decision approaches.
In traditional equity markets, finding out the exact average price that every shareholder paid for a stock like Apple or Nvidia is guesswork. Shares churn through dark pools, high-frequency algorithmic desks, and omnibus street-name accounts where cost bases are hidden inside private brokerage databases.
Bitcoin is different. Because every movement of coins into and out of known custodial clusters leaves an immutable timestamp on the public ledger, on-chain analysts can calculate the Realized Price—the volume-weighted average acquisition price—of every specific tribe in the Bitcoin ecosystem.
When spot Bitcoin ETFs first launched in the United States in January 2024, they triggered a gold rush that fundamentally rewired Bitcoin’s market structure. Over the past thirty-three months, those funds have accumulated roughly $57.6 billion in cumulative net inflows and hold more than $108.4 billion in net assets.
As billions of dollars flowed into funds managed by BlackRock, Fidelity, Bitwise, and Ark throughout the rallies of 2024, 2025, and 2026, the average acquisition cost of those ETF-held coins steadily ratcheted higher, eventually settling at a gravitational center of gravity: $81,500.
To understand why $81,500 carries such immense psychological weight today, you have to remember what that exact number did to the market just five months ago.
THE 2026 ON-CHAIN COST-BASIS BATTLEFIELD (LATE OCTOBER 2026)
=============================================================================
PRICE LEVEL ON-CHAIN / TECHNICAL SIGNIFICANCE MARKET ROLE
-----------------------------------------------------------------------------
$99,500 1-to-2-Year Holder Cost Basis Macro Supply Wall
$96,700 Mean MVRV Valuation Level Bull Target
-----------------------------------------------------------------------------
$87,700 6-to-12-Month Holder Cost Basis ("Tops") HEAVY CEILING
$87,490 2026 Yearly Open (-7% YTD below here) Overhead Supply
$87,165 20-Month Moving Average Technical Cap
$85,000–$87,500 Order-Book Asks & Short Liquidations Rejection Zone
=============================================================================
>>> CURRENT BATTLEGROUND: ~$81,380 – $83,100 (Late October 2026) <<<
=============================================================================
$81,835 50-Day Simple Moving Average (SMA) Immediate Pivot
$81,500 U.S. SPOT BITCOIN ETF COST BASIS THE MAGINOT LINE
$80,000 Corporate Treasury Average Cost Basis Psychological Floor
-----------------------------------------------------------------------------
$77,500–$78,000 True Market Mean (Active Investor Basis) Primary Fallback
$74,850 Short-Term Holder (STH) Realized Price Bull/Bear Line
=============================================================================
Cast your mind back to May 2026.
Bitcoin had spent months trading beneath the $81,500 watermark, leaving the average Wall Street ETF buyer sitting on an uncomfortable unrealized paper loss. When Bitcoin staged a spring relief rally in May, it charged straight toward $81,500—and slammed into a brick wall.
Why did the May rally die right at $81,500? Because in financial markets, human psychology is governed by loss aversion. When investors buy an asset at $81,500, watch it sink into the $60,000s, and spend months enduring critical phone calls from their spouses or investment committees, their primary prayer is no longer “I hope I double my money.” Their prayer becomes “Lord, just get me back to even so I can get out.”
In May 2026, as soon as the price touched the $81,500 ETF breakeven line, a wave of exhausted institutional and retail ETF holders hit the redemption button. From mid-May to early June, U.S. spot Bitcoin ETFs suffered a brutal 13-day outflow streak that sucked $4.4 billion out of the complex. Rejected at $81,500 and stripped of bid support, Bitcoin rolled over and plunged below $60,000 by early July.
Then came the late-summer resurrection.
In mid-August, a record short-squeeze ignited a 26% rally off the summer lows. Unlike the hollow derivatives bounces earlier in the year, real spot capital paid for the late-August and September surge. In September 2026 alone, U.S. spot Bitcoin ETFs vacuumed up $2.65 billion in net inflows—their second-largest monthly intake since October 2025—highlighted by a massive $2.4 billion single-week haul ending September 25 that dragged year-to-date ETF net flows back into positive territory at roughly $1.2 billion.
As Bitcoin powered back above $74,850, cleared $78,000, and finally vaulted past $81,500 in late September, a classic structural polarity flip took place.
What had been a suffocating ceiling in May transformed into a fortified concrete floor in October. For the last three weeks, every time spot prices have dipped toward the $80,000-to-$81,500 band, value-oriented institutional allocators and systematic rebalancing desks have stepped in to defend their collective cost basis.
As Vugar Usi Zade, Chief Operating Officer at MEXC, recently observed regarding this structural evolution, Bitcoin has entered a phase of institutional maturity where the $80,000-to-$81,500 zone represents the core acquisition anchor for spot ETFs and institutional custodians.
When price pulls back into that zone, it no longer triggers automatic retail panic; instead, institutional desks view their own breakeven floor as a high-conviction discount zone to reload.
The battle over stablecoin rewards is opening a much bigger fight: who gets paid on the money you use every day—and who gets to finance America with it.
It is easy to talk about support levels in theory. It is another thing entirely to watch a support level survive a live-fire stress test when hundreds of millions of dollars are heading for the exits.
Consider the sequence of events that has unfolded over the past fourteen days in October 2026:
The $746 Million Outflow Test (Early-to-Mid October):After three consecutive weeks of positive ETF inflows ending October 2 (which added a modest $241 million), institutional sentiment soured as September’s Consumer Price Index (CPI) inflation print came in hotter than Wall Street expected and sovereign Treasury yields held near cycle highs. Over the following week and a half, U.S. spot Bitcoin ETFs bled $681 million in weekly net outflows, followed immediately by another $65 million redemption on Monday, bringing the short-term exodus to$746 million. Even titans like BlackRock’s IBIT contributed to a combined $150 million opening-week sell-off across Bitcoin and Ether funds.The October 15 Liquidity Sweep:Under the weight of $746 million in ETF redemptions and a hawkish macroeconomic backdrop, sellers pressed their advantage. On October 15, Bitcoin was driven down through $81,500, sweeping all the way to$80,000—dipping just underneath the cost basis of both the U.S. spot ETFs ($81,500) and corporate Bitcoin treasuries ($80,000).**The Instantaneous Refill:*In Glassnode’s October 21 flagship report, aptly titled“Swept and Refilled,”*analysts documented what happened next. The dip below $81,500 did not trigger a cascade of institutional capitulation. Instead, spot bids in the $80,000-to-$81,500 overlap zone refilled within days, absorbing the forced selling.The October 19 Institutional Counter-Punch:By Monday, October 19, the institutional pendulum swung back violently: U.S. spot Bitcoin ETFs logged$653 million to $665.2 million in single-day net inflows—almost single-handedly erasing the prior week’s outflow streak in a single eight-hour trading session and catapulting Bitcoin back toward $85,000.The October 21–22 Rejection:Yet when Bitcoin reached the edge of $85,000 on October 21, the rally ran out of oxygen once again. Over the next forty-eight hours into October 22 and 23, Bitcoin shed 4%, erasing two full days of gains, slipping below the 0.618 Fibonacci retracement ($82,614), and returning directly to test the 50-day moving average ($81,835) and the$81,500 ETF cost basis floor.
OCTOBER 2026 TIMELINE: THREE TESTS OF THE $81,500 ETF FLOOR
=============================================================================
Oct 1–7: "A Rally Running Light" — BTC pokes above $85K on thin volume;
stalls out as ETF inflows fade to $241M/wk.
Oct 8–14: "Boxed In" — Hot September CPI print; ETFs bleed $746M in net
outflows ($681M weekly + $65M Monday). BTC tests $81.5K & holds.
Oct 15: "Swept and Refilled" — Price sweeps down to $80.0K, piercing the
ETF & corporate cost bases; institutional spot bids refill fast.
Oct 19: The Counter-Punch — Spot ETFs absorb $653M–$665M in a single day;
BTC surges back toward $85,000.
Oct 21–23: The Third Test — Rejected at $85K; BTC slides 4% back to $81.8K,
putting the $81,500 ETF floor under the microscope once again.
=============================================================================
Look closely at that tug-of-war. Three times in less than three weeks, the market has dragged Bitcoin down to the exact penny where Wall Street’s ETF cohort breaks even. And three times, that line has held.
Why is the entire weight of this defense falling onto ETF buyers and spot limit orders at $81,500? Because when we examine the rest of the Bitcoin ecosystem in late October 2026, the other two engines that powered the bull market of 2025 have temporarily shut down.
For the past two years, Bitcoin’s upward marches were supported by a three-legged stool of demand:
U.S. Spot ETFs(Wall Street wealth management and institutional allocators).Corporate Bitcoin Treasuries(publicly traded companies issuing equity and convertible debt to stack BTC on their balance sheets).Crypto-Native Spot & Derivatives Liquidity(fueled by expanding stablecoin supplies on global exchanges).
Right now, two of those three legs are wobbling.