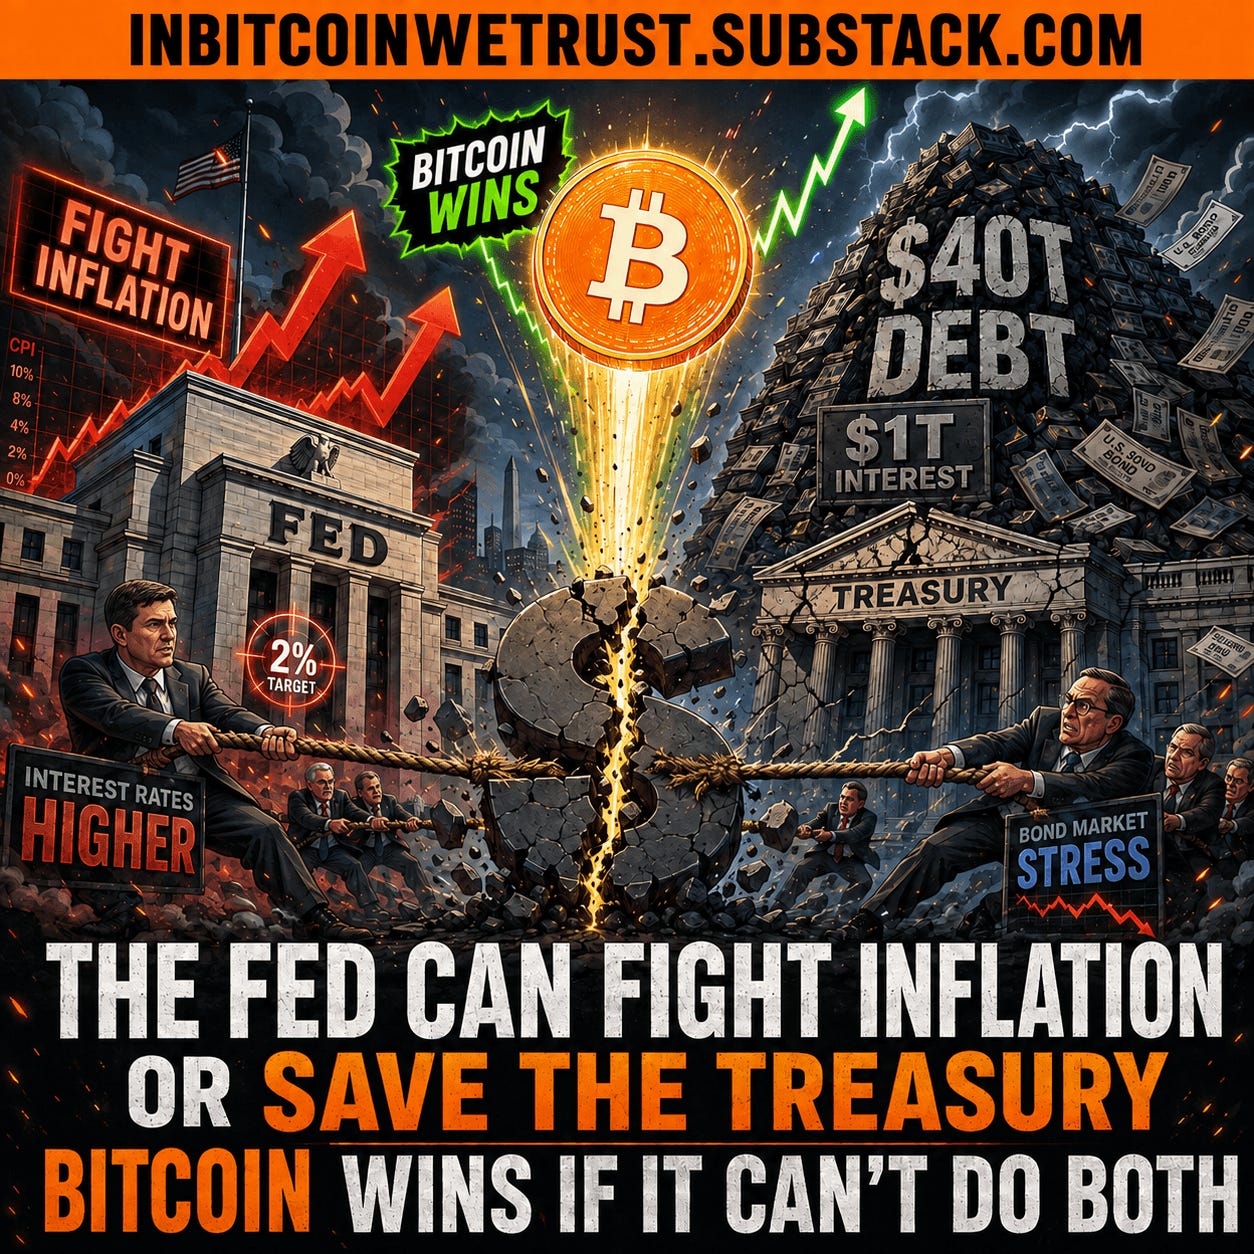
America’s debt machine is colliding with its inflation problem. If keeping government borrowing costs under control starts competing with protecting the dollar, Bitcoin may become the escape valve investors have been waiting for.
There is a phrase you’re going to hear a lot more often over the next few years.
Fiscal dominance.
It sounds like something designed to put normal people to sleep. It isn’t.
In fact, fiscal dominance may eventually become one of the most important macroeconomic concepts for understanding Bitcoin.
Because underneath those two boring words sits an extraordinary problem.
The Federal Reserve has one job it cannot afford to abandon:
Protect the purchasing power of the dollar.
The U.S. Treasury has another problem it increasingly cannot ignore:
Finance an enormous and rapidly growing pile of government debt without blowing up the bond market.
For decades, those objectives could coexist reasonably well. Now they are beginning to collide. And Bitcoin is sitting right in the middle of that collision.
Federal Reserve Chairman Kevin Warsh went to Jackson Hole on August 28 and delivered a message that markets could not easily misunderstand.
Inflation is still too high.
The Fed’s preferred PCE inflation measure is running at 3.7% year-over-year, according to Warsh, while the six-month annualized rate is even higher at 4.1%.
The Fed’s target remains 2%.
Warsh was explicit:
“The Fed’s price-stability objective of 2 percent…is a firm, fixed target.”
And then came the sentence that matters:
“Otherwise, we have work to do.”
Translation:
The Fed is not ready to declare victory over inflation.
Warsh also stressed that short-term interest rates remain the central bank’s primary weapon and that unconventional measures should generally be reserved for genuine crises.
That’s the monetary-policy side of the story.
Then look across Washington.
The Treasury has a completely different problem.
America’s fiscal numbers are becoming increasingly difficult to ignore.
The Congressional Budget Office projects a federal deficit of approximately $1.9 trillion in fiscal 2026.
Not during a financial crisis. Not during a pandemic.
During an economy where unemployment remains low and economic activity is relatively strong.
Federal debt held by the public is expected to equal roughly 101% of GDP this year.
By 2036, the CBO expects that ratio to reach 120%, exceeding the post-World War II record.
And then there is the number that should make every investor pay attention.
Interest.
The federal government is projected to spend roughly $1 trillion on net interest in 2026 alone.
**By 2036? **Approximately $2.1 trillion per year.
Interest costs would rise from 3.3% of GDP today to around 4.6%, approaching the size of all federal discretionary spending combined.
Read that again.
America could eventually spend roughly as much servicing its existing debt as it spends across almost the entire discretionary federal government.
That changes the monetary equation. Because high interest rates don’t just slow consumers and businesses anymore.
They increasingly punish the federal government itself.
America’s debt crisis is no longer about an abstract $40 trillion balance — interest is now swallowing nearly one-fifth of federal revenue before Washington funds anything else.
Imagine you are the Federal Reserve.
Inflation is running well above target. The economy remains resilient.
Your textbook response is straightforward:
Keep monetary conditions tight.
Maybe tighten them further.
Maintain high real interest rates.
Convince markets that inflation will eventually return to 2%.
Simple. Except there is another player at the table.
The United States Treasury.
Every time old government debt matures, much of it has to be refinanced. And debt that was once financed at extraordinarily low interest rates gradually gets replaced by debt financed at today’s much higher rates.
That means the government’s interest bill keeps climbing.
Higher for longer starts sounding wonderful when discussing inflation.
It sounds considerably less wonderful when you owe tens of trillions of dollars.
That is where monetary dominance can begin turning into fiscal dominance.
Under monetary dominance, the central bank essentially says:
We will do whatever is necessary to control inflation. Fiscal authorities will have to adjust.
Under fiscal dominance, the relationship starts reversing.
The government’s fiscal position becomes so difficult that monetary policy increasingly has to accommodate it.
The question quietly changes from:
What interest rate does the economy need?to:
What interest rate can the government survive?
That is an entirely different monetary regime.
How Washington is sacrificing the fiat system to win the global AI arms race — and why hard assets are your only escape.
On August 19, the U.S. Treasury announced that it would at least double the size of its liquidity-support buybacks for longer-dated Treasury securities.
Maximum purchases in certain long-maturity sectors will increase from $2 billion to at least $4 billion per operation beginning September 9.
Treasury says the objective is to improve liquidity in longer-dated markets.
That explanation matters.
These aren’t QE-style purchases funded by newly created money.
The Treasury isn’t suddenly monetizing trillions of dollars of debt. But markets care about direction as much as scale.
Why?