Finance
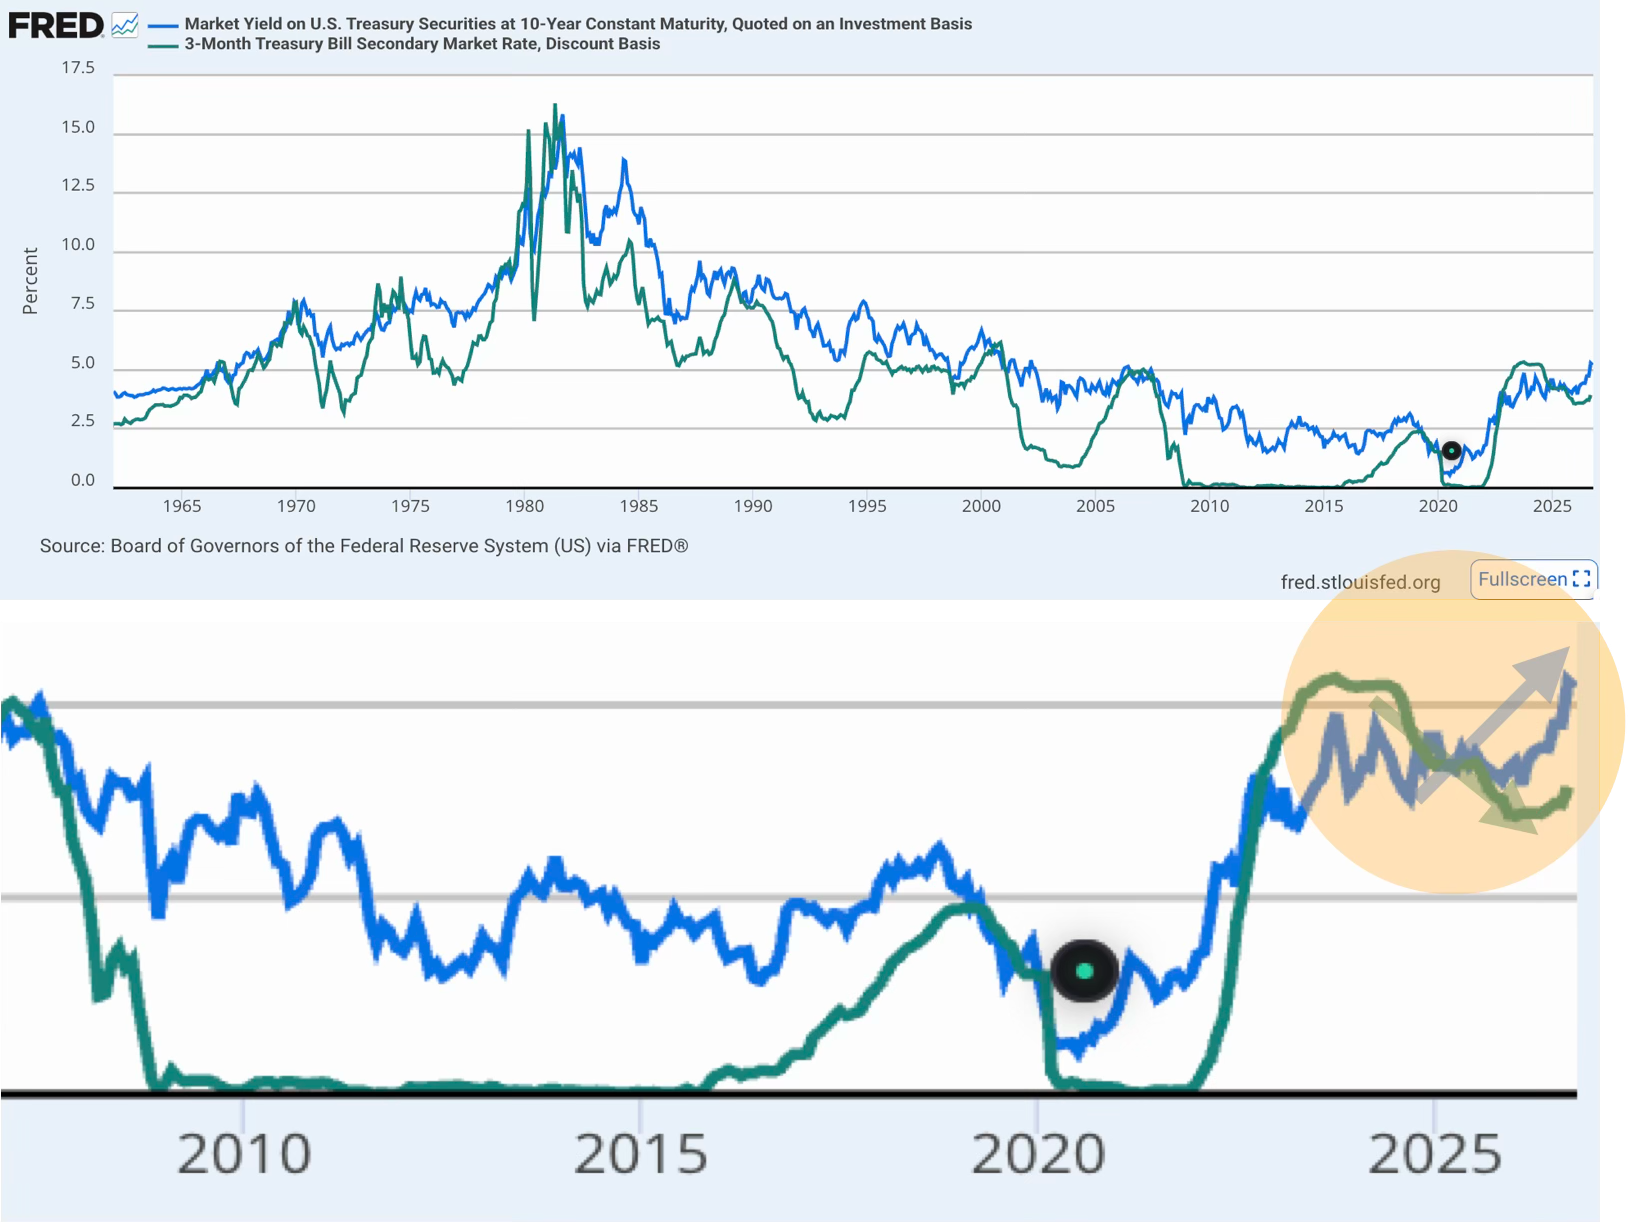
The First Time a Fed Easing Move Has Triggered a Sharp Jump in Long-Term Nominal Treasury Bond Rates: CHART OF THE DAY
Brad DeLong · DeLong's Grasping Reality: Economy in the 2000s & Before
Oct 15, 2026 · 2 min listen · Last updated October 15, 2026
S. S. Treasury interest rates bringing what looks to me like a premature uninversion of the yield curve. Is it the bond vigilantes cleaning their weapons in anticipation of having a Liz Truss Party for the arriving Chaos-Monkey-in-Chief? Or is it a very interesting but rather technical market microstructure phenomenon?
Listen · DeLong's Grasping Reality: Economy in the 2000s & Before
The First Time a Fed Easing Move Has Triggered a Sharp Jump in Long-Term Nominal Treasury Bond Rates: CHART OF THE DAY
0:00-1:37
Pick your daily storyteller
Subscribe to match with Theo, Jessica, Chloe, Mason, Brock — your voice, every brief.
Live · Kokoro-82M