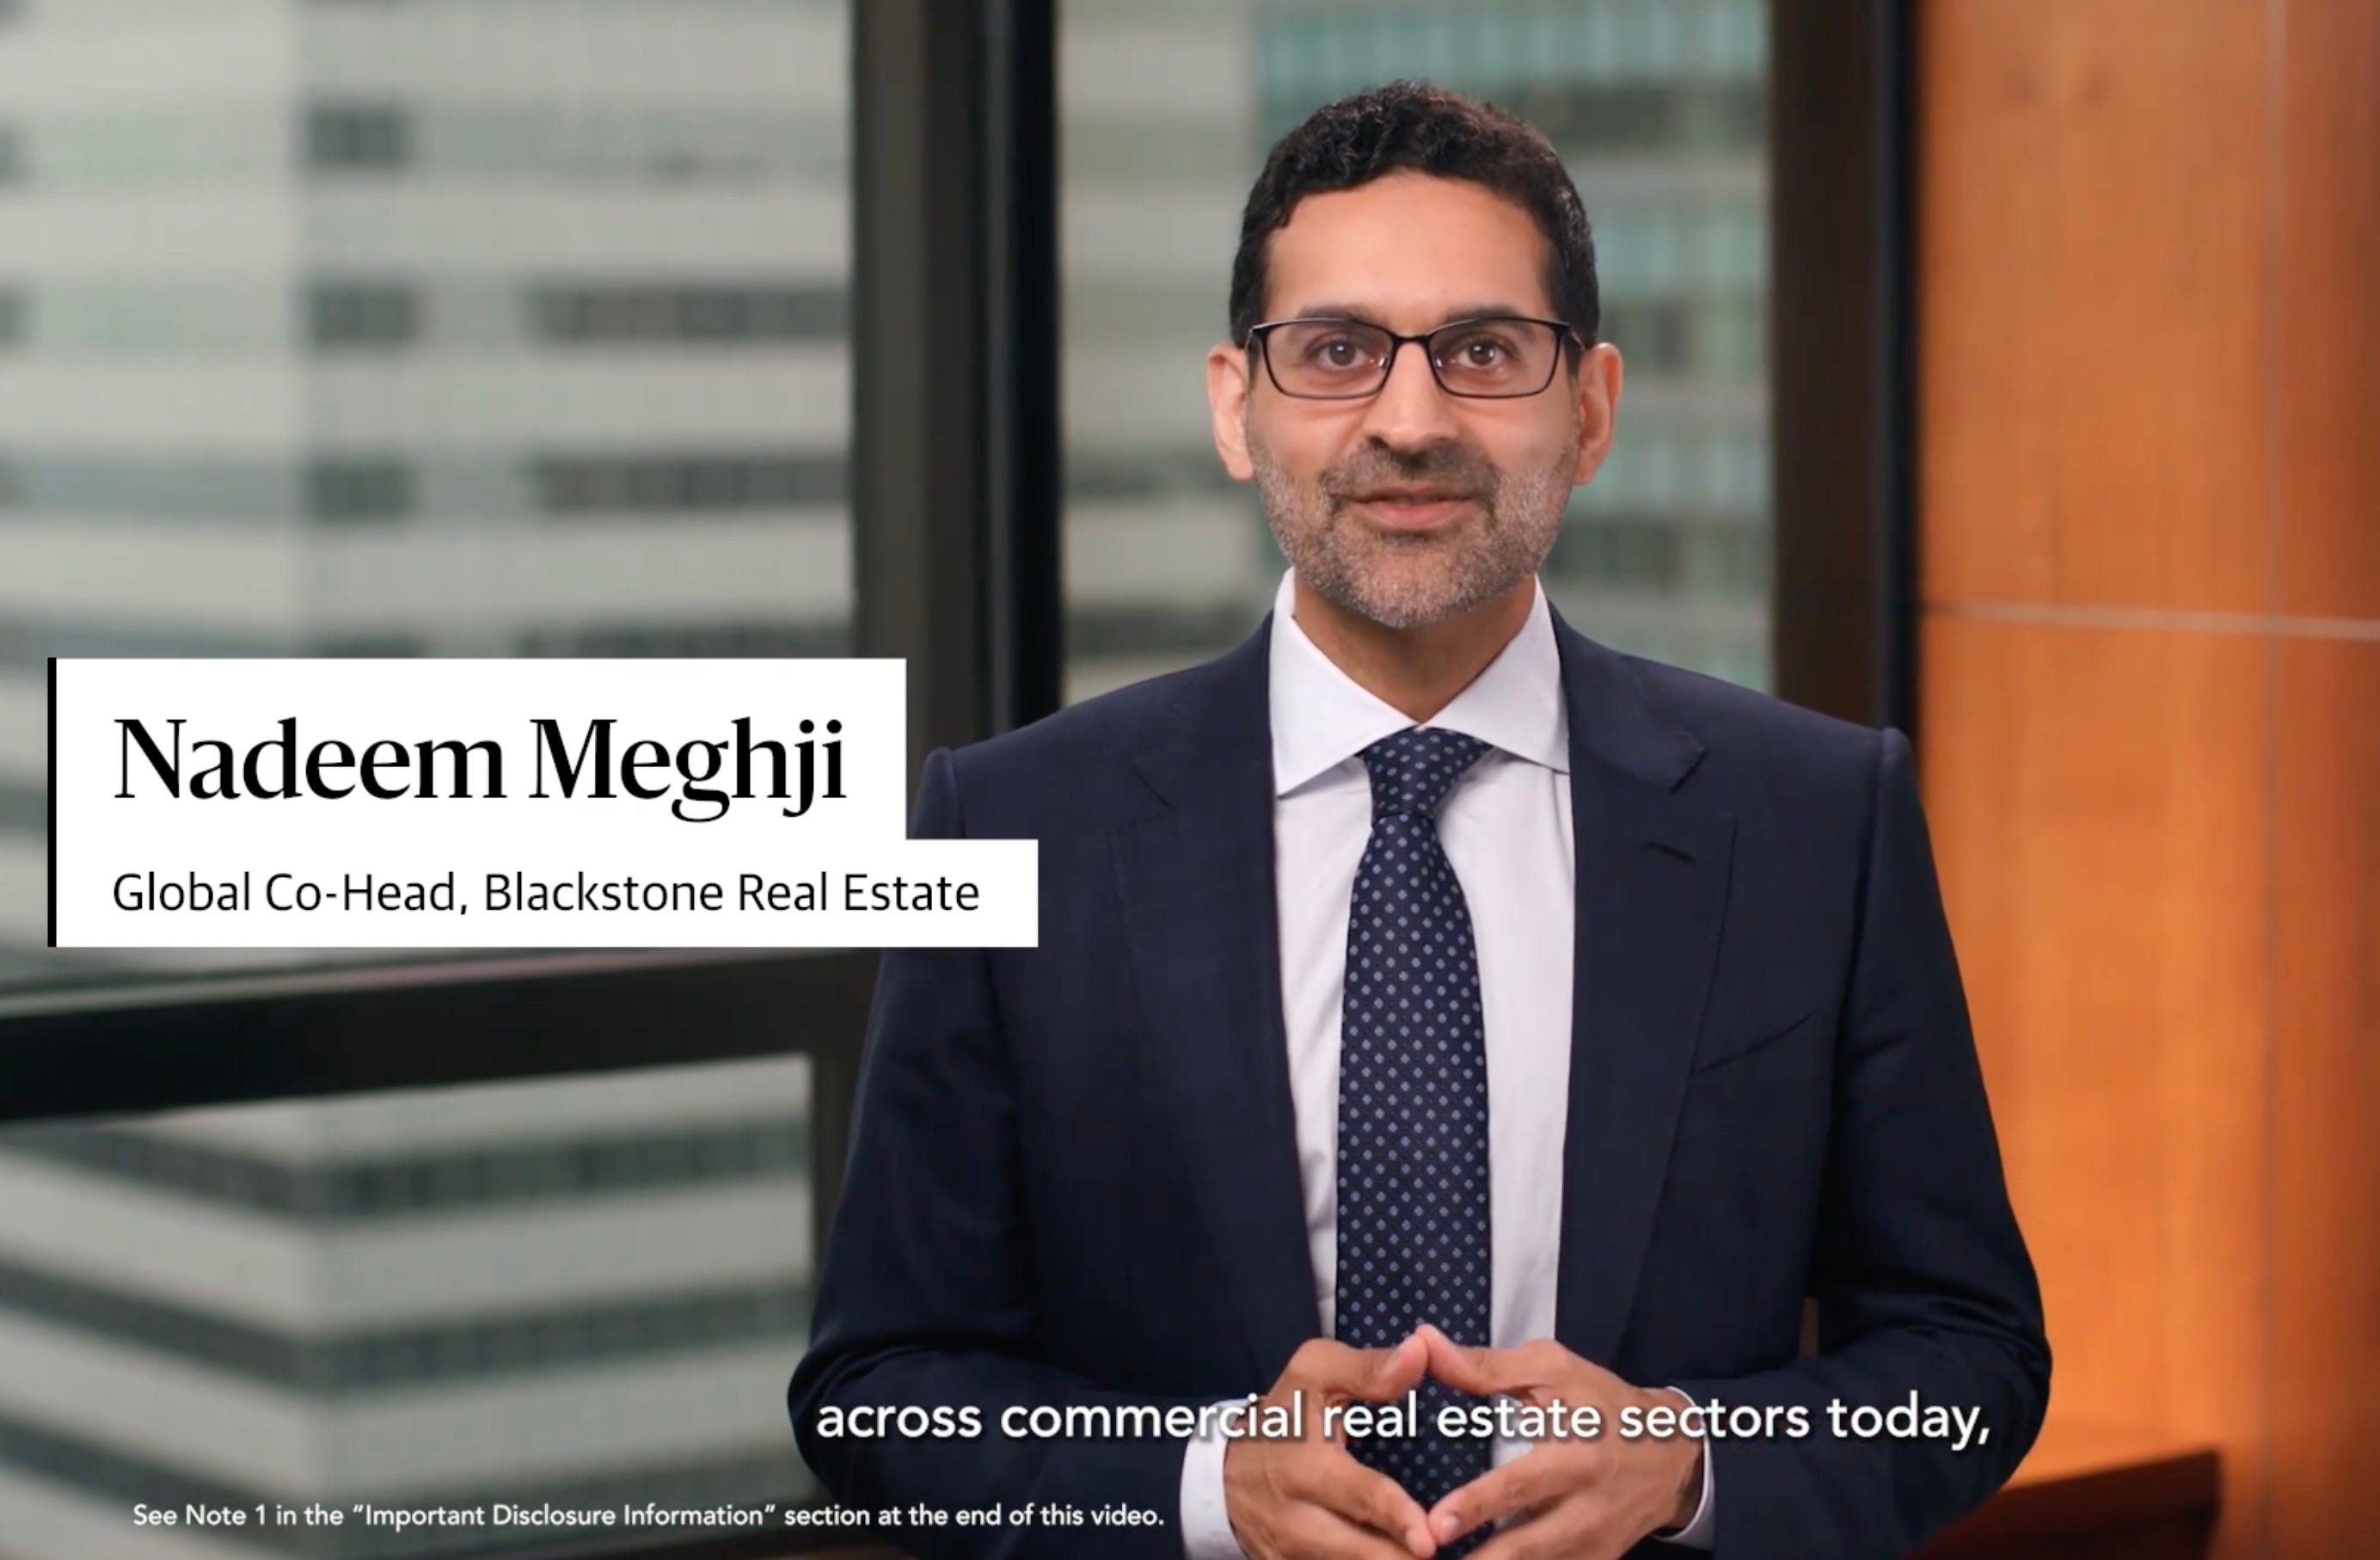
Head of Real Estate Nadeem Meghji is leaving Blackstone less than a year after taking sole control of its real-estate business, according to a new report from the * Wall Street Journal*.
The official explanation is a desire to spend more time with family. That may be entirely true. But when the head of one of the world’s largest real-estate investment businesses decides to leave after nearly two decades, and less than a year of becoming the boss of real estate, I think investors are entitled to wonder whether the timing tells us something.
His departure follows that of former co-head Kathleen McCarthy in 2025 and comes amid a broader turnover of senior real-estate executives over the past several years. Blackstone has named David Levine and Giovanni Cutaia as his successors, emphasizing the depth and continuity of its leadership bench.
Now that the corporate line is out of the way, the question the ole’ Q-Man finds interesting is this: why leave now, after just being promoted to a position you’ve ostensibly worked your entire career for? Surely when Meghji began low on the totem pole at Blackstone the goal was to find himself at the top of management, reaping all the perks that come with it. So why stay for less than a year?
The company line *could *be all there is to it. He could just want to spend more time with family. That’s a commendable aspiration as well. But just from a human psychology standpoint, people generally do not leave extraordinarily lucrative jobs when they believe the next few years are about to be the best few years of their careers. They can, and there are legitimate personal reasons to do so. But the financial incentives at this level are enormous.
If an executive believes the business is about to enter a spectacular upswing, with compensation and equity awards potentially worth millions more, walking away becomes a much more expensive decision. Look, family is important….so is millions more in compensation you can use to take care of said family.
I am not suggesting Meghji is forfeiting a specific amount of money. I have no knowledge of his personal finances or the terms of his departure. The point is simply that basic human psychology dictates to me that senior executives understand the value of staying through a major recovery. If they believe the next leg higher is right around the corner, the incentive to remain is usually substantial. BREIT’s investor material suggests there is a long track ahead of recovery for real estate:
There is another reason the timing catches my attention: executives also tend to find it difficult to leave during the absolute worst moments of a crisis. Departing while a business is visibly on fire can look like abandoning ship, particularly when employees, investors and clients are looking for leadership.
The more natural window is often after the immediate emergency has passed, when conditions have stabilized enough that a departure can be presented as an orderly transition.
It could be argued that this “eye of the storm” is where Blackstone’s real-estate business is today. BREIT, the firm’s giant nontraded real-estate investment trust, endured a prolonged redemption crisis beginning in late 2022. Investors wanted their money back faster than the fund could comfortably provide it, and withdrawals were restricted for more than a year.
Those pressures have since eased. According to the Journal, BREIT began meeting all redemption requests in early 2024, recorded its first positive quarterly net inflow in four years during the second quarter of 2026, and delivered an 11% net return over the past 12 months.
Those are meaningful improvements. Why leave at a point where BREIT appears to finally have stabilized and potentially be on an upswing?
I have to ask: what if BREIT is sitting in the eye of the storm rather than safely on the other side of it. The first phase of the real-estate problem was obvious: rates rose, property values came under pressure, financing became more expensive and investors wanted liquidity. The next phase could be more complicated, particularly if interest rates remain elevated and the private-credit problems I have been writing about begin to feed back into commercial real estate.
Real estate is a leveraged asset class. Higher financing costs do not disappear simply because a fund reports a positive return or redemption requests normalize. Loans still mature. Properties still need refinancing. Borrowers still have to justify valuations against a cost of capital that may be materially higher than the one prevailing when many of these investments were made. And now we’re talking about rate *hikes *instead of rate cuts (though tomorrow’s CPI report will give us more clarity on that).
And then there’s the fact that days ago it was reported that Blackstone’s BCRED private credit fund had to limit redemption requests at 5% of shares outstanding after receiving repurchase requests for ~10% of its shares outstanding.
Private credit, which has been falling apart for the better part of the last 12-18 months, is not some unrelated corner of the financial system. It is increasingly part of the machinery financing businesses and assets across the economy. If credit conditions tighten, lenders become more selective or investors begin demanding liquidity from private vehicles, the consequences can spill into real estate through refinancing availability, transaction volumes and asset prices.
That does not mean BREIT is about to experience another redemption crisis. It does mean that a period of relative calm should not automatically be confused with a durable recovery. And it means that the private credit portion of Blackstone’s business is worth watching closely.
Blackstone, of course, has enormous resources and a long history of making money during dislocations. The firm manages more than $600 billion in real-estate assets, and its investing BREP funds have substantial capital available. A difficult market can create opportunities for a manager with that kind of scale. But there is a difference between saying Blackstone can eventually profit from distress and saying the next couple of years will necessarily be easy for its existing portfolio.
That distinction matters when evaluating the departure of the person who has been running the business. I am not claiming Meghji is leaving because he sees something bad coming. I do not know that, and the publicly reported facts do not establish it. His stated personal reasons may be exactly what they appear to be. The departure does not, in and of itself, prove anything about BREIT’s valuations, liquidity or future returns.
But I’ll reserve my right to not reflexively dismiss the timing as meaningless. And I’ll also reserve my right fall back on the basics of incentives and psychology.
Whether it means something or not, a senior executive leaving after a long career, shortly after assuming sole leadership, following a period of industry distress and amid an uncertain refinancing environment is a development worth a second mention. The fact that the business has recently stabilized makes the timing more interesting, not less.
Maybe Meghji simply decided he had made enough money and wanted to enjoy his life. Good for him if that is the case. But if I were an investor trying to decide whether commercial real estate was about to enter a new golden age, I would not look at the departure of Blackstone’s real-estate chief and conclude that it was an obvious vote of confidence.
I’ll pass on one thing I’ve learned in my two decades following Wall Street, including a decade working on short/skeptical research. Sometimes the most important thing an executive tells you isn’t what the PR/IR team writes for him or her to say in an official statement on the way out. It’s that they decided now was the time to leave in the first place.
QTR’s Disclaimer**:** Please read my full legal disclaimer on my About page here.
Contributor posts, guest posts and curated posts have been hand selected by me, but have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author or reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.
I cannot guarantee the accuracy of any or all facts and figures included in this article though I made an effort to get them right. I have been wrong before and will be wrong again, and encourage you to always double check, do your own research and speak to a licensed financial professional, which I am not.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things I’m bearish on. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.
Starting in 2026, I have been attempting to no longer actively trade as much as I once did ( read my story here). My goal is for my investing/saving to be done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. It is possible I could own, have exposure to, or not own anything, at any point. In an attempt to lead a healthier lifestyle, I’ve also excluded myself from fantasy sports, sports betting, online and in-person casinos and prediction markets.
Any of my positions can change immediately as soon as I publish, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier. Hence, why I am a writer.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. Many times I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour.
Also, again I just straight up get shit wrong a lot. I mention it multiple times because it’s that important you understand.