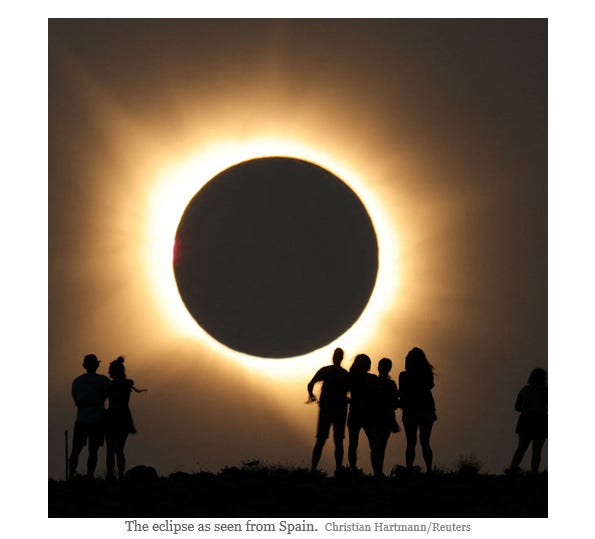
“Turn around, every now and then I get a little bit restless and I dream of something wild” (Bonnie Tyler,‘Total Eclipse of the Heart’)‘Restless’- we say it about kids, about behavior, sometimes even about our legs in bed. But sometimes it is applicable in a broader, more troublesome way ( even though a restless kid can be…well, trouble!); its the word for an electorate that keeps voting for the wildest thing on the menu, and the word for the past decade of geopolitics that restlessness has built. Uncertainty and loss of trust belief in the system as it stands has led to this. The President sits at a 33% approval, roughly six in ten Americans call him dishonest, and 69% say the country is ‘out of control’ (USA Today). His own party’s endorsed candidates are losing primaries. The other party is at war with itself, a socialist knocking off an incumbent in Michigan one week, an AIPAC-funded moderate knifing Cori Bush by 22 points the next (
Slate). Nobody fights to gain the center; everybody wants change, something wild.Point that same restlessness outward and you get the global map we now live in. A decade of it. Brexit, the strongman wave, the tariff wall, and now a regime in Tehran that has shut the Strait of Hormuz and done the arithmetic on how long it can hold. The world stopped dreaming of stability a while ago. It has been dreaming of something wild, and it keeps getting it.
Then.. look up. A total eclipse sits not only over Spain, but less entertainingly over this tape. The market is doing the one thing you must not do during one: staring straight at the bright disc. The S&P a whisker off a record. The VIX at 14.5, pinned near its cycle low. Single-stock skew on the floor.
: a payroll count that just went negative, a 30-year real yield at a record, a Treasury about to sell 30-year paper at the highest rate since 2001, and one tanker a day crawling through a strait that used to pass a hundred and thirty. Bright eyes staring at the disc. Shadow on everything else.The corona, the ring of fire nobody will turn to look at
We were all told as kids not to stare directly at the sun, lest it hurt our eyes. Just sayin…
**REGIME.**Relief rally, stocks and bonds bid, gold and the dollar sold. A rotation, not a flight.**THE SEAM.**Own the mispricing, not a direction. Vol at a cycle low while the long end screams.**THE BOOK.**Bull steepener through financials (long GS, long MET). Gold via the miners. A cheap QQQ tail into PPI.**Im Wrong If.**A soft PPI that rallies the 10Y through 4.60. Long end blinks, it all comes off.
Wednesday’s CPI printed in line, 3.4% headline and 2.5% core, and the reflex was to price relief. The front end took it. The long end refused. The 10Y firmed to 4.68 and the 30Y sat at 5.24, a nineteen-year high, into a Treasury sale of 30-year bonds this afternoon at the steepest financing cost since 2001.
Cool inflation did not pull the long end down, and a cool print that cannot rally duration is a fiscal tape, not a dovish one. Line up the safe havens and the regime settles fast: gold offered, the dollar offered, bonds bid, yen a shade bid. Money rotating out of the crisis hedges into both equities and duration, not fear, not a de-gross.
The mispricing is the calm wrapped around a bond market at a two-decade extreme, a labor count gone negative, and a Hormuz standoff the oil tape is busy pretending is over. Not the level of the S&P.
Own the bull steepener through financials, own gold via the miners, hold the long-end short into the auction, and carry a cheap QQQ tail into the PPI. The thing that kills all of it is the same soft PPI that rallies the long end, which is exactly what the tail is there to catch.
Consensus spent Wednesday afternoon congratulating itself. Core CPI at 2.5%, the slowest since early 2021, September hike odds bleeding back toward 40%, and the equity tape treating the whole thing as permission. Permission granted, apparently. The front end rallied, the reflex being that a benign print takes the Fed off the table. Zzzzzzzzz
The long end did not get the memo. The 10Y firmed rather than fell, and the 30Y held 5.24%, a level it last saw when George W. Bush was in his first term.
Sit with that. A disinflationary CPI landed and the thirty-year would not budge off a nineteen-year high, on a morning the Treasury has to sell twenty-five billion of exactly that paper at the highest yield since 2001.
**When the long bond ignores good inflation news, the message is that inflation was never what was pricing it.**The fiscal weight is. The supply is. The term premium demanded by a market financing a trillion in new issuance a year and rolling six trillion a quarter into an increasingly thin bid (TS Lombard, via the Telegraph).Foreign central banks and sovereign wealth funds, the buyers who used to show up without asking the price, have been thinning out. The buyer of size now is a hedge fund levered off the money-market complex, and that is a buyer who leaves the moment the carry stops working.
The ‘safe havens’ do the rest of the work. Gold offered, at 4,445 and slipping off its high. The dollar soft. Bonds bid, yields down a few. Yen a touch firmer. Some of them bid and some offered is a rotation, not a fright, and the specific pattern here, crisis hedges sold while duration and equities both catch a bid, is a market unwinding a fear premium, not building one. Which is the correct read of a benign CPI. Fine. The trouble is- what is the rotation standing on??
The rotation stands on a payroll count that already went negative. July printed minus twenty-three thousand against a consensus near plus ninety, and the back-month revisions quietly pulled another hundred-odd thousand out of May and June. Six of the last eighteen months now show outright job losses. Job growth over the trailing year averages twenty-six thousand a month, which rounds, generously, to nothing. Call it zero.
It also seems—confoundingly to me — to balance upon the Strait of Hormuz that the President and the oil tape have decided to declare open. Brent is off nearly two percent this morning, 87.40 and sitting near the session low after failing at 89.
The story attached to the fade is diplomacy: an Oman channel, Trump’s pivot from strikes to a naval squeeze, hope of a deal. Read the actual reporting and the hope evaporates. Tehran denied Islamabad’s ‘close to a deal’ line outright and floated holding the strait to 2029 (FT). The prediction markets have normalization by September 30 at 18%, down from 65% at the start of the summer (Polymarket). The tanker count through the strait is running at a trickle against a pre-war hundred and thirty. The premium is being sold on a hope the primary sources contradict. Resolved? Not hardly!
**Jimmy Carter Redux?**Here is where the Carter comparison earns its keep, a positioning input rather than a cheap shot. Jimmy Carter spent 444 days as the hostage of a Tehran that had correctly judged it could wait him out and deal with his successor. This administration is running the same play from the other side of the table, and losing it the same way. ‘Total control’ of the strait, the President says, while one ship a day gets through. The military campaign did not force capitulation, so the bet shifts to economic suffocation, the move of a side that has run out of better options.**Carter without the peanuts, and without the eventual release?**Tehran’s veterans of the Iran-Iraq war have said out loud they can run the clock to January 2029. A country that wants a deal does not price its demands to be refused. A country that has decided to wait does exactly that. For the oil complex, that means every session without a breakthrough adds premium by default, and the market that is busy selling the premium this morning is trading a headline, not the fundamental.
So I respect the tape ( to do anything else is a fool’s errand) and cut the position anyway. Discipline. Brent broke back below the line where the energy runner lived, the momentum that justified it is gone, and a trade that only works on a level it just lost is a hope wearing a ticket. The staged energy leg comes off. The re-arm sits at a 95 Brent print, on watch, not held. You can believe the premium comes back and still refuse to pay for the wait. Both things are true at once, and the book has to live in that tension rather than pretend it away.
What survives all of it is the long end. The payroll roll does not rally the thirty-year, because the thirty-year trades supply and term premium, not growth. Hormuz diplomacy does not rescue it either, because the fiscal bid problem is domestic. The one leg that never depended on Iran, never depended on the labor call, and was just confirmed by a CPI that could not move it is the fiscal long end. Own that. Everything else in the book is a way of owning that without betting the whole ticket on a single afternoon’s auction.
**PPI at 8:30 is the whole distribution, again.**June final demand ran negative on the month; July consensus is roughly plus 0.2%, core near plus 0.1%. A hot print re-cheapens the long end, confirms the fiscal short, and can lift the VIX off its floor, which is what the tail is there to catch. A soft print is the risk to the book: it rallies the 10Y through 4.60, broadens the tape, and de-fangs the higher-for-longer legs all at once. The market is pricing the mean and ignoring the variance. Sound familiar yet?**The 1pm auction is the fiscal stress test in real time.**Twenty-five billion of 30-year paper at the highest yield since 2001. A soft auction that tails and drags the 10Y back above 4.72 is the falsifier for the relief rally, not for my book. A strong one hands the melt-up a green light and puts the steepener on the back foot.**Hormuz has no off-ramp priced, whatever the oil tape says.**Iran floated holding the strait to 2029, the tanker count is a trickle, the prediction market has September normalization at 18%. Oil selling the premium this morning is the mispriced thing, not the auction.**The AI complex started sorting winners from bag-holders, violently.**Cisco down on an AI outlook that underwhelmed a fully-priced order book, Cerebras down 18% on a growth forecast that did not clear the bar, StubHub down 17%. Headline exposure to the capex boom stopped being enough overnight. Applied Materials after the close is the read on whether the sorting spreads to the picks and shovels.
**Cerebras down roughly 18% pre-market, and Cisco down about 6%, both after raising.**So what: the AI trade just changed character. Raising the outlook is no longer the price of admission, converting the order book to revenue and margin is. The market is done paying for exposure and has started paying only for delivery. Own the names turning the buildout into cash, avoid the ones still asking you to look three years out.**Maersk up as much as 8.7% to a four-year high on a second guidance raise in seven weeks.**So what: the freight tape is the cleanest read that Hormuz is a real, persistent dislocation, not a headline. Rates stay elevated because vessels are sailing the long way around a strait that has not reopened. The shipping tape and the oil tape disagree this morning, and the shipping tape is the one getting paid. Follow the freight.**UWM down about 30% on the week, forced into a 2.1 billion Oaktree rescue.**So what: a mortgage giant hedged a servicing deal it did not own, lost the deal, and sat on a naked long-duration bet while yields backed up on the war-driven inflation (FT). Non-bank financial plumbing cracks quietly at the edges first. Filed under: the long end is not a spectator sport, and the borrowing against it is not all visible.
The prior cash session tells the regime story cleaner than the index does. Banks led, the rate proxies lagged, and the split inside the tape is a steepener being expressed at the sector level.
**Financials.**Green and broadening, XLF at the top of its 52-week range with KBWB within a whisker of its own high. The bull steepener is the driver and the leadership is real, not a bounce. Leads the board.**Technology.**Bid at the index, AI-capex names vertical underneath (Nebius, CoreWeave, Super Micro all up double digits), but the dispersion opened hard with Cisco and Cerebras punished on guidance. The most crowded sector into the thinnest vol.**Energy.**The one giving back this morning as Brent fades off 89. The regime leg that just got cut, not the leadership it was two days ago.**Communication Services and Health Care.**The selective-megacap and defensive bids, greener than the rest of growth, health care still carrying a valuation argument after derating to the semis multiple.**Consumer Discretionary.**The funding short of the whole rotation. Rate-level pressure on the consumer, Macy’s down 3%, the group lagging while banks lead. The pair itself, expressed at the sector level: financials over discretionary.**Materials.**Mixed, copper firm on a genuine structural story (more below), the rest of the group along for the reflation ride.**Industrials.**Cooling after the defense-deal enthusiasm, though the munitions-restock theme has real legs into the budget cycle.**Consumer Staples.**Nobody needed the boring defense today.**Utilities.**The AI-power story fighting a 30Y at 5.24, and losing the tug-of-war on any day the long end backs up. Own the electron supply thesis through the merchant names, not the bond-proxy regulateds.**Real Estate.**The weakest corner, most rate-sensitive, wrong side of a backing-up curve and a CRE maturity wall nobody wants to price.
Behind the wall:
the FINANCIALS sleeve, where ‘financials at highs’ is a fee-and-NIM story sitting on top of a private-credit problem, with two intra-sector expressions netted to the winners over the losers, plus the BDC crack the public tape is still not marking.
Then FLOWS & POSITIONING, the breadth, the single-stock-vol gap, the systematic length and the crowded dollar that prove the complacency is real and measurable.
Then THE BOOK: kill switches with distance to each trigger, the cross-asset expressions with stops and falsifiers, the PPI decision tree, the conviction ranking, and the watchlist.
More, and the book as it moves, at
morningmusing.com.