Hello everyone, and Happy Halloween to all who celebrate! 🎃 We prefer Día de los Muertos 💀 in our household, and went off to see a colourful exhibition this morning with creative skeletons and, for some reason, butterflies, and to get some fresh “pan de muerto” for breakfast.
*You’re reading the free weekly send of the premium daily Crypto is Macro Now, where I re-share one or two of the week’s posts and add some non-crypto and non-macro links since it’s the weekend. *🌼
If you’re a premium subscriber, thank you so much! ❤
If not, do consider becoming one – for the cost of a weekly cup of coffee, you’ll get more regular commentary that filters the noise on crypto’s place in monetary and geopolitical realignment.
Sanctions and the tangent threat
Weekend: Indirect Halloween
Adjusted stablecoin volume (removing non-economic activity) grew 48% Jan-Sept 2026, despite flat stablecoin supply. The adjusted transfer count grew more than 70%, faster than value, reducing the average transfer size by 14%.
Download Allium’s ** State of Stablecoins and Payments Q3 2026**.
And get weekly onchain data and more analysis like this from the Allium Research team on Substack.
Because of a crazy schedule, I won’t be recording an episode of Stablecoins Around the World next week, but there is an especially interesting one on the calendar for the following – I’m going to keep you in suspense for now as to which area it covers, he he.
Previous episodes:
Stablecoins in the UKwith Rhys BidderStablecoins in the EUwith Marieke FlamentStablecoins in Switzerlandwith Ian SimpsonStablecoins in Brazilwith Aaron StanleyStablecoins in Japanwith Emily Parker
Coming up this week: central banks, macro, geopolitics and mayhem
Monday musings: Sanctions and the tangent threat
Eyes on Israel: a question of character
Eyes on China: cleaning house
Eyes on the US: an overlooked threat
The Fed: Empty patter and shrinking flexibility
Unrest in Spain: When a simmer becomes a boil
A couple of good reads
The Binance hack stress-test
Macro: strong growth, slowing consumption
One of my guiding principles for this newsletter is to focus on the bigger story, the why rather than the what, and how trends shape changes and vice versa. It’s the reason I don’t do headline summaries or news roundups, even though I’m often tempted – there are so many interesting things happening, so fast, but the noise can easily get overwhelming. And anyway, there are already other newsletters that do that well (I follow BitDigest for general crypto-AI headlines, BlockStories for institution-focused stablecoin/tokenization updates).
Sometimes, though, a single headline can eloquently capture the bigger picture with a real-world example.
Last weekend, while skimming Reuters, I came across the following story:
“Netanyahu rebuked for plan to use crypto to bypass economic sanctions”
Eleven words hint at *four *major stories, all relevant, all timely, all timeless.
One of the four can be put aside for later analysis perhaps, even if it is the most timely – will Netanyahu even be in power at the end of the year? Israel holds legislative elections tomorrow, and the polls show a divided country. It’s possible we could be approaching a regime change, even though by now we all know to not underestimate the staying power of Israel’s longest-serving leader.
Another – economic sanctions – is a topic that on its own has consumed volumes. Jess Hoversen often writes about this over on the excellent Hegemoney newsletter, and I can strongly recommend “Paper Soldiers” by Saleha Mohsin. I usually come at the idea of sanctions from the marginalization and pushback angle – most of us learn at an early age in school that if a tool of control is overused, people will find workarounds.
Which brings us to the third story in the aforementioned headline: an overlooked and yet increasingly important crypto use case.
I’ve written before about the role of crypto and blockchain in sanctions evasion – my take is that the technology offers an alternative that will eventually weaken the power of sanctions. This would of course benefit individuals and businesses that are bystanders in any conflict yet who survival more difficult; but it can also increase the likelihood of destructive kinetic battles as *successful *sanctions generally make boots on the ground less necessary.
Yet of *course *countries hit with restrictions on access to global trading channels will do what they can to protect themselves. Netanyahu knows that protection is a big part of his job. As he said:
“We need to prepare ways to evade banking sanctions through an alternative economic system… You know what that means — the currencies that can bypass them.”
Since he tends to see offense as the best defense, he is telegraphing to global leaders that their threats won’t deter him.
What’s more, his statement is credible. Israel has long been among the more crypto-friendly nations. It does not yet have a specific regulatory framework but legislation is progressing, new onramps are materializing, at least nine crypto service platforms are licensed to operate, and even banks are warming to the concept: Bank Leumi, the country’s largest financial institution, announced in August it will let customers trade BTC, ETH and SOL in its investment app starting early 2027. Also, Israel’s startup community, steeped in frontier technology and funded by deep VC pockets, has given birth to many key crypto infrastructure companies operating in global markets today.
So far, so astonishing. But the fourth embedded story in the Reuters headline is perhaps the most interesting of all. The “rebuke”.
This came from the Bank of Israel, the country’s central bank, which the very next day issued a statement to media that stressed:
“Cryptocurrencies cannot serve as a means of circumventing sanctions on Israel… The right course for Israel’s economy is to preserve economic relations with our main trading partners and focus on preventing sanctions and their negative impact on the economy.”
Of course, they’re right. Diplomacy is always better than its opposite. But sometimes it’s not an option, and even if it were, its outcomes are not reliable in today’s geopolitics. The US President is not known for keeping his word; the EU is going through a power struggle; regional alliances are shifting as fast as a game of musical chairs, without the fun.
It’s not what the bank said that I find interesting – after all, it has so much to lose in terms of global status were sanctions to be imposed, of course it wants to quell any speculation that might happen.
It’s more that it said anything at all. In so doing, it added extra fuel to the fire that Netanyahu started. And it positioned itself as more on the side of the global establishment than on the side of resilience.
Essentially, its panic let the world know that the threat of sanctions would work. Not exactly the “bring it” attitude often exhibited by Israeli leadership in recent years, and not exactly the signal of strength to Israel’s antagonists that its politicians would hope for.
The central bank’s reaction was echoed on Sunday in a statement signed by 109 economists, business leaders and former officials. Most of it was long-winded reminder of just how devastating economic sanctions would be, as if readers didn’t already know that. It also said that all Netanyahu has “to offer the Israeli economy is a bizarre solution typically found in criminal organizations that which will be of absolutely no use.”
Fellow fans of political thrillers, hear me out: An alternative narrative is that the pleas against the imposition of sanctions are a deliberate attempt to convey fear and desperation, distracting from the real resilience work going on throughout the Israeli business and financial community. The bleating feels too defeatist for a nation with an almost permanent wartime mentality. And the “crypto won’t work for sanctions evasion” stance goes against plenty of evidence to the contrary.
Then again, an equally plausible explanation is that the Bank of Israel is almost as scared of the emergence of an alternative financial system as it is of sanctions.
This threat is not so much the potential for a new type of payments technology to weaken the financial clout of Israeli banks. Rather, it’s the glimpse of a world that does not rely on central bank trust.
It’s wrong to worry about becoming irrelevant, in my view. The role of central banks in the finance of tomorrow will be different but still essential. By now, we’ve seen that full decentralization leads to chaos, and a steady, centralized hand is necessary to maintain the trust that underpins global flows. Even the distribution of blockchain-based currencies will need some coordination – after all, the central bank of Iran has been handling considerable volumes of USDT. And the Bank of Israel has been working on a CBDC for some years, although a decision has not yet been taken to proceed to production. CBDCs can also be a sanctions evasion tool.
Bottom line, the central bank’s rebuke to Netanyahu’s public acknowledgement of what is an obvious and inevitable resilience strategy could be an admission of vulnerability – “Israel would not survive sanctions” – or a rejection of any hint of a systemic restructuring. It could also be both, or something else entirely. But it feels like an arrow inadvertently pointing to a different story than we’re reading in the mainstream media.
See also:
Stablecoins and sanctions evasion(June 2026)
(in this section, I share stuff that has NOTHING to do with macro or crypto, ‘cos it’s the weekend and life is interesting)
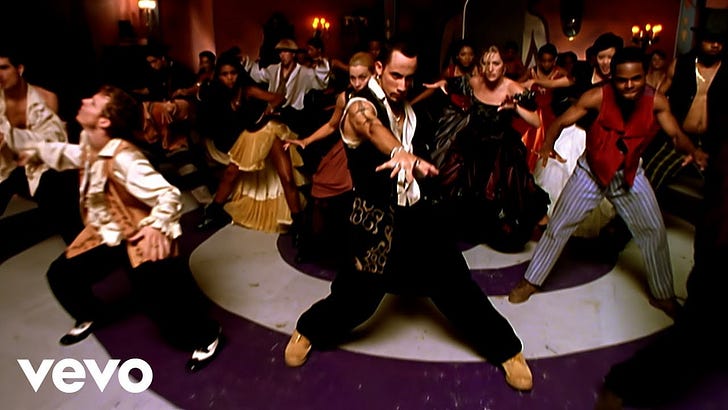
Some of you are probably getting ready for costumed festivities tonight – others (like me) just want to stay home and listen to spooky music. Here are some appropriate and yet not-obvious choices, songs that are not about Halloween but are nevertheless really Halloween-y, either in tone or the visuals or both.
Backstreet Boys – Everybody
Yeah Yeah Yeahs – Heads Will Roll
Rina Sawayama – Frankenstein
Rihanna – Disturbia
If you find this newsletter at all worthwhile, or even if you just like my excellent taste in music 😉, would you mind hitting the like button? ❤
DISCLAIMER: I never give trading ideas, and NOTHING I say is investment advice! I hold some BTC, ETH and a tiny amount of some smaller tokens, but they’re all long-term holdings – I don’t trade. Also, I often use AI for research instead of Google, but never for writing.