Hello everyone! I hope you’re all well and taking care of yourselves.
*You’re reading the free weekly send of the premium daily Crypto is Macro Now, where I re-share one or two of the week’s posts and add some non-crypto and non-macro links since it’s the weekend. *🌾
Production note: the free weekly will skip publication next Saturday as I’ll be travelling. For premium subscribers, I’ll also have to skip Thursday and Friday.
Why Pontes is not about CBDCs
The pretence of multicurrency platforms
Assorted links: Computism, art and language, TV ranking, biltong
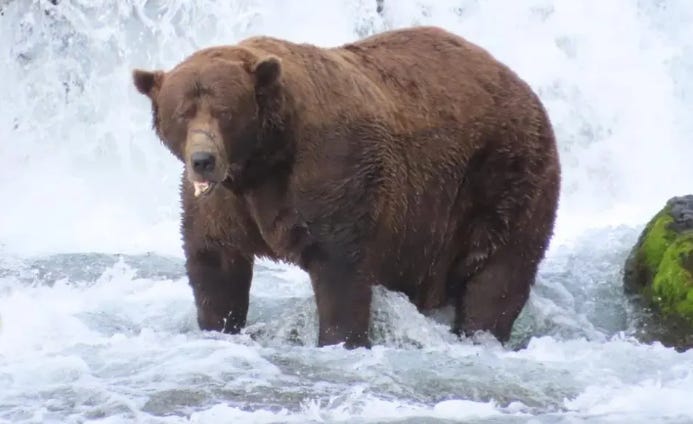
Weekend: Fat Bear Week
Where have stablecoins made the biggest inroads in cross-border flows? Indexed against fiat weight, stablecoin B2C runs at 5.3x in APAC, 3.5x in EMEA and 1.4x in the Americas.
Finde out more by downloading the full report: Stablecoins in Cross-Border Payments
Get weekly onchain data and more analysis like this from the Allium Research team on Substack.
In this series, I explore stablecoin systems outside of the US, talking to experts familiar with various geographies away from the mainstream glare. So far, I’ve recorded episodes on Japan with Emily Parker and Brazil with Aaron Stanley.
Next week: Europe! I’ll be talking to Marieke Flament, who knows more about this ecosystem than anyone I’ve ever met. You’ll find out why when the episode is released on Thursday. Meanwhile, check out her newsletter Currency of Power, which she co-authors with Nicolas Colin.
Coming up this week: geopolitics on stage
The pretence of multicurrency platforms
Why Pontes is not about CBDCs
Markets: a new vibe
Stablecoins: central banks vs banks
The changing face of banking
Basel report: bank exposure to crypto assets
Term of the day: prudential exposure
Markets: The squeeze tightens
Macro: In the driver’s seat
The fuel for stablecoin statecraft
Term of the day: diesel
This week, Europe took a big step forward on its path to tokenized markets. True to form, it did so through legacy institutions rather than by encouraging private innovation – but, to be fair, it solved a problem that had been holding the ecosystem back, and it did so with full establishment support.
The Eurosystem’s platform for tokenized asset settlement, known as Pontes, is now live.
Before I dive into its features, some definitions are in order.
The “Eurosystem” is the European Central Bank plus the national central banks of euro countries.
“TARGET Services” refers to the suite of real-time wholesale payment services managed by the Eurosystem. This launched in 1999 as group of linked national real-time gross settlement (RTGS) systems, became a single platform known as TARGET2 (short for Trans-European Automated Real-time Gross settlement Express Transfer, 2nd interation) in 2007-8, and in March 2023 was upgraded to the current multi-service structure that includes:
wholesale monetary operations (T2),
securities settlement (T2S),
instant payments (TIPS),
and unified collateral management (ECMS).
I know, there are a lot of acronyms in there.
With that out of the way, on to Pontes:
Its aim is to connect tokenized markets to central bank money. One of the main drags on the development of a deep tokenized ecosystem in Europe has been the lack of a legally recognized settlement token that reflects the efficiency of distributed ledgers.
The EU’s 2014 Central Securities Depositories Regulation (CSDR) says that central securities depositories (CSDs) must settle in central bank money where practical. The EU’s T2S securities settlement platform, through which most euro-area CSD transactions travel, settles only in central bank money. (In the US, settlement flows up to central bank money rails but often goes through commercial bank money settlement steps and batching before getting there, giving American firms more flexibility in settlement services.)
Stablecoins are not yet recognized as legal settlement for tokenized securities, although the EU’s painfully slow DLT Pilot Regime is exploring how they could be incorporated.
The EU law actually says that central bank money must be used for securities settlement “where practical and available”, and one could argue that in tokenized markets it was just not available, so stablecoin settlement could be considered legal – but institutional investors would understandably rather wait for more robust regulatory assurance, depriving tokenized markets of the desired liquidity.
Pontes offers an interoperability layer (the “Eurosystem DLT”) that connects tokenized assets to central bank money in two ways:
Via a “trigger” that executes a payment in fiat money on T2.
Via the exchange of tokenized central bank money, which then settles on T2.
Either way, finality is achieved in T2, as in the traditional settlement system.
The key advantages include:
Potential connectivity between a wide range of DLT networks and official settlement rails.
Technology agnostic – authorized market participants connect via APIs.
The exchange of securities and money is simultaneous (delivery-vs-payment, or DvP) even across distinct cash and asset layers, eliminating settlement risk.
It does not require a legal re-write of settlement laws, which would take years.
However:
Pontes is for now only operational during traditional banking hours, but the ECB has hinted that these will be expanded next year.
And, as yet, it does not enable smart contract functionality, it is purely a settlement connector. That said, participants can use whatever onchain features they want on their end.
A widespread misunderstanding is that Pontes is the engine for a Eurosystem central bank digital currency (CBDC). It isn’t. It is for wholesale transactions, which separates it from the retail-facing digital euro. But central bank money is not directly issued on the ledger – Pontes creates and handles a tokenized representation of balances held on T2. It’s closer to a deposit token than a new form of central bank monetary engagement.
I’ve also seen much commentary on how Pontes kickstarts the Eurosystem move towards onchain money. Not really. It’s not about digital currency at all, that’s in the background. Pontes is about tokenized markets. The aim is to find a way to efficiently fund tokenized asset transactions while complying with settlement regulation.
This speaks to the larger, quieter goal: a new capital market. The EU has been working on Capital Markets Union for decades and the progress has been minimal. Why? Because EU governments don’t want to give up control of their national markets. Luxembourg, which earns over 60% of its corporate income tax revenue from the finance industry, does not want to cede supervisory power to ESMA. Germany, a bank-heavy economy, does not want to see increased capital market financing detract from interest income on loans. I could go on.
So, we may have monetary union but not capital markets union, which is frustrating for anyone who cares about liquidity. Unfortunately, this is unlikely to change given the lack of incentives to do so, and will continue to hold the EU back in terms of innovation and capital market efficiency.
It’s not just about unnecessarily thin markets sending ambitious companies to the US to list and grow, with the resulting brain and capital drain that implies.
It’s also about distribution of opportunity – if we are a united economic bloc, then issuers should have access to the same pool of investors, and savers should be able to invest in any European-issued asset without tax penalties or legal friction.
And, it’s about euro stablecoins. Without a deep, pan-European bond market, we’re unlikely to get pan-European government bonds. This will mean that stablecoin issuers don’t have access to as safe a backing instrument as those in the US – which gives US stablecoins under the GENIUS Act an advantage over those under the EU regulation MiCA. Politicians will insist that MiCA compensates for the relatively thin debt market by requiring a significant chunk of stablecoin reserves to be held in bank deposits – as if bank deposits were safer than government bonds.
I’ve often written before about how I see onchain markets as a solution. If national interests insist on holding on to the current fragmented system, a new type of market supported by European authorities could perhaps satisfy the need for a pan-European structure.
In a speech last month, ECB Executive Board Member Piero Cipollone pretty much confirmed this is a key part of the plan:
“If we design and build an integrated European market for tokenised assets from the outset, the digital finance transformation
will allow us to leapfrog the fragmentation of existing legacy systems.” (my emphasis)
Pontes is a big step forward to bringing institutional liquidity to the tokenized asset ecosystem. Tokenized central bank money is not the goal here, onchain settlement for a pan-European marketplace is. Put differently, Pontes is not about money – it is about assets, trading, savings, investment and the creation of wealth.
See also:
Reform vs change(Aug 2026)EU tokenization and wholesale CBDC(Mar 2026)Tokenization: Building frustration(Apr 2026)The EU DLT Pilot Regime: let’s move faster(Feb 2026)
The recent BRICS Summit held in New Delhi did not, despite the declared ambition of Indian officials, produce a commitment to launch a group payment platform. Rather, the post-Summit Declaration rather tamely acknowledged work done so far by the BRICS Payment Task Force on studying the interoperability of national systems and the potential for local currency settlement – and it encouraged continued discussion “while respecting national priorities and acknowledging that there is no one-size-fits-all approach”. The overall vibe is one of “we have no consensus on the need nor the format”.
This is hardly a surprise. The BRICS is made up of such a diverse array of financial cultures and priorities that agreement feels elusive at best – and the larger the group gets, the less likely consensus becomes. For many, the situation is not urgent enough to overcome mutual distrust. And without broad interest, the effort and cost of the development will be hard to justify.
Even narrow collective platforms struggle. The mBridge platform, a CBDC-connector developed by the central banks of China, Hong Kong, Thailand, and the UAE under the umbrella of the innovation lab of the Bank of International Settlements (BIS). A small group, a limited scope, and even then, rumours of governance difficulties have been circulating for a while.
In June 2024, Saudi Arabia joined the project as it reached Minimum Viable Product (MVP) stage. A few months later, the BIS withdrew.
Last Sunday, the Financial Times reported that Saudi Arabia had exited the mBridge project. The headlines spread rapidly across mainstream media and social feeds, amping it up as a geopolitical signal. This was irresponsibly misleading (and further proof that fact-checking is a thing of the past): in May 2025, Saudi Arabia executed a proof-of-concept on the platform and then stopped participating. Over a year ago.
What’s more, it’s unlikely the decision had anything to do with US pressure – Saudi joined late, tested the plumbing, and probably realized there was no clear advantage beyond bragging rights. Not long after the mBridge test, the kingdom entered into a security pact with Pakistan, sending the message the US no longer has sway in its strategic decisions. Bottom line, Saudi Arabia backed out because it doesn’t need mBridge.
Why not? For one, it’s not desperately looking for alternative digital rails, unlike some jurisdictions. Most of its trade is invoiced in dollars, and it is unlikely to find itself on the receiving end of a dollar blockade. The riyal is pegged to the dollar, and the bulk of its reserves are in dollars. True, China is Saudi Arabia’s largest trading partner, and some invoice settlement is in yuan – but not enough to develop an alternative system. And, unlike the UAE, the kingdom has no clear CBDC strategy.
Meanwhile, mBridge has continued to grow – recent additions to the list of participants include Macau and Mongolia, and a South China Morning Post report in July said commercial launch was imminent.
But for now, the only active CBDC on mBridge is the digital yuan.
This raises an obvious question: are multicurrency platforms the answer to trade settlement? The BRICS nations seem to think not. And mBridge is so far behaving more like a digital yuan connector than a joint governance project.
But China already has one: the Cross-border e-CNY Transfer Services (CBETS) platform. Merging various e-CNY pilots, it launched as a rebranded entity in June with 26 direct participants. These were mainly Chinese institutions, but with direct operations in Hong Kong, Macau, Laos, Thailand, Singapore, Qatar and Brazil. Local banks in these countries can connect with CBETS participants to get access to e-CNY supply, transfers and settlement.
Or, they can apply to connect to China’s CIPS yuan payments platform. Last year, it started incorporating direct participants headquartered in foreign countries, starting with the UAE, Thailand, Singapore and Kyrgyzstan. South Africa’s Standard Bank, the largest financial institution in Africa with operations in 21 countries, is a direct member. The expansion continued in 2026, with additions from Angola, Mongolia and – earlier this month – Türkiye, Georgia, Malaysia, Rwanda, Uzbekistan and the Maldives. In August, Deutsche Bank became the first non-Chinese bank in Europe to be designated an RMB clearing bank, upgrading its direct CIPS connection (via its Chinese subsidiary) into an official European regional hub.
With so many global banks joining the fiat Chinese currency cross-border platform, and with China’s e-CNY platform expanding, you’re probably wondering why mBridge exists.
The thing is, for a multi-currency CBDC platform to be effective, it needs multiple currency CBDCs. That is much, much harder to orchestrate than just spinning up a token representing central bank money (itself legally and operationally complex). The underlying issue is the same friction that fragments today’s currency map: concentrated demand, influenced by infrastructure a…